The Fed raises interest rates for the first time in three years! How will the market react?
Wall Street Morning Brief: CPI comes in mildly, US stocks stage a deep V-shaped recovery; AI cloud, storage, and optical communications surge collectively.
Every Monday through Friday morning, PANews delivers insights on macro trends, US equities, AI, precious metals, and crude oil—using data to recap markets and trends to seize opportunities ahead.
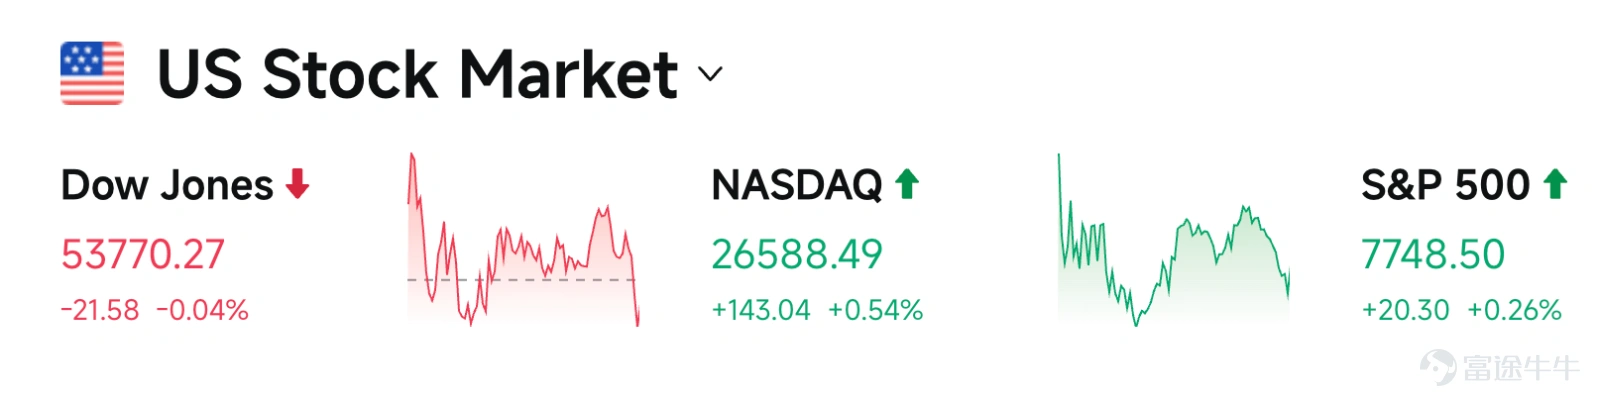
The three major indices finished mixed: the Dow Jones Industrial Average fell 0.04%, marking its third consecutive daily decline, dragged down by blue-chip stocks Home Depot and Microsoft; the S&P 500 rose 0.26%, approaching record highs; and the Nasdaq Composite gained 0.54%, with AI hardware, storage, optical communications, and new cloud computing re-emerging as the market's main themes.
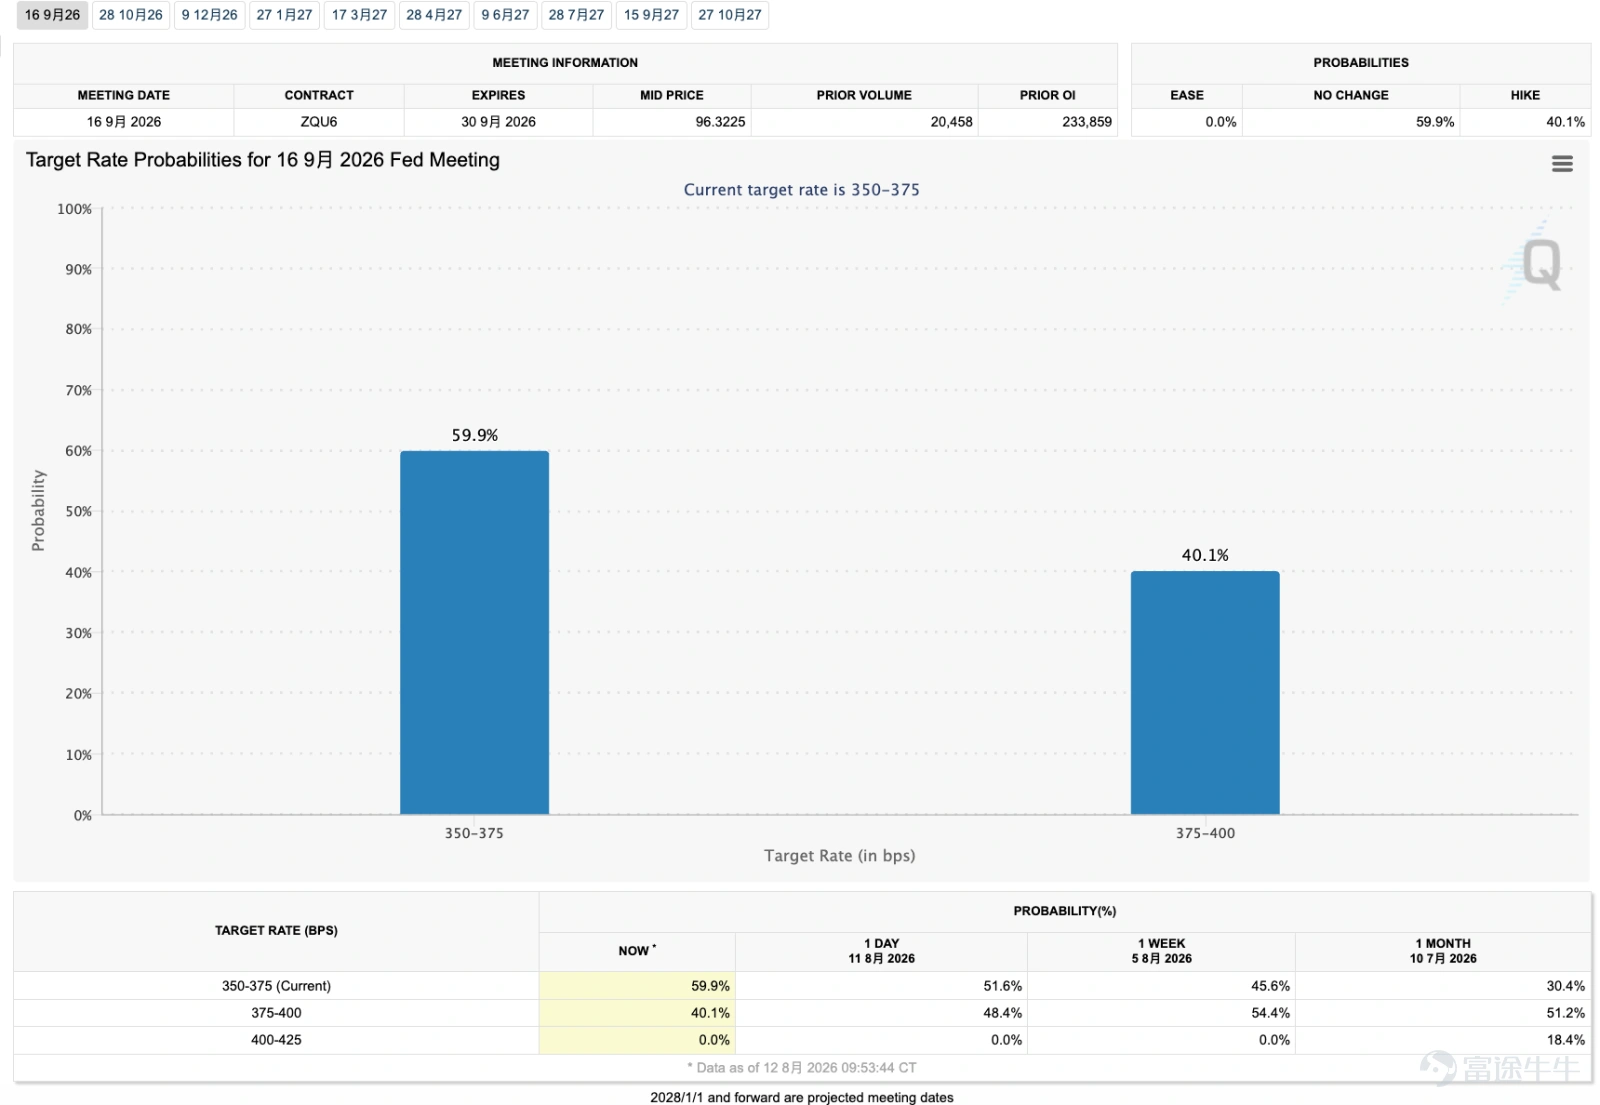
In July, US CPI rose 0.1% month-on-month and 3.4% year-on-year, while core CPI increased 0.2% month-on-month and 2.5% year-on-year. All figures met expectations, with the year-on-year core rate recording its slowest growth since March 2021.Combined with last week's weak non-farm payrolls data, the probability of a September rate hike priced in by money markets has dropped to 40%,while the probability of holding rates steady has risen to approximately 60%.
Goldman Sachs expects the Federal Reserve to likely hold rates steady for the remainder of the year;
Morgan Stanley's Ellen Zentner also noted that maintaining rates unchanged in September remains the baseline scenario unless subsequent data shows significant changes;
CICC pointed out that US inflation may have entered a new phase, with drivers shifting from supply shocks such as tariffs and oil prices to demand expansion driven by AI investment, potentially prolonging the duration of inflation.
Gold maintained its strong momentum, with prices staying above $4,400 and rising over 9% in August. Silver showed greater elasticity, rising about 14% in August, marking its eighth gain in 11 trading sessions, with spot prices hovering near $66.Citi reiterates its strong bullish stance on silver, expecting prices to potentially rise to $90 per ounce over the next 6-12 months,provided that tensions in the Strait of Hormuz de-escalate and the Federal Reserve pivots to a dovish stance, with investment demand stepping in to offset weak industrial silver consumption.
The oil market finally caught its breath, with WTI briefly falling below $81 and Brent dropping below $87; WTI had previously risen about 11% cumulatively over five consecutive trading sessions,as the market awaits tangible progress on the reopening of the Strait of Hormuz.The International Energy Agency warned that amid ongoing US-Iran conflicts, the global oil supply deficit this quarter could reach 1.8 million barrels per day, more than double previous forecasts, with the shortfall in 2026 potentially marking the largest in five years.
Trump claimed that the US has "complete control" over the Strait of Hormuz, but shipping data shows daily transit volumes of only around a dozen vessels, far below the pre-war level of 130, as Iran exerts actual control over navigation routes through sporadic attacks that create a "fear factor." War risk insurance premiums have soared to 10% of vessel value, with transit costs for a single large tanker reaching millions of dollars. Bret Kenwell from eToro warns that if oil prices break above $100, it will force the Federal Reserve to reassess its policy path.
The US fiscal situation is equally grim, with Treasury Department data showing thatthe federal budget deficit in July reached $432.3 billion, a year-on-year increase of approximately 48%,marking the largest single-month deficit since March 2021 and a record high for the month of July; the cumulative deficit for the first 10 months of the current fiscal year approached $1.8 trillion,with the CBO projecting the fiscal 2026 deficit to rise to $2.1 trillion.Interest payments on debt are becoming a fundamental pressure keeping long-term rates elevated. So far this fiscal year,the United States has paid $1.17 trillion in interest on its $39.9 trillion national debt,with net interest expenditures reaching $931 billion. Maya MacGuineas, President of the CRFB, stated bluntly that running a deficit exceeding $2 trillion during a non-recessionary period is "not normal."
Last night, capital clearly flowed out of traditional software stocks and some Magnificent Seven giants, rotating into cloud computing power, semiconductors, memory, and optical communications. Goldman Sachs data shows hedge funds continued to net sell software stocks, while long-term investors bought on dips, but market prices ultimately favored the former trend.
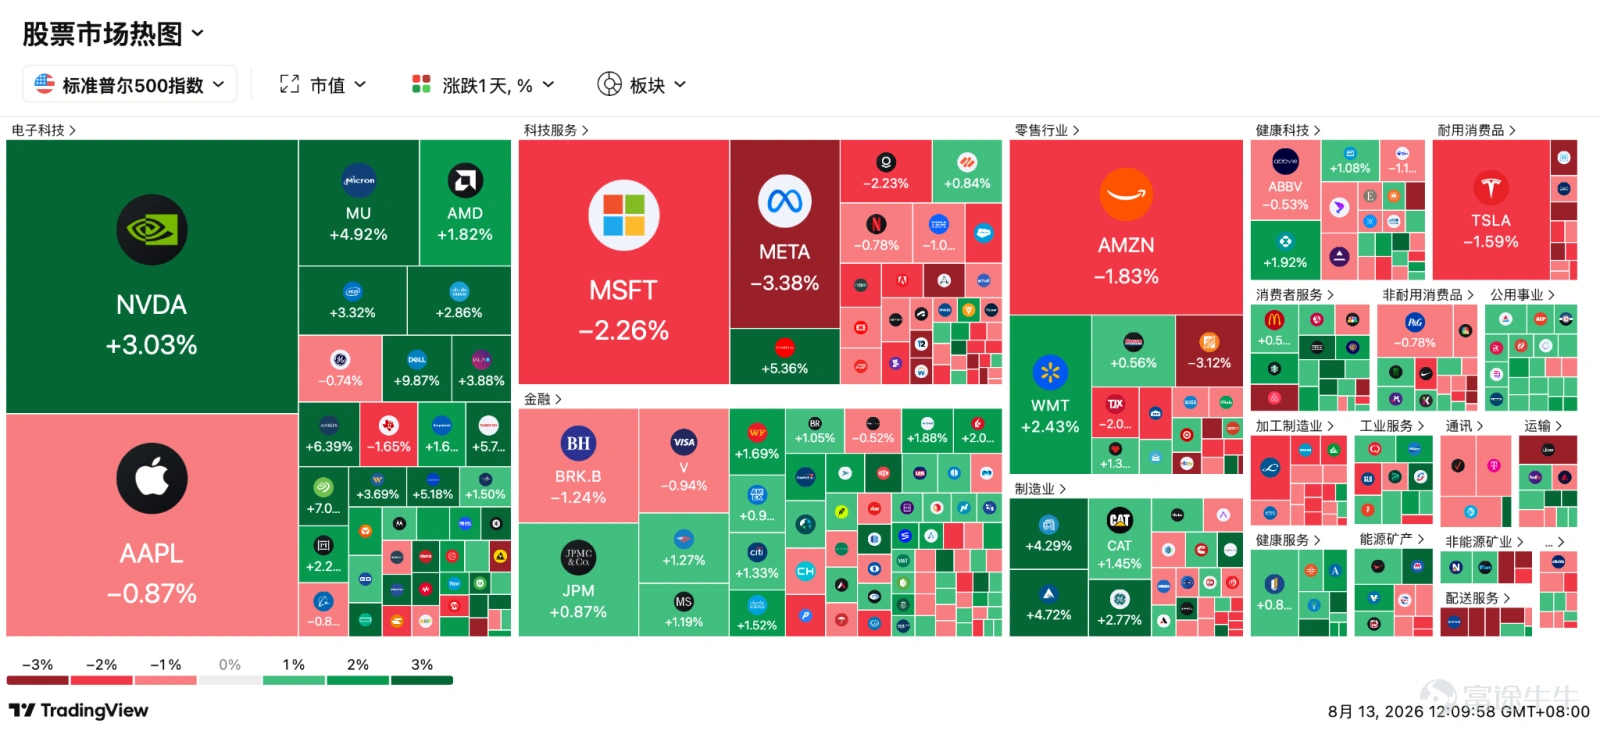
Conversely, the "pick-and-shovel" AI supply chain heated up across the board. The Philadelphia Semiconductor Index rose 2.49%; SK Hynix jumped 9.01%, Seagate Technology rose 7.03%, SanDisk gained 5.76%, Micron Technology advanced 4.92%, and Western Digital climbed 3.69%. In the optical communications sector, Lumentum surged 13.63%, Coherent rose 8.24%, Credo Technology gained 8.26%, and Corning increased 5.18%.
Cloud computing power emerged as the day's most frenzied sector: NEBIUS skyrocketed 34.14%, CoreWeave rose 19.28%, IREN gained 9.86%, and the Roundhill Neocloud ETF jumped 17.26%. CoreWeave's backlog reached $104 billion, and Nebius AI cloud sales grew 514% year-over-year, signaling that the market is regaining confidence that demand for AI infrastructure is not only real but is already translating into contracts and revenue.
Morgan Stanley's Michelle Weaver offered a more critical industry assessment: corporate applications of AI have begun generating quantifiable returns, but the true bottlenecks are shifting toward computing power, electricity, labor, and policy. Currently, about 25% of S&P 500 constituents can quantify ROI on AI investments, up from just 14% a year ago, indicating that AI demand is moving from the storytelling phase to the realization phase.
DeepSeek V4 ProThe official version quietly launched on the evening of August 12, with the model version switching to DeepSeek-V4-Pro-0813; meanwhile,SpaceX AI releases Grok 4.6The competition between the two has shifted beyond merely "who chats more intelligently" to focus on agent execution capabilities, complex programming, knowledge work, visual tasks, and token costs. The starting price for the Grok 4.6 API is just $2 per million input tokens and $6 per million output tokens, with SpaceX AI stating that this pricing is approximately half that of other frontier models.
The real pressure on OpenAI, Anthropic, and Google lies in the rapid commoditization of model capabilities, suggesting that the moat for AI companies may shift from the models themselves to computing power, ecosystem, and commercialization capabilities.
NEBIUS surges 34.14%: The company's Q2 revenue skyrocketed 454% year-over-year, with AI cloud business sales growing 514%, and it signed four contracts with an average value exceeding $1 billion. Short interest of approximately 24% further amplified the post-earnings short squeeze, driving the stock price rapidly from around $193 to $247.
CoreWeave jumps 19.28%:Q2 revenue more than doubled year-over-year, backlog reached $104 billion, and full-year capital expenditure guidance was raised. Strong orders and demand for computing power have become the core rationale for capital reallocating bets toward AI infrastructure.
Cerebras Systems surges 11.63%, but plunges over 17% in after-hours trading due to concerns over earnings structure. The company's Q2 core revenue grew 103% year-over-year, and cloud service revenue surged 287%, but core hardware revenue declined 23% year-over-year, revealing the volatility of hardware sales. The company announced a partnership with AMD and AWS to launch a "decoupled inference" solution to increase throughput by fivefold and raised its full-year guidance;
Cloud computing sector sees violent rally:IREN surged 9.86%, Applied Digital rose 4.92%, Hut 8 gained 2.24%, and the New Cloud ETF jumped 17.26%.
AI infrastructure player Super Micro Computer soared 19.02%:The company's Q4 revenue nearly doubled to $11.12 billion, net profit skyrocketed 503% year-over-year, gross margin significantly recovered from 9.5% in the same period last year to 17.5%, and its guidance for the next fiscal year far exceeded market consensus expectations;
Lumentum surged 13.63%:Q4 revenue increased 109% year-over-year, non-GAAP EPS rose 267% year-over-year, and guidance for next quarter's revenue and earnings comprehensively beat Wall Street expectations of 8% and 16%, respectively.
Coherent jumped 8.24%, but due to excessive short-term cumulative gains and overly high market expectations, its stock price fell about 3% in after-hours trading. Its Q4 revenue increased 34% year-over-year to $2.05 billion, gross margin improved to 40.2%, and guidance for the next fiscal year was also stronger than expected, but high valuations triggered profit-taking on the news.
Optical communication concept stocks generally moved higher, with Credo Technology surging 8.26%, Corning rising 5.18%, AAOI up 2.79%, and Marvell Technology gaining 2.25%.
The memory sector rose across the board:The Roundhill Memory ETF (DRAM) surged 7.68%. SK Hynix jumped 9.01%, Seagate Technology rose 7.03%, Western Digital gained 3.69%, and SanDisk climbed 5.76% (the company is set to hold its first Investor Day in 2026 following the spin-off). Micron Technology closed up 4.92% (facing a new patent infringement lawsuit filed by Netlist).
SpaceX surged 9.65%, reaching a market capitalization of $1.93 trillion. SpaceX AI, under Elon Musk, officially launched Grok 4.6, focusing on complex programming and long-duration agent tasks, with API pricing set at just half that of comparable frontier models.
Other major tech moves: NVIDIA closed up 3.03%, hitting its highest closing price since June, with a total market cap of $5.42 trillion;Ciscoreported Q4 revenue and EPS both beating expectations, with AI orders from hyperscale cloud providers reaching $4 billion. However, its after-hours stock price initially rose 8% before reversing to a 6% decline;Apple closed down 0.87%, as institutional research reports indicate that rising component costs could increase the bill of materials for the iPhone 18 Pro Max by $300. Additionally, reports suggest Apple plans to pay hundreds of millions of dollars to partner with publishers for news content to enhance the AI-powered Siri launching later this year;Google closed down 0.18%Google announced a restructuring of DeepMind, moving certain teams into its corporate structure to accelerate the commercialization of Gemini. Meanwhile, impacted by memory shortages, the entire new Pixel 11 lineup saw a $100 price increase. Meta fell 3.38%, Microsoft dropped 2.26%, Amazon declined 1.83%, and Tesla slipped 1.59%.
20:30 US July PPI:PPI will indicate whether businesses continue passing costs through to end consumers. If PPI runs hot—even if CPI remains mild—the market may worry about resurgent inflation; if PPI cools in tandem, the 'disinflation + easing policy pressure' trade narrative would strengthen further.
21:00 Western Digital (SanDisk) Investor Day:The market is focused on NAND supply-demand dynamics, enterprise SSDs, capital expenditure, the high-bandwidth flash memory roadmap, and long-term margin targets. With memory stocks under recent pressure, SanDisk's comments will directly impact sentiment toward Micron, Western Digital, SK Hynix, and A-share memory-related stocks.
JD.com’s Q2 earnings call, SMIC, and Hua Hong Semiconductor earnings.
U.S. SEC Form 13F quarterly holdings filing deadline:The filings will disclose long equity positions held by institutions such as U.S. hedge funds as of June 30. The market is closely watching whether large institutions have increased their allocations to AI, optical communications, power, energy, gold, and financial stocks. However, 13F filings have a lag of approximately one and a half months and only cover long positions, failing to fully reflect the true risk exposure of hedge funds.
Applied Materials’ after-market U.S. earnings release:The market is watching demand for DRAM, advanced packaging, wafer fabrication equipment, and changes in orders from China.
Bill Gates visits South Korea and discusses SMR small modular reactor cooperation with SK Group and HD Hyundai:The market is focused on nuclear energy, small modular reactors (SMRs), and their integration with AI data center power demand. If collaboration details advance, it would reinforce the 'AI power infrastructure' investment thesis.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comments
to post a comment
1