The Fed raises interest rates for the first time in three years! How will the market react?
Bitget UEX Daily Report | Fed Officials Turn Hawkish Again, CPI to Set Tone for September Path; U.S.-Iran Standoff in Strait of Hormuz Persists; NVIDIA Clarifies Financing Plans, Easing Market Concerns (August 12, 2026)
I. Key Headlines
Federal Reserve Updates
Fed officials strike a hawkish tone once more; tonight's CPI data will be pivotal in determining September rate hike prospects
Chicago Fed President Goolsbee emphasized that excessively rapid price increases are currently the biggest economic issue, describing the labor market as 'stable but not strong.'
Cleveland Fed President Mester stated that multiple rate hikes may be necessary to bring inflation back to the 2% target.
Markets are focused on the U.S. July CPI data, due Wednesday evening Beijing time, with headline inflation expected at 3.4% year-over-year and core inflation at 2.5%; CME Group’s FedWatch Tool shows roughly equal probabilities for a rate hold versus a hike in September.Market ImpactAmid hawkish rhetoric and ahead of key inflation data, short-end rate-sensitive assets are under pressure, risk appetite is turning cautious, and the CPI outcome will directly shape September policy pricing.
US-Iran maritime tensions escalate as Hormuz Strait impasse persists
Iran’s Secretary of the Supreme National Security Council Rezaei stated the strait will not reopen unless the US accepts ceasefire conditions—unfreezing assets and ending regional hostilities.
U.S. forces fired missiles at a Panama-flagged cargo vessel heading toward an Iranian port in the Gulf of Oman; Houthi militants attacked Saudi and Egyptian vessels in the Bab el-Mandeb Strait, resulting in crew fatalities.Market ImpactGeopolitical risk premium is supporting oil prices, concerns over supply disruptions persist, and inflation expectations are intertwined with safe-haven sentiment, leading to heightened short-term volatility in commodities.
Market sentiment remains bearish, though historical data points to potential upside room for a rebound.
The S&P 500 continues to hit new highs, yet in 20 of the past 25 weeks, short positions have exceeded longs, indicating institutional positioning lags behind fundamentals.
22V Research notes that historically, excessive pessimism has signaled positive returns over the subsequent 1–6 months; Wells Fargo & Co’s sentiment indicator is nearing the sell zone typically seen after extreme bullishness.Market ImpactThe disconnect between sentiment and fundamentals may create room for subsequent correction, but near-term moves remain constrained by CPI data and geopolitical risks.
SpotGoldApprox. USD 4,390 per ounce, +0.52%
SpotSilverApprox. USD 65.0 per ounce, +0.5%
WTI Crude OilApprox. USD 83.9 per barrel, +0.96%
Brent crudeApprox. USD 85 per barrel, +0.67%
US Dollar Index (DXY):99.86%,+0.05%
Driver AnalysisThe U.S.–Iran standoff in the Strait of Hormuz and Houthi attacks underpin oil prices, sustaining the geopolitical risk premium. Gold oscillates ahead of inflation data amid safe-haven demand, while silver trades relatively independently due to its industrial attributes. Hawkish remarks from Federal Reserve officials cap upside potential for precious metals. Institutional views suggest that in the near term, commodities remain driven jointly by geopolitics and the upcoming CPI release; elevated oil prices could reinforce concerns about sticky inflation, with asset linkages manifesting as: geopolitical tensions → oil price support → inflation expectations → repricing of interest rate paths.
BTC: Approximately $63,765, -0.43%
ETH: Approximately $1,884, +0.45%
Total cryptocurrency market capitalization: Approximately $2.27 trillion, -0.1%
Market liquidation situation: Total 24-hour liquidations amount to approximately $171 million, with $125 million in long liquidations
Bitget BTC/USDTLiquidation Map: Bitcoin is currently trading around $63,711. Dense long-position liquidations are clustered near the $63,000–$63,500 range; a break below $63,000 could accelerate long-side unwinding. Short liquidations are concentrated in the $64,000–$65,000 zone above; a breakout above $64,000 may trigger cascading short squeezes and push prices higher.
Bitcoin spot ETF net inflows/outflows: Net outflow of $145 million yesterday; dynamic net outflow of $424 million today
Driver Analysis: Declining risk appetite in U.S. equities and rising oil prices have heightened inflation concerns, exerting macro pressure on crypto markets. Bitcoin failed to hold the $64,000 level, while Ethereum showed relative resilience. Leveraged liquidations were predominantly longs, reflecting stop-loss pressure after upside momentum stalled. Institutional consensus points to a weak sideways trend; focus remains on tonight’s CPI data for its spillover impact on risk assets and shifts in ETF fund flows.
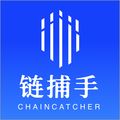
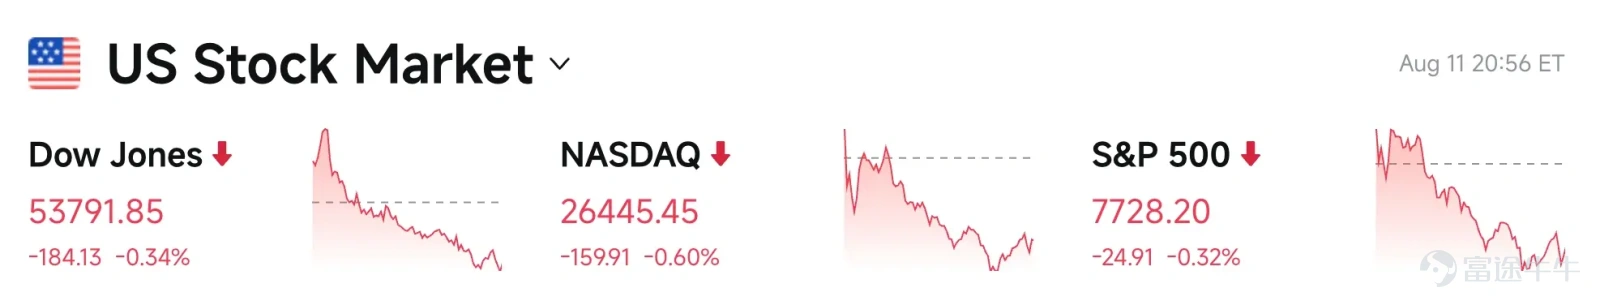
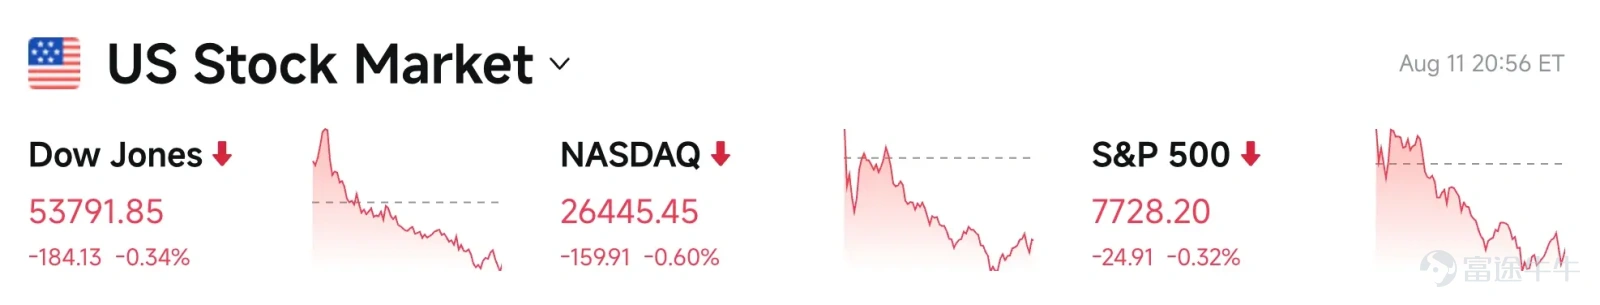
Dow Jones Industrial Average: Closed at 53,791.85, down 0.34%, marking its second consecutive daily decline
S&P 500: Closed at 7,728.20, down 0.32%
Nasdaq: Closed at 26,445.45 points, down 0.60%, with the technology sector under notable pressure
NVDA: Approximately $217.50, down 0.02%
AAPL: Approximately $304.91, down 1.09%
MSFT: Approximately $503.81, down 0.44%
GOOGL: Approximately $343.80, down 3.84%
AMZN: Approximately $272.27, down 2.09%
META: Approximately $599.12, up 0.71%
TSLA: Approximately $332.81, up 0.58%
Performance Summary and Driver Analysis: The Magnificent Seven showed divergent performance. Google and Amazon led declines, followed by Apple and Microsoft; Meta and Tesla rose against the trend. NVIDIA’s losses narrowed following Jensen Huang’s clarification on financing plans. Overall, the market was weighed down by the U.S.-Iran standoff and hawkish commentary, shifting focus from AI themes toward reassessing capital expenditure efficiency and macro risks, resulting in pronounced stock-specific drivers.
Semiconductors/memory were relatively resilient and partially rebounded
Representative stocksSK Hynix rose approximately 4.7%, Micron gained about 0.87%, and KLA Corp climbed around 4.0%.
Key DriversThe AI computing demand thesis remains intact, with capital flowing back into select hardware segments amid the broader market pullback.
Optical communication-related stocks strengthened broadly.
Representative stocks:CRDOup approximately 3.23%, Marvell up about 1.8%,AAOIup approximately 1.14%.
Key DriversAnticipated demand for AI optical interconnects is providing support, with sector rotation becoming evident.
Cloud service providers moved higher.
Representative stocks:NEBIUSup approximately 4.95%,CoreWeaveUp approximately 2.42%.
Key DriversCapital is returning to themes related to computing power leasing and AI infrastructure.
Event summaryThe market had previously misunderstood NVIDIA’s potential $500 billion computing power financing plan. Jensen Huang clarified on X: support would be limited to no more than 25% of a single project opportunity and would be based on residual value, constituting limited backing intended to supplement—not replace—independent underwriters. This clarification removed uncertainty, leading to a narrowing of the five-year credit default swap spread. Meanwhile, NVIDIA is reportedly developing Nemotron 4, an open-source model with trillions of parameters, aiming to expand its open-source ecosystem and drive GPU demand.CMEPlans to launch GPU computing power futures.Market AnalysisInstitutions believe the clarification significantly reduced concerns over credit risk, shifting market perception from a misreading of 'unlimited exposure' to an understanding of limited support. Analysts are now focused on the actual operation of the financing platform and how the open-source model boosts the ecosystem.Investment InsightShort-term sentiment recovery is favorable, but medium-term outlook still requires monitoring AI-related capital expenditure returns and supply chain execution.
Event summaryGoogle shares fell approximately 3.84%, marking one of the steeper declines among the Magnificent Seven. The market continues to digest the company's earlier upward revision in capital expenditures and the pace of returns on AI investments.Market AnalysisAmid hawkish macroeconomic sentiment and geopolitical uncertainty, institutions remain cautious on high-capital-expenditure tech stocks, emphasizing the need for cloud business growth to align with investment efficiency.Investment InsightFocus will be on AI revenue contributions and changes in capital expenditure guidance in upcoming earnings reports.
Event summaryApple declined approximately 1.09%, following the broader tech sector’s pullback. The market is watching its positioning within the AI and hardware cycles.Market AnalysisRelatively resilient but still weighed down by sector-wide sentiment; institutions are monitoring the iPhone cycle and the resilience of its services business.Investment InsightAs a relatively defensive tech holding, investors need to track progress on new product launches and the implementation of AI features.
Event summaryMeta rose approximately 0.71%, outperforming other members of the Magnificent Seven.Market AnalysisInstitutions may hold a relatively optimistic view on its advertising strength and AI-driven efficiency gains, leading to some short-term capital inflows.Investment InsightWatch for marginal improvement signals in its advertising business and AI investments.
Event summaryTesla rose approximately 0.58%, showing resilience amid a broadly pressured market environment.Market AnalysisThe market remains divided on its delivery outlook and AI/robotics narrative, with short-term performance driven more by individual stock fund flows.Investment InsightVolatility remains high; monitor actual progress in Robotaxi and energy businesses.
1. U.S. Energy Information Administration (EIA) Short-Term Energy Outlook Report: WTI crude oil price forecast for 2026 revised upward to $80.88 per barrel from $76.26 previously; 2027 forecast raised to $65.39 from $60.76. Brent crude price forecast for 2026 increased to $86.81 per barrel from $81.91 previously; 2027 forecast raised to $69.39 from $64.76.
2. South Korea's Kiwoom Securities has simultaneously lowered target prices for Samsung Electronics and SK Hynix. Concerns are mounting that the memory semiconductor industry has passed its peak cycle, prompting an increasing number of brokerages to revise down their target price expectations for these two Korean market leaders.
Kiwoom Securities lowered its target price for Samsung Electronics to KRW 350,000 from KRW 390,000 the previous day, and reduced SK Hynix’s target price to KRW 2,100,000 from KRW 2,200,000, while maintaining a 'Buy' recommendation for both stocks.
3. According to Fox Business, Phong Le, CEO of Strategy, said the company will resume purchasing more Bitcoin for the remainder of this year.
4. Pokémon trading cards have outperformed both the S&P 500 and Bitcoin year-to-date. Meanwhile, a wave of emerging blockchain platforms is betting on tokenization to transform the roughly $13–15 billion collectibles market, aiming to enhance liquidity, ownership records, and settlement efficiency for physical collectibles.
5. Eric Balchunas, senior ETF analyst at Bloomberg, stated that when investors physically convert Bitcoin into shares of a spot Bitcoin ETF, they do not currently recognize capital gains; however, their original cost basis and holding period carry over. Thus, this mechanism essentially defers taxes rather than avoids them. The same process can also work in reverse, allowing ETF shares to be converted back into Bitcoin.
Evening
United States
July CPI (headline/core)
⭐⭐⭐⭐⭐
Wednesday, August 12
★★★★★ The U.S. releases July CPI data (market expects headline YoY ~3.4%, prior 3.5%; core YoY ~2.5%, prior 2.6%; MoM headline ~0.1%, core ~0.2%), taking over from last week’s NFP as this week’s most critical macro data, directly influencing September Fed rate hike pricing (currently implied probability ~44%).
Tencent reports earnings (focus areas: gaming, advertising, fintech, and AI capex/HunYuan progress);
★★★★Coherent、CiscoNEBIUS after-hours (and partially pre-market) earnings report, testing demand for AI networking equipment and high-speed optical communications; API/EIAcrude oil inventories, with IEA and OPEC monthly reports densely scheduled for release.
Thursday, August 13
The U.S. releases July PPI and weekly initial jobless claims;
★★★★★ Western Digital (SanDisk) Investor Day (evening Beijing time), focusing on NAND supply-demand dynamics, capital expenditure, High Bandwidth Flash (HBF) roadmap, and long-term margin targets—setting the tone for the memory sector;
Google's Made by Google event (Pixel 11 series and wearables, with deep Gemini integration);
Fed officials Hammack and Barkin to speak;
★★★★ Applied Materials (AMAT) after-hours earnings report, with focus on wafer fabrication,DRAM, advanced packaging, and guidance on semiconductor equipment spending; concurrent earnings from JD.com, SMIC, Hua Hong, and other China-concept/semiconductor names.
Friday, August 14
★★★★ US July retail sales MoM, preliminary August University of Michigan consumer sentiment index, and 1-year inflation expectations—testing consumer resilience following signs of labor market cooling;
Deadline for US institutional Q2 13F filings—monitor shifts in large funds’ allocations across tech, energy, and other sectors.
Investment bank analysts believe that hawkish comments from Federal Reserve officials and the upcoming CPI report constitute key near-term variables. Combined with the ongoing stalemate in U.S.-Iran maritime tensions, market risk appetite has turned cautious. Geopolitically supported oil prices could reinforce concerns about sticky inflation. NVIDIA’s financing clarification alleviated some credit concerns, but the broader tech sector remains pressured by capital expenditure efficiency and macro repricing. Cryptocurrency markets are under pressure alongside other risk assets. Strategically, it is advisable to remain flexible ahead of data releases, prioritize monitoring how inflation outcomes transmit to interest rate expectations and risk assets, and maintain caution toward high-valuation growth stocks.
Disclaimer: The above content has been compiled by AI-powered search and verified only by human review prior to publication. It does not constitute any form of investment advice. Data presented herein may inevitably contain inaccuracies; please refer to real-time market data for accuracy.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comments
to post a comment
1