Anthropic's annual revenue surges to RMB 100 billion; IPO postponed to November

Revenue has nearly septupled in seven months! Anthropic races toward its IPO, but will the market accept its high valuation?
The US IPO market may soon see another mega-deal.
Anthropic, the AI company behind Claude, has secretly filed for an IPO,currently in a fast-moving stage, but the specific timeline has not been fully finalized.。Recent reports are conflicting: The Financial Times states that the S-1 could be made public as early as this week, with an IPO launch expected between late September and early October; Reuters suggests that the prospectus release may be delayed until late September, with IPO marketing starting as early as mid-October.
Although the two media outlets differ on the timeline, they point to the same fact:Anthropic has entered the final preparation stage before going public.
The first pure-play frontier large model company may finally be going public.
Over the past three years, investors have participated in the AI rally through various channels.
$NVIDIA (NVDA.US)$ 、 $Broadcom (AVGO.US)$ Representing AI chips and infrastructure. $Microsoft (MSFT.US)$ 、 $Amazon (AMZN.US)$ 、 $Alphabet-C (GOOG.US)$$Alphabet-A (GOOGL.US)$ Representing cloud computing and massive AI capital expenditures. $Palantir (PLTR.US)$ 、 $Salesforce (CRM.US)$ Capturing AI applications and software commercialization.However, frontier foundation model companies at the core of the industry chain have long remained in the private market, with OpenAI and Anthropic being the most typical examples.
Even though investors are very bullish on the development of Claude, ChatGPT, and AI Agents, it is difficult to find a direct proxy in the public market whose revenue is highly correlated with model inference volume, token usage, and enterprise AI penetration.
Anthropic's IPO could change this. OpenAI also secretly filed for an IPO in June, but at the current pace, Anthropic still has the opportunity to enter the public market first.For investors, it offers a previously scarce exposure, allowing them to directly trade on the commercialization growth of frontier model companies.
Growing approximately sevenfold in seven months, what is Anthropic experiencing?
Currently, the most compelling figure for Anthropic in the eyes of capital markets is its revenue growth rate.
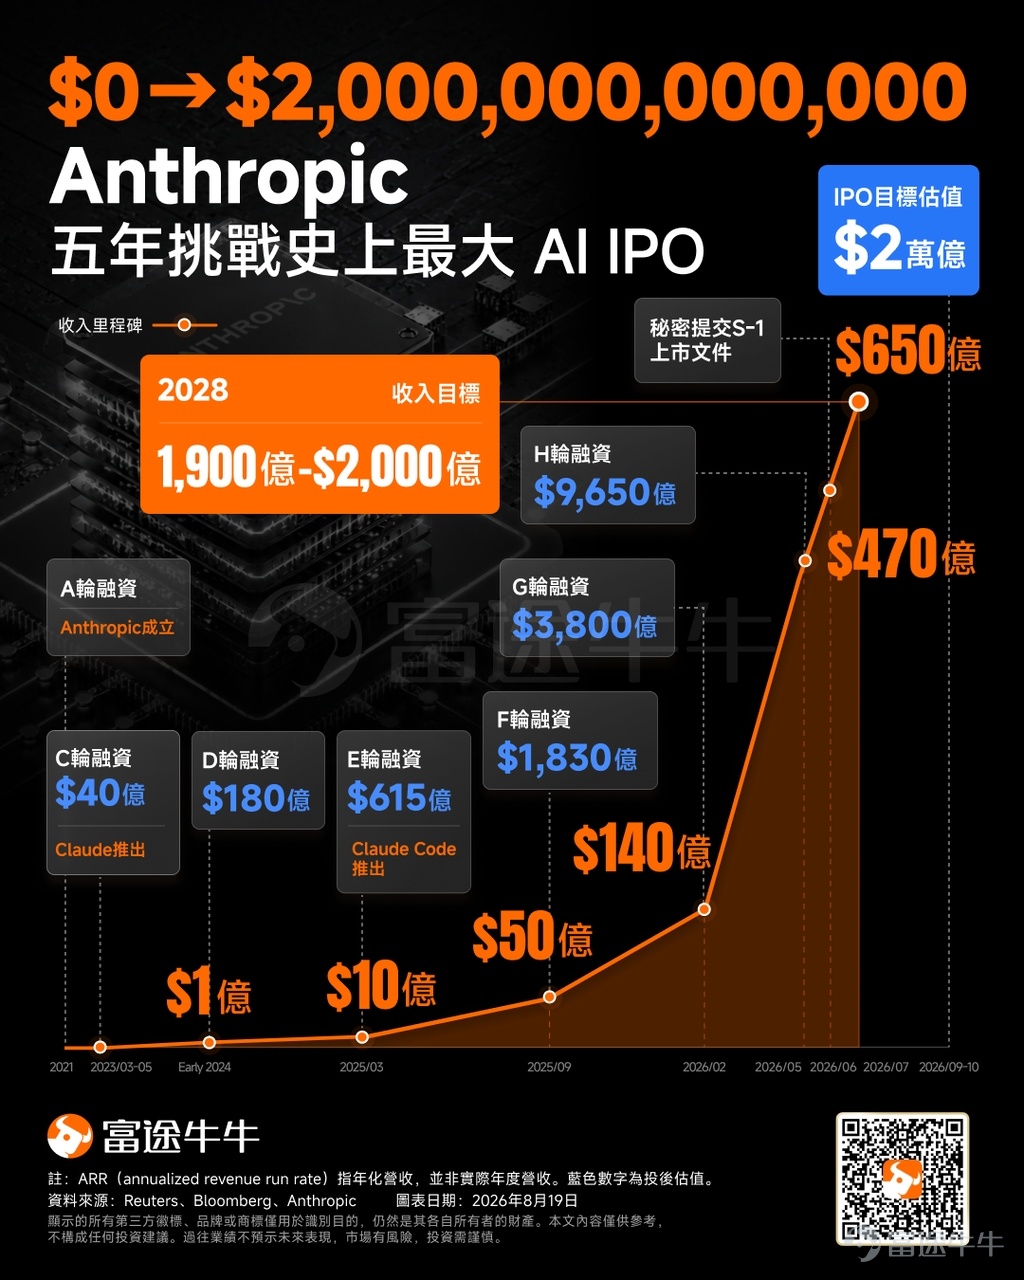
By the end of 2025, Anthropic's annualized revenue run rate was approximately $9 billion. It surpassed $47 billion in May of this year and exceeded $65 billion by the end of July. In just seven months, it grew more than sevenfold. When Anthropic closed a $65 billion financing round in May, its post-money valuation reached $965 billion. According to reports,current market discussions suggest a potential IPO valuation as high as approximately $2 trillion.
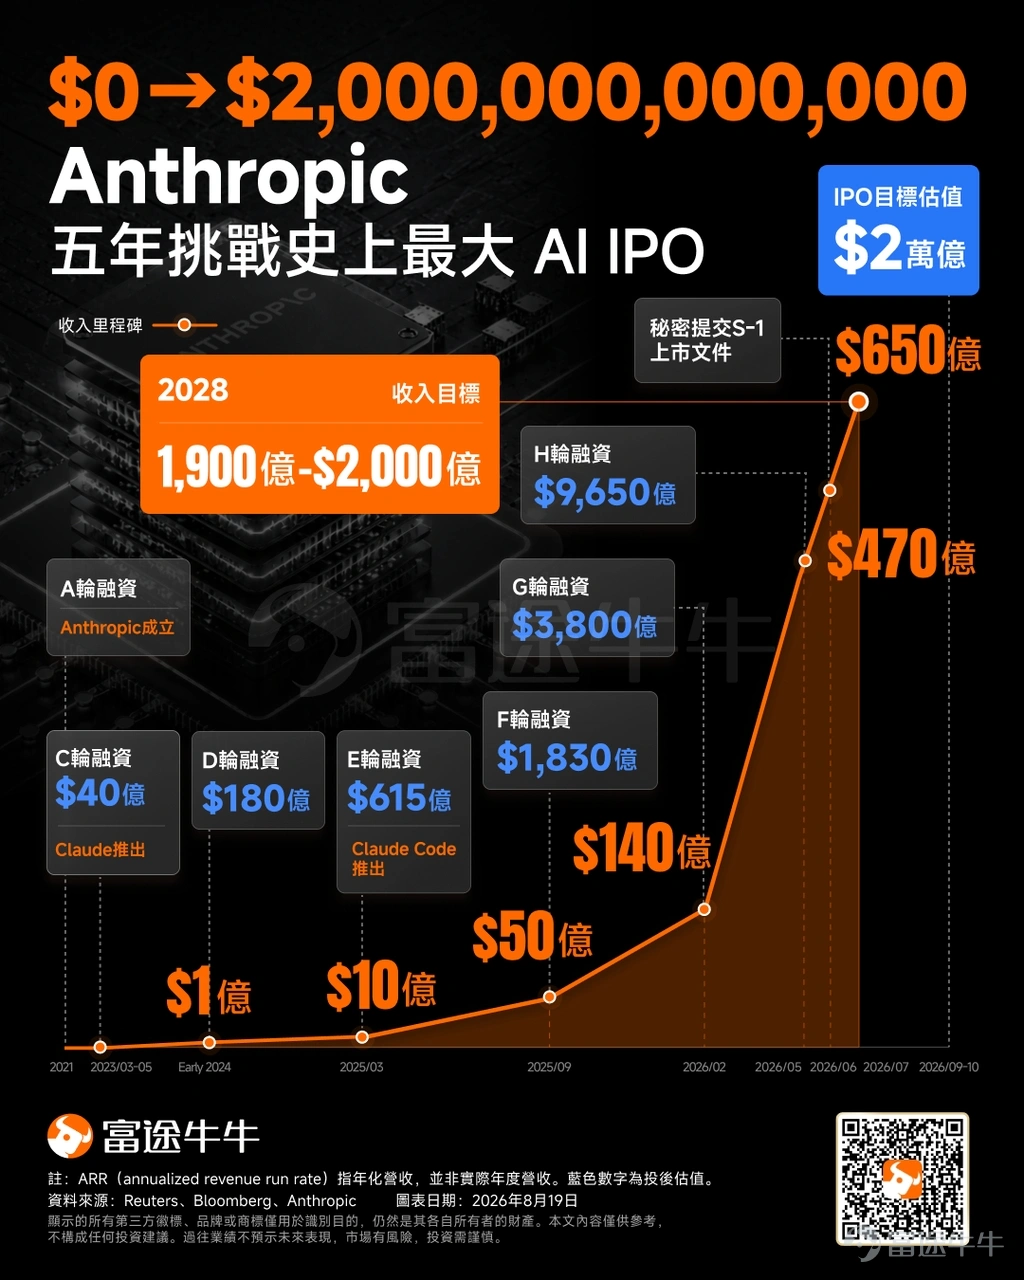
It is important to clarify the metrics used here.The $65 billion figure refers to the annualized revenue run rate, which is extrapolated based on recent revenue trends and does not equate to Anthropic having already realized $65 billion in full-year accounting revenue.However, even accounting for this distinction, maintaining such a growth rate on such a large revenue base remains rare.
Growth is no longer driven solely by the Claude chatbot. As early as 2025, enterprise and commercial clients contributed approximately 80% of revenue, with the company already serving over 300,000 business and enterprise customers. Claude Code has rapidly become one of its flagship products. Over the past year, AI programming has evolved from assisting with code generation to autonomous agents capable of handling complex development tasks, allowing Anthropic to establish strong product recognition in this market.
Within this business model, there is a critical shift for investors.The monetization logic for AI is shifting from whether users are willing to pay $20 per month to how much enterprises are willing to pay for work completed by AI. The total addressable market for the latter is significantly larger.
If Claude continues to integrate into software development, enterprise workflows, and commercial systems like Salesforce, Anthropic's future revenue growth will become increasingly tied to actual enterprise AI usage. The recent expansion of collaboration between Salesforce and Anthropic, including the launch of Claudeforce, epitomizes this trend.
Behind the trillion-dollar valuation, what is the market really betting on?
Hypergrowth leads to sky-high valuations.Such pricing implies that investors are not just buying into Anthropic's current earnings, but are also pricing in its performance for 2027 and even 2028. Based on a $2 trillion valuation, Anthropic's valuation is approximately......31 times its current annualized revenue run rate of $65 billion.。
Investors are also focusing on longer-term performance.According to an August Reuters report, Anthropic internally projects that its 2028 revenue could reach $190 billion to $200 billion, implying a valuation roughly 10 times its 2028 revenue.Insiders stated that investment banks and investors have begun valuing companies using future revenue multiples, with high-growth, high-valuation firms like Palantir, Cloudflare, and SpaceX serving as benchmarks.
Anthropic's IPO will be a fascinating market博弈 (game of strategy). On one side, there is rare revenue growth speed in public markets and extreme scarcity at the AI model layer. On the other, there is an absolute valuation approaching $1 trillion or even $2 trillion, alongside massive ongoing investments in computing power.The market is essentially betting that Anthropic can achieve rapid growth to justify its current staggering valuation.
In a deal revealed only in late August, Anthropic plans to pay Nscale approximately $45 billion over the next six years to lease AI computing power. The company has previously signed large-scale compute resource agreements with Amazon, Google, and several chip and cloud computing firms. As AI demand intensifies, Anthropic will need to procure more GPUs, servers, electricity, and data center resources.
After the IPO, the core issue the market needs to assess is whether its revenue growth can consistently outpace the growth in compute costs. This will directly determine Anthropic's ultimate gross margin and free cash flow, and is key to whether its $2 trillion valuation can hold.
Once the S-1 is released, these are the figures worth watching closely.
For current investors, many key data points have not yet been fully disclosed.The next critical milestone is the S-1 filing, at which point at least four key items need to be verified.
First, actual revenue and growth rate.Currently, the market relies heavily on annualized run-rate revenue. After the prospectus is published, we will be able to see quarterly revenue, growth rates, and contributions from different business segments with greater accuracy for the first time.
Second, gross margin and compute costs.How much Anthropic spends to generate one dollar of revenue will determine whether it ultimately resembles a high-margin software company or a highly capital-intensive AI infrastructure company.
Third, customer structure.How much revenue is contributed by Claude Code, API, and enterprise subscriptions respectively, the level of concentration among major clients, and the proportion of sales through cloud platforms like AWS—these figures will directly impact the valuation multiples assigned by the market.
Fourth, the IPO price.Anthropic's revenue run rate has grown from approximately $9 billion at the end of 2025 to over $65 billion currently. If this growth trajectory can be sustained, today's seemingly exorbitant valuation could quickly be justified by earnings growth. However, once the growth rate significantly decelerates, a $2 trillion valuation could become a heavy burden.
Given the current pace of progress, this wait won't last long. At that point, the market will have its first opportunity to answer:How much is Claude's rapid growth actually worth?
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments (3)
to post a comment
36
40