"AI Bottleneck Trade" Ignites Upstream Sector—Who’s Raking in the Profits?
Value Partners AI Watch | The Tug-of-War Between Macro Tightening and Billion-Dollar Orders: How to Reassess AI in the High-Interest-Rate Era?
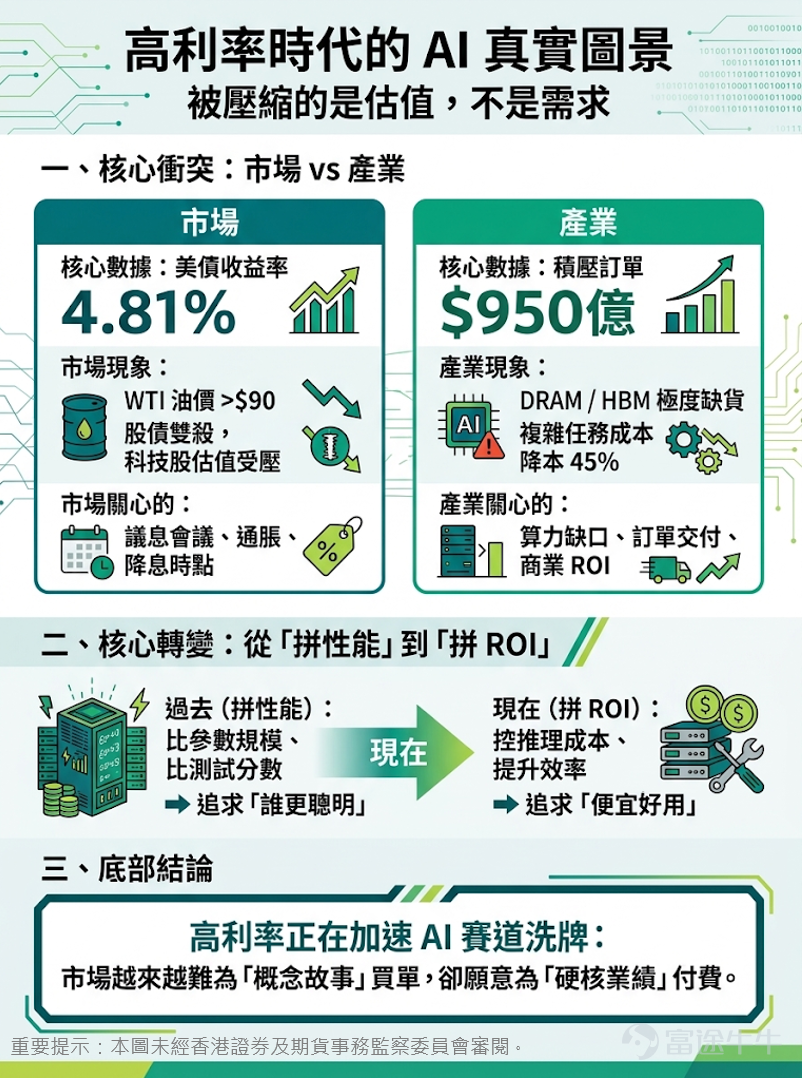
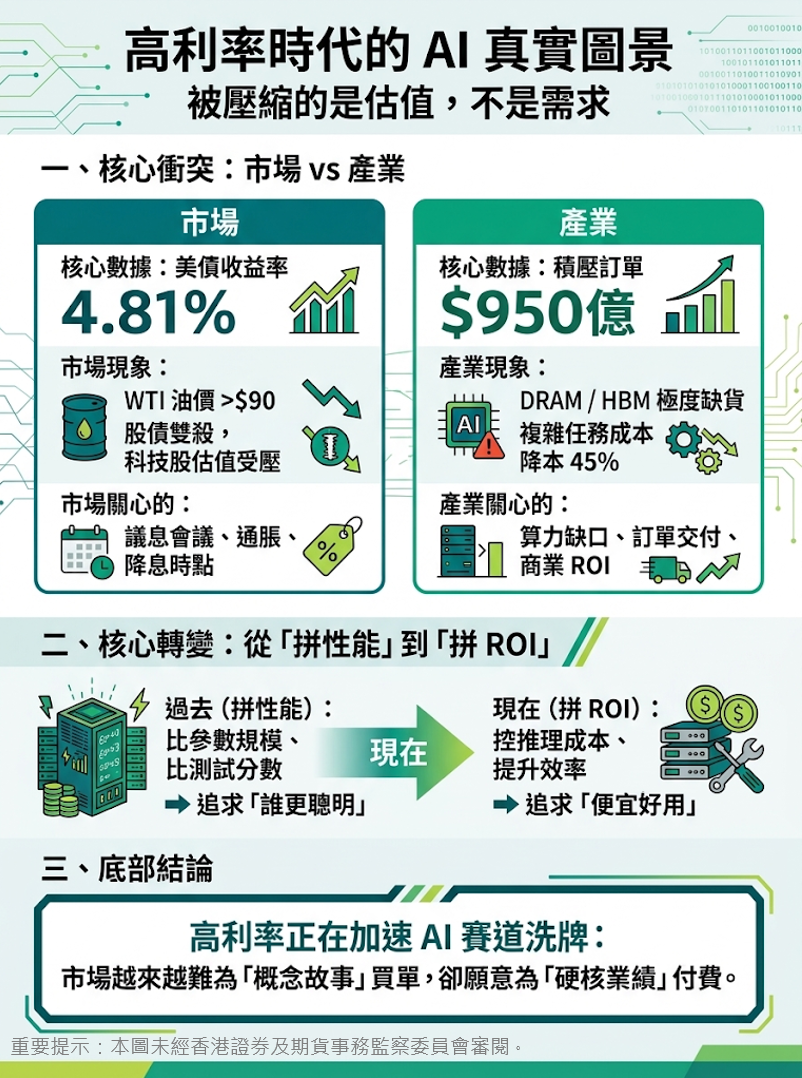
As we step into September, global markets have once again entered "risk pricing" mode. Driven by escalating tensions between the US and Iran,oil prices have returned above $90, market concerns aboutresurgent inflationandand persistently high interest rateshave rapidly intensified, with the yield on the US 10-year Treasury note climbing to4.81%nearby levels, hitting a recent high. Affected by this, the Dow Jones $Dow Jones Industrial Average (.DJI.US)$ 、Nasdaq $Nasdaq Composite Index (.IXIC.US)$ 、and the S&P 500 Index $S&P 500 Index (.SPX.US)$ Gold prices fell broadly $XAU/USD (XAUUSD.CFD)$ 、Bitcoin $Bitcoin (BTC.CC)$ Other assets also weakened in tandem, with the market once again experiencing a simultaneous sell-off in both equities and bonds.
Historical experience suggests that such a market environment is often unfavorable for technology growth stocks. As risk-free rates continue to rise, investors reassess the value of future cash flows, and sectors whose valuations are primarily built on expectations of future growth are usually the first to be impacted. Therefore, as US Treasury yields approach the 5% threshold again, many investors have begun discussing a key question:Will high interest rates bring an end to this round of the AI rally?
However, shifting focus from the secondary market to the industrial sector reveals a completely different picture. Just as the market was lowering valuations for growth stocks due to rising interest rates, the AI supply chain saw a series of major developments over the past few days. Dell's latest conference call indicated that AI order demand remains robust, with the focus of industry discussions not on insufficient demand but on tight DRAM supply; Anthropic released Claude 3.5 (noted as Fable 5.1 in source, likely referring to a model update), emphasizing reduced costs and improved efficiency for complex tasks; Google is set to launch Gemini 1.5 (noted as 3.8 in source, likely a typo for current models), intensifying the next round of model competition; and discussions surrounding HBM, advanced packaging, and the expansion of computing infrastructure are also heating up.
This suggests that the market may currently be facing a significant misjudgment. Many believe that high interest rates are broadly dampening AI, but recent signals from the supply chain seem to be telling the market:It is AI valuations that are being compressed, not AI demand.
1. While the market worries about interest rates, the supply chain is concerned about shortages.
If one looks solely at stock price performance, it is easy to conclude that the AI boom is cooling down. After all, in a high-interest-rate environment, both the semiconductor index and the software sector have seen significant corrections as capital flees valuation-sensitive assets. With the yield on the US 10-year Treasury note approaching 5%, investors can secure higher returns from low-risk assets, meaning growth stocks naturally face stricter pricing standards.
However, developments within the supply chain do not fully align with this sentiment.
One of the most closely watched industry news items recently comes from the server sector. During its latest conference call, a global server leader disclosed that its backlog of AI server orders approached $95 billion, while also raising its full-year performance guidance. More noteworthy than the order figures themselves was management's description of the current industry landscape. When addressing supply chain questions, they repeatedly emphasized that the biggest bottleneck is not demand, but DRAM supply—the phrase "what we are short of is DRAM, DRAM, DRAM" quickly became a hot topic in the market.
Insufficient demand and insufficient supply send completely different signals. Insufficient demand suggests the industry may be entering a downturn, whereas insufficient supply often indicates that demand is growing faster than supply can expand. From HBM to DRAM, and from advanced packaging to data center construction, multiple segments of the supply chain have been sending similar signals recently. Observing these phenomena together reveals a fairly consistent message from the entire supply chain: while the market worries about interest rates, companies remain focused on demand.
2. The focus of AI competition is shifting from model capabilities to commercial value.
If infrastructure expansion reflects the intensity of demand, then recent moves by model companies reveal another important shift in the AI industry.
Over the past two years, core competition in the AI industry has revolved around model capabilities. Larger parameter sizes, stronger reasoning abilities, and better benchmark scores have become almost the sole criteria for evaluating model value. At that time, the most discussed question in the industry was "who is smarter," with everyone chasing technical breakthroughs.
However, since entering 2026, this competitive logic has been quietly changing. When Anthropic launched Fable 5.1, the market's primary focus was not on model parameters, but on the up to 45% reduction in costs for complex tasks. Similarly, Google's upcoming release of Gemini 3.8 places emphasis on efficiency improvements and optimization of application capabilities.
This actually reveals an important signal:The AI industry is shifting its focus from raw performance to return on investment (ROI).
In the past, corporate procurement of AI services resembled a bet on future technology; today, companies are increasingly willing to pay because AI has demonstrated its ability to reduce costs and improve efficiency in real-world business operations. When clients start discussing ROI, it signals that the technology has moved from the lab to practical applications. The rise in interest rates has actually made the market more rational; capital is no longer willing to pay infinite premiums for pure concepts, but is instead focusing on who can create tangible value.
3. High interest rates are repricing AI, but it is not demand that is being repriced.
Putting these two phenomena together reveals that the AI industry is currently undergoing a significant turning point.
On one hand, the market is indeed re-evaluating the valuations of growth assets. Rising yields imply higher discount rates, which naturally place greater pressure on conceptual assets lacking profitability or order book support. On the other hand, the supply chain tells a completely different story: server orders continue to grow, supply and demand for storage products remain tight, and corporate clients are continuously testing new application scenarios. This indicates that AI demand itself has not disappeared with rising interest rates, which constitutes the biggest divergence in the market recently.
The market trades on interest rates, while the industry trades on demand.
The market is concerned with this week's non-farm payroll data, the next FOMC meeting, and inflation trends over the coming months, whereas the industrial chain is focused on whether computing power is sufficient, whether orders can be delivered, and whether corporate clients are willing to continue purchasing. In the short term, high interest rates do suppress market risk appetite; however, from an industrial perspective, the true criterion for companies deciding whether to continue investing in AI is return on investment. If AI capabilities continue to create value, corporate investment will not cease entirely due to rising interest rates.
Therefore, the greatest impact of high interest rates on AI is likely not to end the industry's growth logic, but to accelerate internal consolidation. Concepts lacking support from viable business models may face sustained pressure, while segments with genuine demand, infrastructure attributes, and commercial implementation capabilities have the opportunity to prove their value during this adjustment period.
Conclusion: The most important change in AI is not a technological breakthrough, but the realization of demand.
The most significant change brought about by US Treasury yields surging to 4.8% may not be the falsification of the AI investment thesis, but rather the repricing of the AI sector.
In a high-interest-rate environment, the market is increasingly unwilling to pay for narratives and instead demands tangible performance; it is becoming harder to accept concepts without revenue support, while business models that can deliver on demand are gaining recognition. High interest rates are accelerating divergence within the AI sector, and the common signal emerging from the industry chain recently is:
AI demand may be stronger than the market imagines, and the industry is shifting from "storytelling" to "delivering on promises."
Source: Compiled from public market data including the U.S. Department of the Treasury, Trading Economics, Futu News, Cailianshe, Reuters, and Bloomberg.
Disclaimer
· The above content is provided for reference purposes only and does not constitute, nor should it be construed as, an offer, solicitation, or recommendation to buy or sell any securities, investment products, or funds. This content is intended solely for viewing by persons in any jurisdiction where the distribution or provision of such content is lawful. By accessing this content, you represent and warrant that the laws and regulations applicable in your jurisdiction permit you to access such content.
· Investing involves risk. Past performance is not indicative of future results. The price of fund units/shares may rise or fall, and historical fund performance does not guarantee future returns. Investors should refer to the relevant fund prospectus for details and risk factors. Investors may not recover their full principal investment. The value of investments and any income derived therefrom (if any) may be volatile and subject to significant fluctuations over short periods.
· The data and information used to prepare the above content were obtained by Value Partners Asset Management Hong Kong Limited ('Value Partners') from sources believed to be reliable. However, no representation or warranty is made regarding the accuracy or completeness of data sourced from third parties. Any forecasts or other forward-looking statements concerning future events or performance of countries, markets, or companies are not necessarily indicative and may differ materially from actual events or outcomes. Value Partners assumes no liability for any losses incurred by any person acting on the data contained herein.
· No person may reproduce or use the above content—including but not limited to text, images, audio, and video—for any public or commercial purpose without the prior permission of Value Partners. Any modification or use of the above content may infringe upon copyrights and/or intellectual property rights held by Value Partners (where applicable).
· Publisher: Value Partners Asset Management Hong Kong Limited. This content has not been reviewed by the Securities and Futures Commission.
$Dow Jones Industrial Average (.DJI.US)$ $Nasdaq Composite Index (.IXIC.US)$ $S&P 500 Index (.SPX.US)$ $Hang Seng Index (800000.HK)$ $Hang Seng TECH Index (800700.HK)$ $Hang Seng China Enterprises Index (800100.HK)$ $NASDAQ 100 Index (.NDX.US)$ $Russell 2000 Index (.RUT.US)$ $HKEX Tech 100 Index (800666.HK)$ $PHLX Semiconductor Index (.SOX.US)$ $Ethereum (ETH.CC)$ $U.S. 1-Year Treasury Bills Yield (US12M.BD)$ $U.S. 10-Year Treasury Notes Yield (US10Y.BD)$ $U.S. 30-Year Treasury Bonds Yield (US30Y.BD)$ $FTSE Singapore Straits Time Index (.STI.SG)$ $Nikkei 225 (.N225.JP)$ $VIX (LIST91327.US)$ $CBOE Volatility S&P 500 Index (.VIX.US)$
Content Disclosure: Personal opinion
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments
to post a comment
5