Gold prices have climbed above $4,600. Is the metals bull market back?
Gold price trends amid US debt and fiscal deficits: The allocation advantage of gold mining stocks
Market sentiment in August was volatile. According to Bloomberg data, as of August 24, 2026, the three major US stock indices ( $Nasdaq Composite Index (.IXIC.US)$ 、 $S&P 500 Index (.SPX.US)$and $Dow Jones Industrial Average (.DJI.US)$ ) showed relatively stable overall performance; Hong Kong stocks were weighed down by traditional tech and internet giants, $Hang Seng Index (800000.HK)$ and $Hang Seng TECH Index (800700.HK)$ with performance under pressure. Even though $HKEX Tech 100 Index (800666.HK)$ was driven by the biotechnology sector, sentiment was similarly affected by the correction in tech stocks. In this context, the biotechnology sector and gold-related assets performed notably well in August, with $XAU/USD (XAUUSD.CFD)$ showing particularly noteworthy trends.
In our previous article, we mentioned three core reasons for the recent rise in gold prices:Non-farm payroll data、Central banks around the world continue to increase their gold holdings, as well as the resurgence of the "Debasement Trade" (Debasement Trade). We also pointed out that gold mining stocks, due to "All-in Sustaining Cost」(All-in Sustaining Cost (AISC)) relatively fixed characteristics, possessingnatural leverage effect。
This time, we continue to explore gold price trends from a macro perspective, focusing on the market's recent high attention toUS long-term bond yieldsandthe US fiscal deficit issue, and their impact on gold.
The rise in long-term bond yields is driven by fiscal deficits and credit concerns
According to Bloomberg data, $U.S. 10-Year Treasury Notes Yield (US10Y.BD)$ remains close to the high level of 4.70%, $U.S. 30-Year Treasury Bonds Yield (US30Y.BD)$ It even touched a near 20-year high of over 5.3%. This rise in long-end interest rates is not driven solely by economic overheating or inflation expectations, but rather bya significant increase in the term premium.。
The core reason lies in the U.S. fiscal situation:
– Federal debt has exceeded $40 trillion.
– Interest expenses reached approximately $1.4 trillion over the past 12 months, becoming a heavy burden.
– The deficit remains persistently high, with the single-month deficit in July reaching $432 billion, and the cumulative deficit for this fiscal year already surpassing the full-year level of the previous year.
– Foreign official buyers' willingness to hold positions has declined, with buyers relying more on price-sensitive private capital that demands higher risk compensation.
(Source: Official data from the U.S. Department of the Treasury and related market reports, as of August 19, 2026)
In mid-August, the U.S. Treasury announced it would at least double the size of its liquidity support repurchase agreements for 10–30 year bonds in an attempt to suppress long-end interest rates. While this initially caused yields to fall, the U.S. dollar to weaken, and gold prices to rise, the market generally views this as merely treating the symptoms without addressing the root problem of persistent deficits and expanding debt. Some analysts even interpret it as "stabilizing the bond market at the expense of the U.S. dollar."
Impact on Gold: Structural support exists, but short-term upside is limited.
Under traditional logic, rising long-term bond yields increase the opportunity cost of holding gold, which is bearish for gold prices. However, when the primary driver of rising rates isconcerns over fiscal creditworthiness,the logic shifts:
– The market begins to question the absolute status of U.S. Treasuries as "risk-free assets."
– Allocation demand rises for gold as an alternative credit asset with no counterparty risk and limited supply.
– This is an extension of the "devaluation trade"—capital rotating from sovereign debt into physical or hard assets.
Therefore, the current rise in long-term bond yields actually provides structural support for gold. From a medium-term perspective, as long as the supply-demand imbalance in U.S. Treasuries and fiscal sustainability issues are not significantly alleviated, gold still has room to move higher.
However, there is relatively limited room for further sharp surges in the short term:
– Gold prices have rebounded significantly from their lows, with some bullish factors already priced in.
– Real interest rates remain at relatively high levels (10-year TIPS yields around 2.3–2.4%).
- The impact of the Treasury's buyback intervention was short-lived; subsequent developments, including the Jackson Hole symposium and inflation data, warrant close monitoring.
- Should credible signals of fiscal consolidation emerge, or should real interest rates rise further, short-term volatility could intensify.

(Source: Bloomberg, as of 2026/08/24)
Bloomberg data indicates that the widening spread between long- and short-term US Treasury yields has been a key driver behind the recent rebound in gold prices. However, from an ultra-short-term perspective, the spread has recently shown signs of narrowing, reflecting relatively resilient short-end rates and volatility at the long end amid discussions on fiscal deficits. In this context, the US Dollar Index may have room for a rebound, thereby limiting the extent of gold's further short-term upside.
Overall, we maintain our view that gold retains allocation value over the medium term, but the rhythm is more suited to medium-term positioning rather than expecting a sharp, one-way surge in the short term.
Natural Leverage vs. Traditional Leveraged Instruments: Differences in Medium-Term Positioning
As mentioned previously, gold mining stocks feature All-In Sustaining Costs (AISC). Simply put, since mining costs are relatively fixed, any increase in gold prices above these costs translates almost entirely into profit, creating 'natural leverage.' Historically, gold mining stock indices have often recorded gains far exceeding those of gold prices themselves during gold price upcycles.
This is the core appeal of the E Fund (Hong Kong) Solactive Global Gold Miners Select Index ETF (2824). This ETF tracks leading global gold miners, allowing investors to hold a basket of gold mining stocks with natural leverage characteristics.
This ETF isthe only product among gold mining thematic ETFs listed on the Hong Kong Stock Exchange that allocates to both Hong Kong-listed and US-listed gold mining constituents。
(As of 2026/08/24, E Fund Gold Miners is currently the only ETF globally that includes gold mining stocks from both the Hong Kong and US markets; the accuracy of this statement may change if other similar products are listed; this statement excludes unlisted funds and private equity funds; source: Bloomberg)
Compared to traditional leveraged gold instruments (such as 2x or 3x gold futures ETFs or leveraged ETFs), natural leverage offers distinct advantages:
– No daily reset decay: Traditional leveraged products are prone to volatility decay due to daily rebalancing, making them unsuitable for medium- to long-term holding in volatile markets.
– No expiration or rollover risk: Futures-based instruments require continuous rollovers, resulting in higher costs and basis risk.
– Closely aligned with corporate earnings: Gold mining stocks reflect actual changes in corporate profits, rather than serving as pure price leverage.
– More suitable for medium-term positioning: In an environment where the medium-term outlook for gold prices remains positive, natural leverage can amplify returns while avoiding the structural decay associated with derivative instruments.
Chart: Historical Performance of the Global Gold Miners Select Index
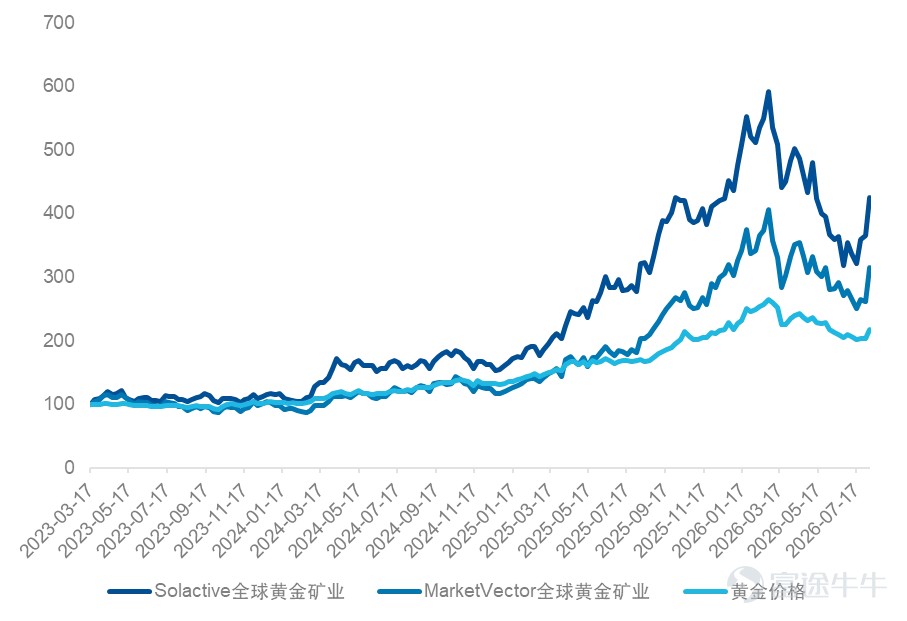
(Source: Bloomberg, USD-denominated, data from March 17, 2023 (base date) to August 7, 2026)
(The above is solely an objective presentation of the historical performance of the underlying index. Past index performance does not predict future fund returns and should not be construed as investment advice. Investors are advised to pay attention to the risks associated with index volatility. Actual fund returns may differ from index performance due to management fees, tracking error, and other factors. Please take note.)
*Note: The volatility of the Global Gold Miners Select Index is higher than that of spot gold. When gold prices decline, the index may experience more significant drawdowns.
Summary
Rising yields on long-term US Treasuries and the US fiscal deficit issue bring short-term volatility, but provide medium-term support for gold as a credit hedge. $Gold Futures (DEC6) (GCmain.US)$ The medium-term trend of gold prices remains worth monitoring, but there is limited room for another sharp surge in the short term. It is more suitable to position with a medium-term perspective.
In terms of instrument selection, $EFUND GOLD MI ETF (02824.HK)$ it offers natural leverage advantages through AISC (All-In Sustaining Costs), making it more suitable for medium-term holding than traditional leveraged gold derivatives. It avoids daily reset and expiration risks. Investors can use it as an aggressive tool in their gold allocation, depending on their risk tolerance.
Important Notice
This material is issued by E Fund Asset Management (Hong Kong) Company Limited. This material is for reference only and does not constitute an offer or recommendation to invest in fund units. This material is for display purposes only and must not be shown to any person in any jurisdiction where such display would be unlawful. Investing involves risks, and you may lose a substantial portion of your principal. Prior to investing, investors should carefully read the relevant investment risks described in the offering documents (including the 'Risk Factors' section) of the fund. This material has not been reviewed by the Securities and Futures Commission of Hong Kong.
iShares (Hong Kong) Solactive Global Gold Mining Select Index ETF (the “Sub-Fund”) is a sub-fund of iShares ETF Trust. The iShares ETF Trust is an umbrella unit trust established under Hong Kong law. The Sub-Fund is a passively managed ETF as defined under Chapter 8.6 of the Securities and Futures Commission (“SFC”) Code on Unit Trusts and Mutual Funds. Units of the Sub-Fund (“Units”) are traded on The Stock Exchange of Hong Kong Limited (“HKEX”) like stocks. The investment objective is to provide investment returns that closely track the performance of the Solactive Global Gold Mining Select Index (the “Index”) before fees and expenses.
Gold prices may fluctuate significantly due to changes in global supply and demand, geopolitical events, and currency movements. In addition, gold mining companies may face industry-specific risks, such as operational challenges, regulatory changes, and environmental concerns, all of which could affect their profitability regardless of gold price movements.
For detailed important notices and disclaimers regarding the above fund, please visit E Fund (Hong Kong)'s website:
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments
to post a comment
3
2