NVIDIA's revenue doubles, beating expectations; is the AI trade narrative making a comeback?
Wall Street Brief (August 27): U.S. stocks edged lower on Wednesday amid heavy wait-and-see sentiment; NVIDIA's earnings validated AI demand. Divergence emerged among big tech stocks, while gold fell below the $4,600 mark.
Summary: US stocks dipped slightly on Wednesday. The S&P 500 fell 0.02%, the Nasdaq dropped 0.08%, the Dow Jones declined 0.21%, and the Russell 2000 slipped 0.14%. Volatility across the four major indices was limited, with the Dow and small caps slightly weaker, while the Nasdaq remained relatively stable. The VIX fell to 15.21, down 1.55% for the day, indicating continued easing of short-term volatility concerns and persistent wait-and-see sentiment. US July PCE inflation came in higher than expected, dampening the appetite for chasing highs, while NVIDIA's post-market earnings further confirmed strong demand for AI computing power. In terms of sector performance, industrials and technology led the way, with AI memory and optical communications standing out, highlighting divergence within big tech. Healthcare, consumer discretionary, and social media sectors were weaker, and crypto-related stocks faced pressure. Among major asset classes, the 10-year US Treasury yield rose 0.54% to 4.664%; gold fell 1.39% to $4,594.115; crude oil rose 0.99% to $81.91; Bitcoin dropped 0.24% to $78,700.0; and the US Dollar Index gained 0.24% to 99.1458.

I. Major Events
1. US July PCE slightly exceeded expectations, curbing market enthusiasm for chasing highs
The US Bureau of Economic Analysis reported that the July PCE price index rose 3.7% year-over-year, surpassing market forecasts; core PCE increased 3.3% year-over-year, remaining well above the Federal Reserve's target, reigniting concerns about sticky inflation. Personal income and consumer spending continued to grow, indicating that demand has not cooled rapidly. Rising US Treasury yields and a stronger dollar put pressure on gold, while US stocks consolidated sideways. Investors were not in a rush to significantly reduce positions but were also reluctant to chase highs ahead of NVIDIA's earnings report.
2. NVIDIA releases post-market earnings, further validating AI computing demand
NVIDIA announced its second-quarter fiscal results after hours, with revenue of approximately $96.22 billion and adjusted earnings per share of $2.22, both beating market expectations. The company provided guidance for next quarter's revenue at around $108 billion, with data center business revenue reaching approximately $89 billion, underscoring robust demand for AI computing power. NVIDIA's earnings continue to support the AI hardware narrative, but market focus has shifted beyond just revenue growth rates. Gross margins, supply constraints, revenue from China, and returns on AI capital expenditure will all influence the valuation premium investors are willing to assign to semiconductor and cloud computing companies.
3. Meta settles child safety lawsuits for up to $18 billion
Meta has reached a settlement with multiple U.S. states, agreeing to pay up to approximately $18 billion and adjust safety mechanisms for teenagers on Facebook and Instagram. This resolution brings an end to a high-profile trial and allows Meta to avoid the uncertainty of potentially larger damages. While the penalty is substantial, the tail risk from litigation has decreased. For the internet platform industry, the more critical issue going forward is whether youth protection and content recommendation mechanisms will set new regulatory precedents.
II. Major Trends
On Wednesday, the four major indices closed nearly flat. The Dow Jones Industrial Average and the Russell 2000 were slightly weaker, while the Nasdaq saw a smaller decline. Following hotter-than-expected PCE inflation data, the market did not continue to chase higher prices, with capital largely adopting a wait-and-see approach.
Over the past two weeks, all four major indices have pulled back: QQQ fell 1.70%, IWM dropped 1.25%, SPY declined 0.83%, and DIA decreased by 0.46%, indicating more pronounced short-term pressure on tech and small-cap stocks. Over the three-month horizon, DIA rose 6.14%, IWM gained 3.14%, SPY increased 2.33%, while QQQ fell 2.48%, suggesting that the medium-term structure still favors the Dow and small caps over the Nasdaq.
Over the past two weeks, the market has not returned to huddling around big tech stocks. The MAGS index fell 0.21%, indicating that leading tech stocks have not yet regained their role as the primary drivers of gains. Meanwhile, the equal-weight S&P 500 ETF (RSP) rose 0.47% over two weeks, outperforming SPY's 0.83% decline, which suggests that market breadth remains healthy. In terms of style, SPYV rose 0.55% over two weeks while SPYG fell 2.02%, showing that value stocks continue to significantly outperform growth stocks.
III. Market Sentiment
The VIX dropped to 15.21, down 1.55% for the day, indicating that expectations for market volatility remain low. Although the indices retreated slightly, this did not trigger significant hedging demand. The CNN Fear & Greed Index dipped from 57 to 55, reflecting a slight pullback from the 'greed' zone. This shift aligns with the day's trading action: capital did not flee in panic, but investors were also not eager to chase higher prices.
Regarding CBOE Put/Call ratios, the total Put/Call ratio stood at 0.76, the index Put/Call ratio at 0.92, and the equity Put/Call ratio at 0.70. Demand for protection on the index side remains modest, and bullish sentiment for individual stocks has not noticeably heated up. Overall, the market appears to be maintaining a wait-and-see stance ahead of major earnings reports and inflation data.
4. Market Scan
1. Index ETFs
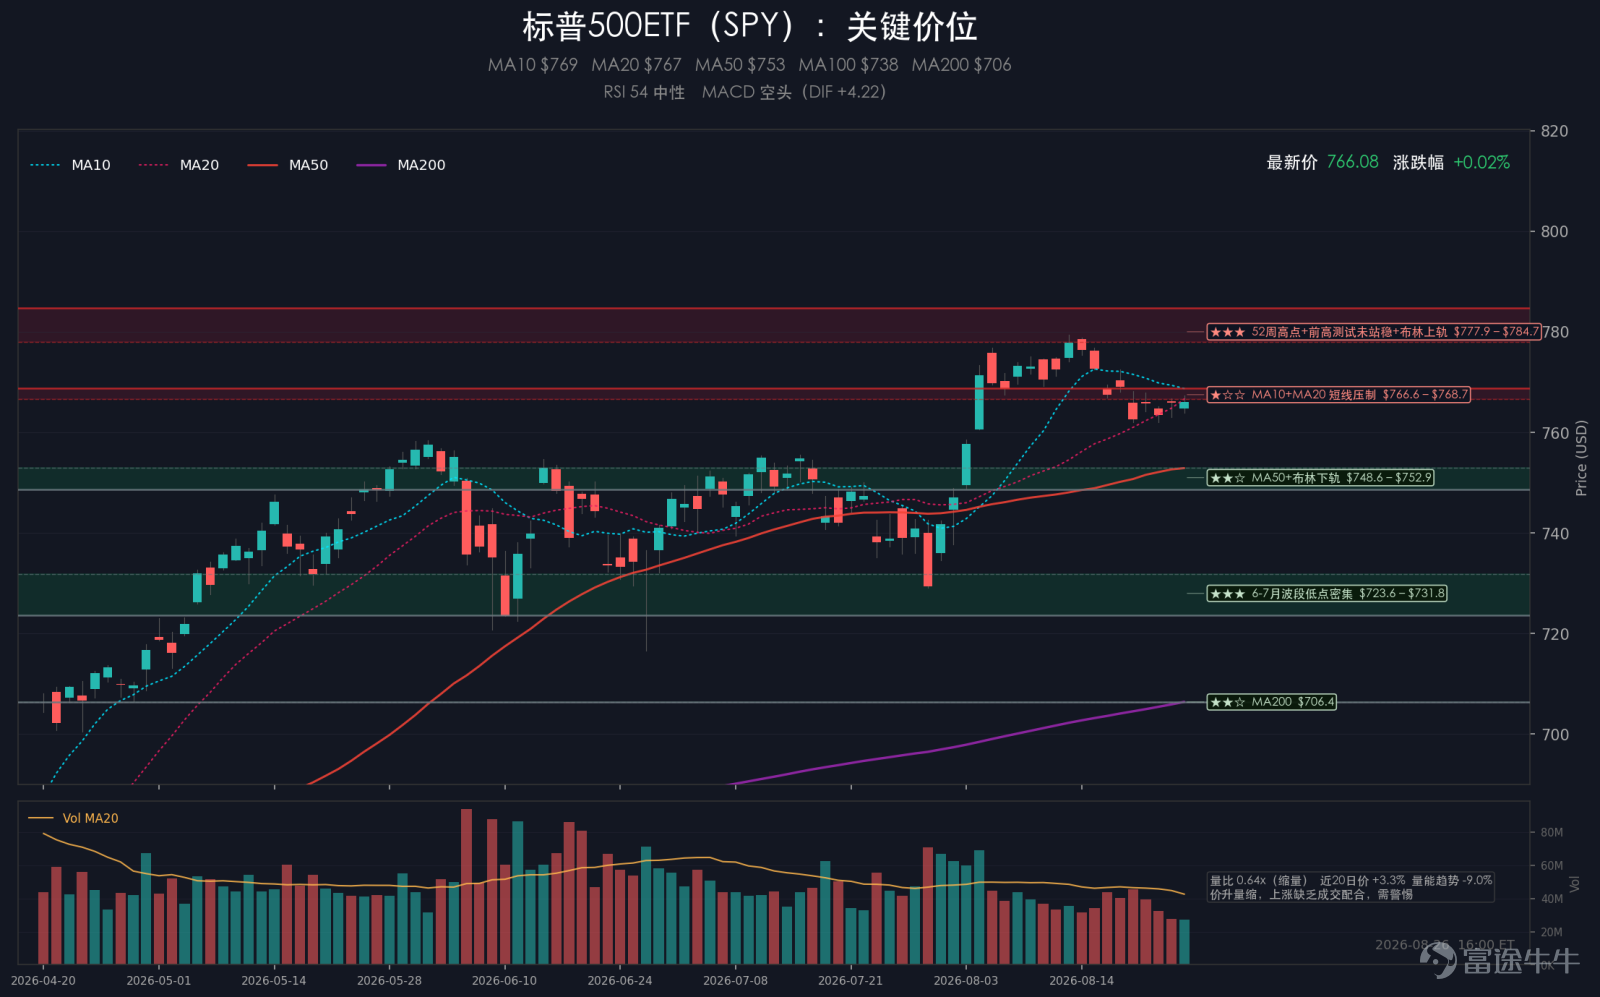
The Dow Jones ETF (DIA) fell 0.19%, the S&P 500 ETF (SPY) rose 0.02%, the Nasdaq 100 ETF (QQQ) gained 0.09%, and the Russell 2000 ETF (IWM) dropped 0.10%. The four major index ETFs overall closed nearly flat, with QQQ showing slight strength while DIA and IWM were weaker, indicating that investors remain reluctant to expand risk exposure following the hotter-than-expected PCE data.
International ETFs showed no clear directional strength. $Ishares Inc Msci United Kingdom Etf (New) (EWU.US)$ Fell 1.07%, $iShares MSCI South Korea ETF (EWY.US)$ fell 0.54%, $iShares MSCI Brazil ETF (EWZ.US)$ Down 0.45%, with most major country-specific ETFs underperforming core US equity indices.
2. Sector Performance
Among the 11 GICS sectors, $Industrial Select Sector SPDR Fund (XLI.US)$ Up 1.09%, $The Technology Select Sector SPDR® Fund (XLK.US)$ Up 0.61%, $Energy Select Sector SPDR Fund (XLE.US)$ Up 0.60%, $Utilities Select Sector SPDR Fund (XLU.US)$ Up 0.46%, ranking among the top performers; $The Health Care Select Sector SPDR® Fund (XLV.US)$ Down 1.00%, $Consumer Discretionary Select Sector SPDR Fund (XLY.US)$ Down 0.67%, $Real Estate Select Sector Spdr Fund (The) (XLRE.US)$ Down 0.60%, $The Communication Services Select Sector SPDR® Fund (XLC.US)$ Down 0.50%, acting as a drag on performance.
From the perspective of industry and thematic ETFs, $First Trust Exch Traded Fund 2 Nasdaq Cybersecurity Etf (CIBR.US)$ up 1.30%, $Global X Funds Global X U.S. Infrastructure Development Etf (PAVE.US)$ Up 1.04%, $SPDR S&P Oil & Gas Exploration & Production ETF (XOP.US)$ Rose 0.95%, $Ishares Trust U.S. Aerospace & Defense Etf (ITA.US)$ Rose 0.89%, $First Trust Cloud Computing ETF (SKYY.US)$ Rose 0.80%. $VanEck Gold Miners Equity ETF (GDX.US)$ Fell 2.94%, moving in tandem with the pullback in gold; $Global X Social Media ETF (SOCL.US)$ Fell 1.45%, $Proshares Online Retail Etf (ONLN.US)$ Fell 1.02%, indicating more pronounced pressure on platform and consumer supply chains.
Divergence persists within the AI supply chain. The optical communication/optical module basket rose an average of 2.88%, and the AI storage basket rose an average of 2.54%, but $VanEck Semiconductor ETF (SMH.US)$ remained largely flat, while NVIDIA declined during trading hours. Capital is favoring specific hardware segments rather than broadly chasing the semiconductor sector.
3. The Magnificent Seven Tech Stocks
The seven major tech ETFs (MAGS) fell 0.06%, overall nearing flat territory. Apple (AAPL) rose 1.15%, Meta rose 1.07%, and Microsoft rose 0.95%; NVIDIA (NVDA) fell 1.59%, Tesla (TSLA) fell 1.26%, Google (GOOG) fell 1.23%, and Netflix (NFLX) fell 0.94%.
Divergence continues among large-cap tech stocks. Apple, Meta, and Microsoft supported the weighted indices, while NVIDIA pulled back ahead of its after-hours earnings report. Tesla and Google also showed weakness, indicating that capital is not buying AI and platform tech stocks as a consolidated package.
4. Chinese ADRs
$KraneShares CSI China Internet ETF (KWEB.US)$ Down 0.49%, overall weak. $Futu Holdings Ltd (FUTU.US)$ Up 1.36%, with relatively strong performance, but most heavyweight Chinese internet stocks did not follow suit. $NetEase (NTES.US)$ Down 4.17%, $Bilibili (BILI.US)$ Down 2.53%, $JD.com (JD.US)$ Down 2.01%, serving as the main drag. There is significant divergence within Chinese concept stocks; capital prefers to select a few high-beta targets rather than systematically adding positions across the entire sector.
5. Cryptocurrencies
Bitcoin fell 0.24%, remaining in high-level consolidation. Cryptocurrency-related stocks saw even larger declines, $MARA Holdings (MARA.US)$ Down 5.16%, $Riot Platforms (RIOT.US)$Down 3.24%, $Coinbase (COIN.US)$ Down 2.87%, $Strategy (MSTR.US)$ Down 2.87%, $Circle (CRCL.US)$ Down 2.29%. Cryptocurrency-related stocks are more sensitive to risk appetite. While Bitcoin itself has seen limited volatility, mining companies, trading platforms, and stablecoin-related assets have already priced in the cooling of capital flows.
$S&P 500 Index (.SPX.US)$ $SPDR S&P 500 ETF (SPY.US)$ $Invesco Exchange Traded Fd Tr S&P 500 Equal Weight Etf (RSP.US)$ $NASDAQ 100 Index (.NDX.US)$ $Invesco QQQ Trust (QQQ.US)$ $Dow Jones Industrial Average (.DJI.US)$ $State Street® SPDR® Dow Jones Industrial Average® ETF Trust (DIA.US)$ $Russell 2000 Index (.RUT.US)$ $iShares Russell 2000 ETF (IWM.US)$ $Roundhill Magnificent Seven ETF (MAGS.US)$ $USD (USDindex.FX)$ $U.S. 10-Year Treasury Notes Yield (US10Y.BD)$ $iShares 20+ Year Treasury Bond ETF (TLT.US)$ $XAU/USD (XAUUSD.CFD)$ $SPDR Gold ETF (GLD.US)$ $CBOE Volatility S&P 500 Index (.VIX.US)$ $CME-Bitcoin RR Futures (SEP6) (BTCmain.US)$ $iShares Ethereum Trust ETF (ETHA.US)$ $NVIDIA (NVDA.US)$ $Tesla (TSLA.US)$ $Meta Platforms (META.US)$ $Amazon (AMZN.US)$ $Alphabet-C (GOOG.US)$ $Microsoft (MSFT.US)$ $Apple (AAPL.US)$
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments
to post a comment
8