Global institutional capital is accelerating its return to high-quality income-generating assets in the Asia-Pacific region—the Samsung Asia-Pacific High Dividend REIT (ex-New Zealand) ETF (3187 HK) captures this recovery opportunity
Amid current global macroeconomic volatility and diverging interest rate trajectories, international institutional investors are focusing on tangible real estate assets that offer "stable cash flows" and "inflation-hedging capabilities."
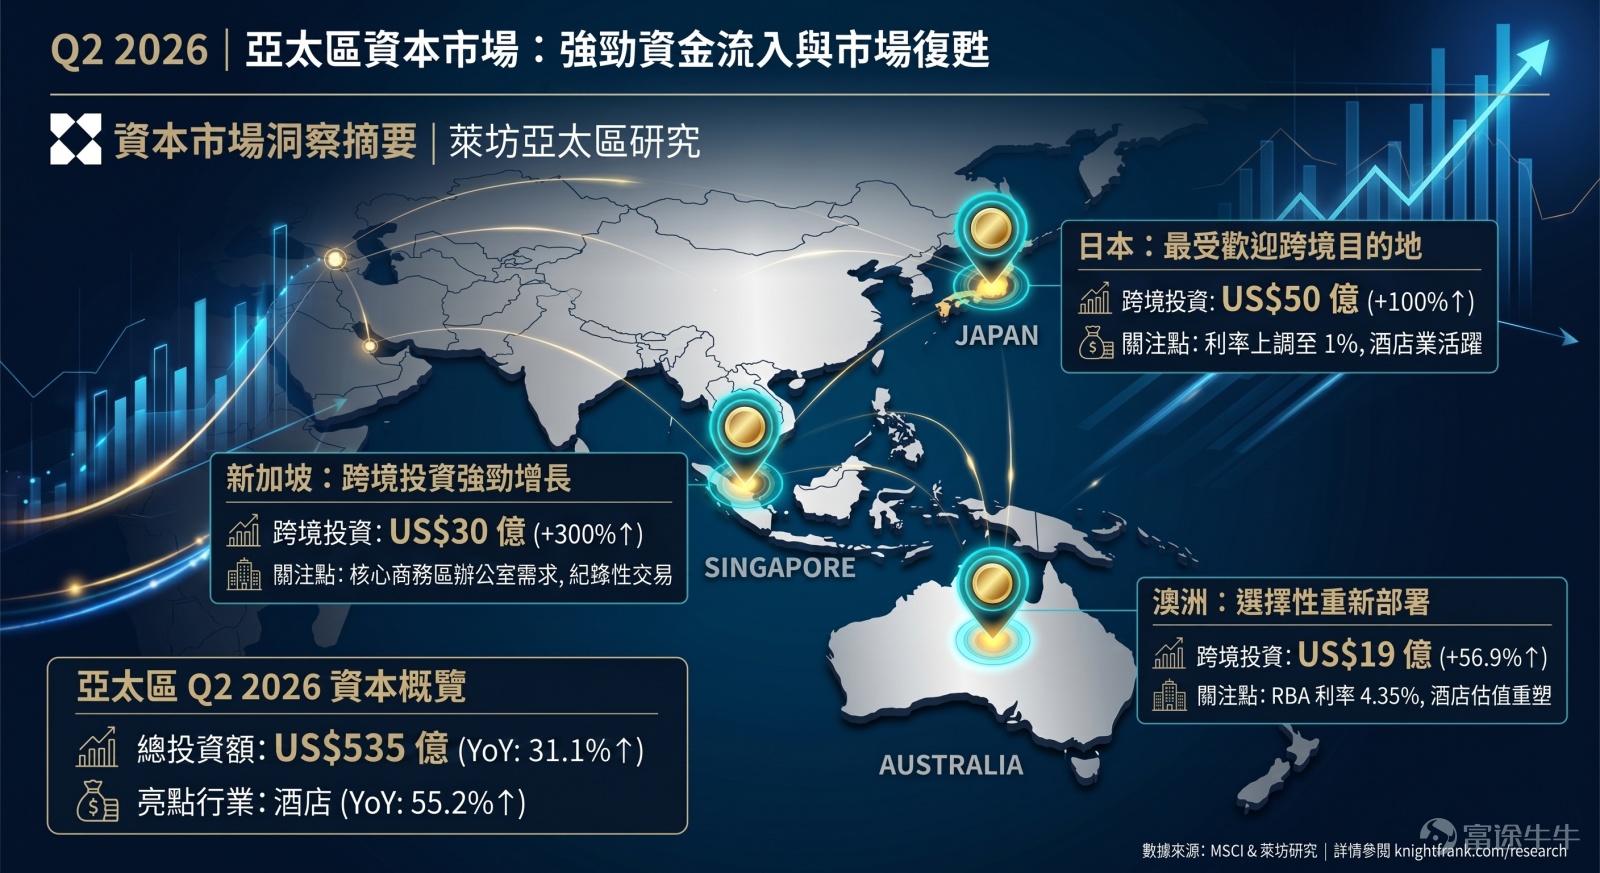
According to the "Asia Pacific Capital Markets Insight" report released by Knight Frank, a globally authoritative real estate advisory firm, in August, total commercial real estate investment in the Asia-Pacific region reached $53.5 billion in Q2, representing a significant year-on-year increase of 31.1% and exceeding the five-year Q2 average by 16.1%. The key driver was the strong return of cross-border capital. International investment flowing into the Asia-Pacific region in Q2 amounted to $12.5 billion, accounting for 23.4% of total investment, a substantial year-on-year surge of 156.8%. The data clearly demonstrates that international long-term capital is showing strong confidence and actively returning to core property markets in the Asia-Pacific region [1].
Three core markets lead the recovery, with fundamental highlights emerging across the board
The primary destinations for cross-border capital are concentrated in $Samsung S&P High Dividend APAC ex NZ REITs ETF (03187.HK)$ the three markets covered by core holdings—Japan, Singapore, and Australia.
Japan: Ample liquidity, top choice for foreign capital allocation Japan has become the most favored investment destination for multinational capital in the Asia-Pacific region, attracting as much as $5 billion in foreign inflows in Q2 2026, doubling the scale from the same period last year. The report notes that although the Bank of Japan raised interest rates to 1% in June, international funds still view Japan as a core allocation market, thanks to its vast market liquidity and scale advantages. This indicates that even amidst minor policy adjustments, the appeal of high-quality Japanese assets and their long-term investment value remain robust [1].
Singapore: Strong defensive attributes attract an influx of cross-border capital Cross-border investment in the Singapore market continued its strong momentum from Q1 in Q2, surpassing $3 billion, a more than threefold year-on-year surge. Notably, multinational capital accounted for a high proportion of 58.1% of local total transaction volume. Among these, prime properties in the core CBD area demonstrated strong defensive attributes and stable rental income capabilities. For instance, the landmark transaction where IOI Properties Group acquired Asia Square Tower 2 for $1.9 billion highlights the high demand among investors for defensive, stable-yield assets amid limited supply [1].
Australia: Valuation reset, precise positioning in high-quality assets Australia attracted $1.9 billion in cross-border capital in Q2, a year-on-year increase of 56.9%. According to Knight Frank's analysis, despite the Reserve Bank of Australia raising rates three times this year, this wave of capital inflow was not indiscriminate; rather, it involved precise positioning in assets whose valuations had been adjusted and whose income fundamentals remained resilient. The hotel sector emerged as a highlight, with cross-border investment surging nearly fivefold year-on-year to reach $674 million. This confirms that following the valuation reset, yields in the Australian market are highly attractive, and long-term fundamentals remain solid [1].

Why choose the Samsung Asia Pacific High Dividend REIT ETF (ex-New Zealand) (3187 HK)?
For retail investors, directly purchasing cross-border commercial buildings or logistics parks involves extremely high barriers to entry; whereas $Samsung S&P High Dividend APAC ex NZ REITs ETF (03187.HK)$ it provides investors with a convenient tool to gain one-click access to top-tier Asia-Pacific Real Estate Investment Trusts (REITs):
AdditionQuarterly dividend distributionspolicy, where underlying assets are supported by tangible leases and robust operating cash flows, making it an ideal income-generating "ballast" to weather market volatility and hedge against inflation.
1. One-click diversified allocation into high-quality cross-border properties: Closely tracks mature Asia-Pacific markets (such as Singapore, Australia, Japan, etc.), avoiding concentration risk in a single economy, while directly capturing top-tier commercial buildings, shopping malls, logistics warehouses, and hotel facilities.
2. Quarterly dividend distribution mechanism to build stable cash flow:AdditionQuarterly dividend distributionspolicy, where underlying assets are supported by tangible leases and robust operating cash flows, making it an ideal income-generating "ballast" to weather market volatility and hedge against inflation.
3. Align closely with the institutional "Flight to Quality" strategy: The Knight Frank report emphasizes that the current market environment will highly reward "high-quality assets with scale and pricing advantages" [1]. The 3187 HK tracking index screens for high-liquidity, high-yield, premium REITs in the Asia-Pacific region, aligning with institutional-grade investment logic.
Source:
[1] Knight Frank, "Asia Pacific Capital Markets Insight," Q2 2026 Report
[2] Samsung Asset Management (Hong Kong), as of August 26, 2026
Disclaimer and Important Notes
• Investment involves risks. Past performance is not indicative of future results. The price of funds may rise or fall, and investors may suffer all or substantial investment losses. Investors should not make any investment decisions based solely on this information.
• The Samsung Asia Pacific High Dividend Real Estate Investment Trust (Excluding New Zealand) ETF is a sub-fund of Samsung ETF Trust II. Its investment objective is to provide investment results that, before fees and expenses, closely correspond to the performance of the S&P High Yield Asia Pacific (Excluding New Zealand) Select Real Estate Investment Trust Index (the "Index").
• Key risk factors associated with the Samsung Asia Pacific High Dividend Real Estate Investment Trust (Excluding New Zealand) ETF include general investment risks; currency risks; concentration risks in the Asia-Pacific real estate market; risks related to investing in real estate funds (including real estate market risks, operational and management risks, interest rate risks, liquidity risks, regulatory risks, leverage risks, etc.); Asia-Pacific market risks; securities lending transaction risks; new index risks; multi-counter risks; other currency distribution risks; risks of distributions paid out of capital or effectively out of capital; passive investment risks; tracking error risks; trading risks; risks of trading differences; termination risks; and risks related to reliance on market makers and liquidity. Please note that the above list of investment risks is not exhaustive. Investors should carefully read the product prospectus, product key facts statement, and relevant sales documents before making any investment decisions to understand details including product features, risk factors, and distribution policies.
• The aforementioned fund has been authorized by the Securities and Futures Commission (the “SFC”) of Hong Kong. Such authorization does not imply official endorsement of the product. This information is for reference only and does not constitute an offer or solicitation to any person to buy or sell any product or adopt any investment strategy.
• The manager may, at its discretion, make cash distributions to unit holders from capital or total income (while charging all or part of the product’s fees and expenses to the product’s capital / paying them from the product’s capital), thereby increasing distributable income to fund distributions, effectively resulting in distributions being paid from capital.
• Paying distributions from capital or effectively from capital is equivalent to investors receiving a return of part of their original investment or withdrawing part of their original investment or capital gains attributable to that original investment. Any practice involving payment of distributions from the product’s capital or effectively from the product’s capital may result in an immediate reduction in the net asset value per unit.
• This document is prepared by Samsung Asset Management (Hong Kong) Limited (SAMHK) and has not been reviewed by the SFC or any other regulatory authority. Investors should determine whether any investment product or strategy is suitable for them based on their personal financial situation, investment experience, and objectives. If you have any questions regarding this information, you should seek professional advice as needed.
• Certain information contained herein has been compiled from third-party sources. SAMHK has made reasonable efforts to ensure the accuracy, completeness, and timeliness of such information and has taken measures to accurately reproduce it; however, SAMHK assumes no responsibility or liability for the accuracy of such information, its use, or reliance thereon. This content may contain forward-looking statements based on SAMHK’s opinions, expectations, and assumptions. SAMHK undertakes no obligation to update or revise any forward-looking statements, and actual results may differ materially from those anticipated in such statements. All copyright in the content of this material (including all data, images, code, text, logos, and designs) belongs to SAMHK. No part of this material may be reproduced or redistributed without SAMHK’s prior consent.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comments
to post a comment
1