Options Hub: Oil prices break $100, PPI beats expectations! How to position with options for tonight
Daily Options Outlook | NVIDIA earnings hit after the bell, with options market implying ±5.4% stock price volatility; July PCE data to be released at 20:30 tonight—will the Fed's policy path be repriced?
Today's Options Opportunity Outlook
On the macro front,$Invesco QQQ Trust (QQQ.US)$Down 0.15% in pre-market trading,$SPDR S&P 500 ETF (SPY.US)$Down 0.03% in pre-market trading. In the previous session, Iran and Oman made progress regarding safe navigation in the Strait of Hormuz, leading to a continuous decline in oil prices and a significant drop in US Treasury yields.
At 20:30 tonight, the July PCE, the second estimate of Q2 GDP, and durable goods orders will be released simultaneously.Market expectations suggest headline PCE will ease slightly from June's 3.7% to 3.6%. Core PCE is expected to rise by approximately +0.2% month-over-month, slightly higher than June's 0.13% increase; year-over-year, it is projected to rise by 3.20%, compared to June's 3.3%. Q2 GDP may see a slight upward revision from the initial estimate of 1.5%.This batch of data happens to be released just before Governor Warsh's speech at Jackson Hole on Friday, so even a modest deviation from expectations could quickly transmit to US Treasuries and tech stocks.
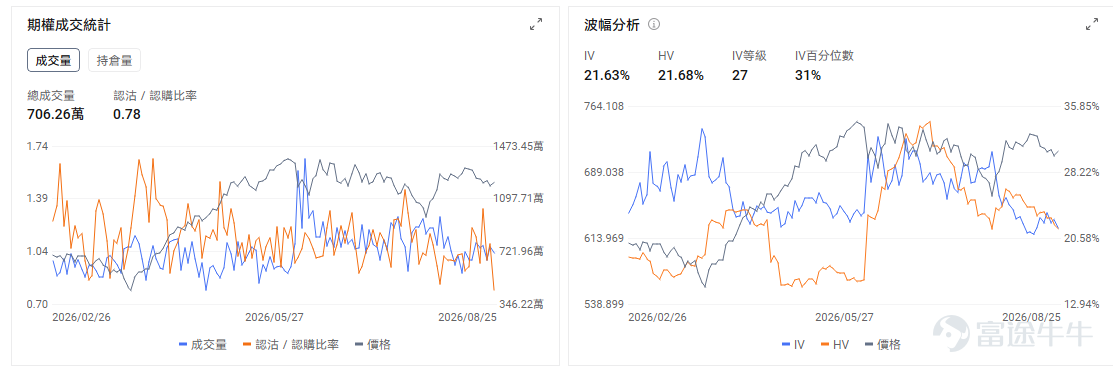
If core PCE comes in below expectations, the recent narrative of "cooling long-end rates" will be further validated, with QQQ and high-valuation tech stocks being the most direct beneficiaries. If PCE re-accelerates, the market may raise the probability of a September rate hike again, placing tech stocks under dual pressure from interest rates and earnings ahead of NVIDIA's report. Options market data shows the Put/Call volume ratio for QQQ dropped to 0.78 on the last trading day, with implied volatility (IV) reaching 21.63%.

At the individual stock level, $NVIDIA (NVDA.US)$ The company is scheduled to release its Q2 earnings after the bell on August 26 (ET). The stock saw a slight pre-market rebound after seven consecutive days of declines, rising 0.31% in pre-market trading. Market focus has shifted from simply whether earnings can "beat" estimates to whether AI infrastructure investment can maintain its high intensity, including demand for Blackwell/Rubin, cloud providers' capital expenditures, gross margins, and the scale and risks of NVIDIA's involvement in AI infrastructure financing.
The options market currently implies a post-earnings stock price move of approximately ±5.4%, which is among the lowest implied volatility levels for NVIDIA's earnings since 2021,and is significantly lower than the average actual post-earnings move of about 7.4%. Options market data shows the stock's Put/Call volume ratio has dropped to 0.39, with implied volatility at 44.22%.


$Salesforce (CRM.US)$ and $CrowdStrike (CRWD.US)$ Companies such as these are set to report earnings tonight, leading to a collective validation of software valuations. Options pricing also offers sufficient trading value:The market currently implies post-earnings moves of ±7% for CRM and ±7.5% for CRWD.For CRM, the key is whether AI products like Agentforce can truly drive order and revenue growth; for CRWD, the question is whether AI security demand is sufficient to support its valuation after the significant rally this year.
If both companies beat expectations simultaneously, it could trigger further valuation repair in the software/cybersecurity sectors, which have been under pressure this year. If AI-related revenue remains sluggish, it may reinforce the trade thesis that "AI benefits hardware but hurts software."
Recap of yesterday's options activity
Index Options
On August 25 (ET), trading volume in the US index options market declined, with a total of 4.78 million contracts traded. The Put/Call volume ratio fell to 0.97.
For the upcoming expiration date,$S&P 500 Index (.SPX.US)$ The options volume distribution shows the following characteristics: put option volume peaked at 7,670 points, while call option volume peaked at 7,700 points.
Single-Stock Options
$Advanced Micro Devices (AMD.US)$Closed up 4.91%, with 407,300 options contracts traded; the put/call volume ratio dropped to 0.72. Raymond James upgraded AMD to Strong Buy with a target price of $641, predicting it will surpass Intel by 2027.
$Palantir (PLTR.US)$Closed down 1.80%, with 361,700 options contracts traded; the put/call volume ratio dropped to 0.63. Palantir CEO Alex Karp sold 492,000 shares on August 20, worth $86.06 million.
Options Volume Rankings
Among the top 10 stocks by options volume,$Advanced Micro Devices (AMD.US)$had the highest put/call volume ratio, reaching 0.72.
Implied Volatility Leaderboard (underlying market cap > $1 billion and options volume > 100,000)
$Cipher Digital (CIFR.US)$Implied volatility was highest, reaching 99.97%, down 2.76% from the previous trading session. Morgan Stanley analysts believe Bitcoin miners like Cipher Digital are well-positioned to pivot to AI businesses, as their grid connectivity helps them bypass political resistance facing data centers.
$NuScale Power (SMR.US)$Implied volatility saw the largest increase, reaching 87.55%, up 9.36% from the previous trading session. NuScale Power is deploying nuclear-specific AI tools to enhance engineering efficiency, with initial tests showing an 80% reduction in information retrieval time.
Risk Warning
An option is a contract that grants the holder the right—but not the obligation—to buy or sell an underlying asset at a predetermined price on or before a specified date. Option prices are influenced by multiple factors, including the current price of the underlying asset, strike price, time to expiration, and implied volatility.
Implied volatility reflects the market’s expectation of future price fluctuations over a given period. It is derived by reverse-engineering the Black-Scholes option pricing model and is generally viewed as an indicator of market sentiment. When investors anticipate greater volatility, they may be willing to pay higher premiums for options to hedge risk, resulting in higher implied volatility.
Traders and investors use implied volatility to assess the attractiveness of option prices, identify potential mispricings, and manage risk exposure.
Disclaimer
This content does not constitute an offer, solicitation, recommendation, advice, opinion, or any guarantee regarding any securities, financial products, or instruments. The risk of loss in trading options can be substantial. In certain circumstances, your losses may exceed the initial margin deposit. Even if you place contingent orders such as 'stop-loss' or 'limit' orders, you may not be able to avoid losses. Market conditions may prevent the execution of such orders. You may be required to deposit additional margin on short notice. If you fail to meet such margin requirements within the stipulated time, your open positions may be liquidated. You remain fully liable for any resulting deficit in your account. Therefore, you should thoroughly research and understand options and carefully consider whether such trading is suitable for you based on your financial situation and investment objectives. If you trade options, you should be familiar with the procedures for exercising options and handling expiration, as well as your rights and obligations upon exercise or expiration. Options trading involves substantial risk and is not suitable for all investors. Investors should carefully read"Characteristics and Risks of Standardized Options"。
This content does not constitute an offer, solicitation, recommendation, advice, opinion, or any guarantee regarding any securities, financial products, or instruments. The risk of loss in trading options can be substantial. In certain circumstances, your losses may exceed the initial margin deposit. Even if you place contingent orders such as 'stop-loss' or 'limit' orders, you may not be able to avoid losses. Market conditions may prevent the execution of such orders. You may be required to deposit additional margin on short notice. If you fail to meet such margin requirements within the stipulated time, your open positions may be liquidated. You remain fully liable for any resulting deficit in your account. Therefore, you should thoroughly research and understand options and carefully consider whether such trading is suitable for you based on your financial situation and investment objectives. If you trade options, you should be familiar with the procedures for exercising options and handling expiration, as well as your rights and obligations upon exercise or expiration. Options trading involves substantial risk and is not suitable for all investors. Investors should carefully read"Characteristics and Risks of Standardized Options"。
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments
to post a comment
15
11