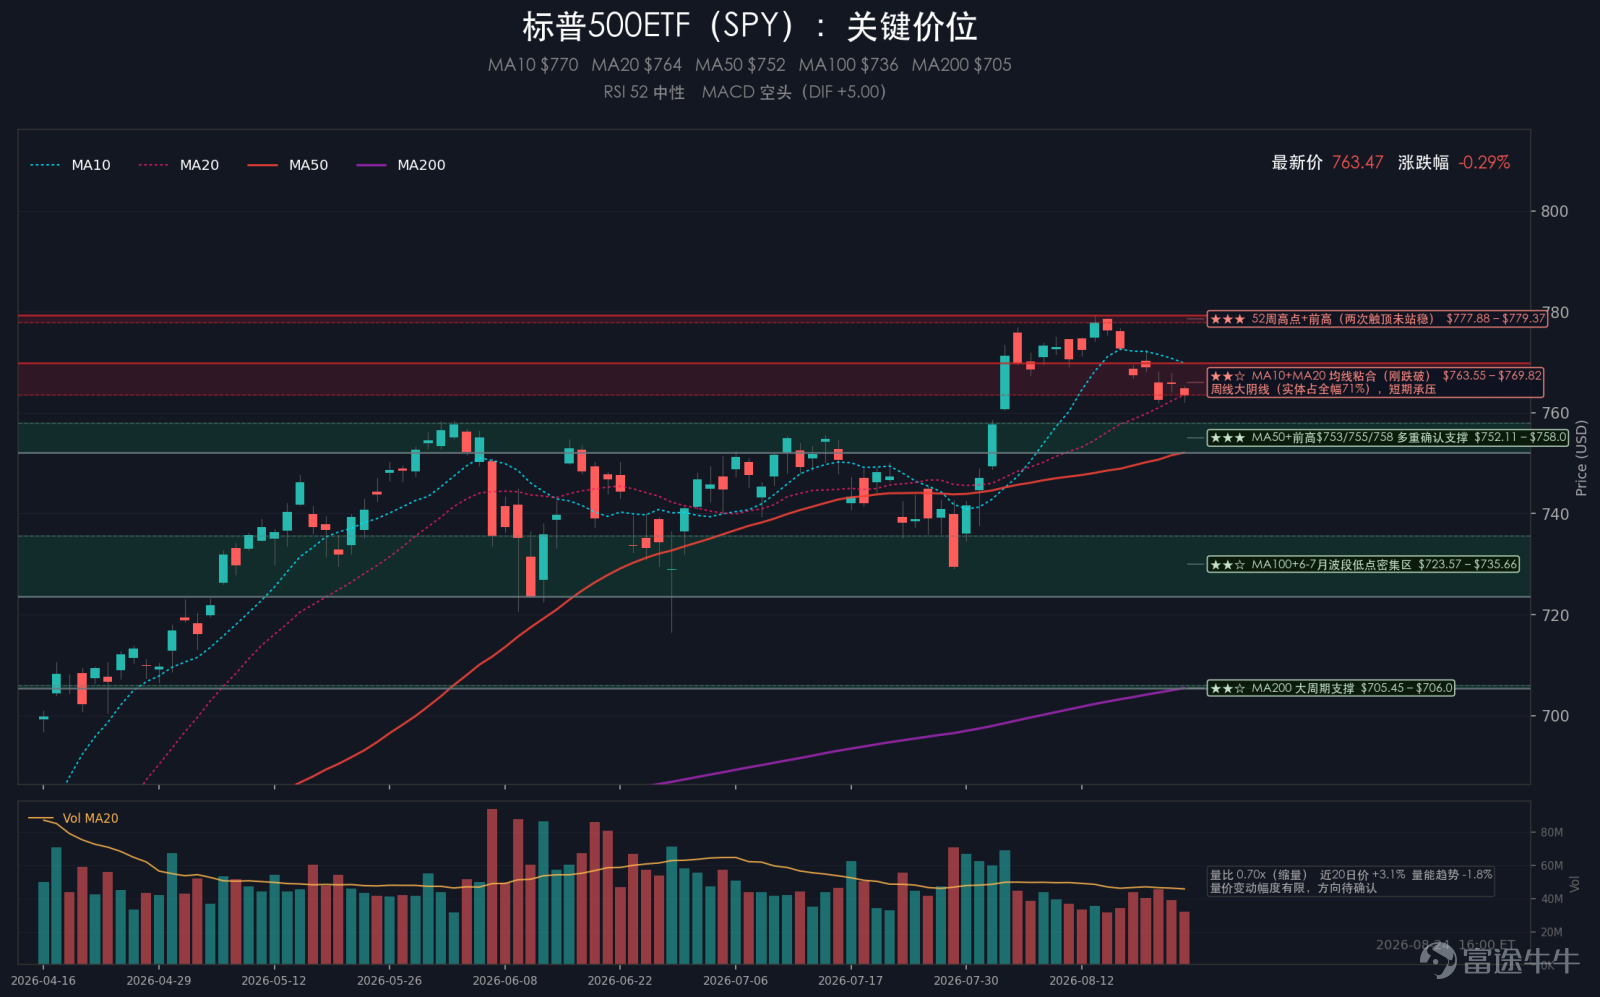
The Nasdaq pulled back while the Dow showed resilience, with consumer staples emerging as a safe hav
Wall Street Briefing (August 25): US stocks diverged on Monday, with the Dow Jones rising against the trend. AI hardware stocks saw a significant pullback, while gold and Bitcoin continued to climb. Amid a密集 period of major events, market hedging sentiment has marginally increased.
Summary: US stocks diverged on Monday. The S&P 500 fell 0.28%, the Nasdaq dropped 0.76%, the Dow Jones rose 0.26%, and the Russell 2000 declined 0.76%. The Dow Jones strengthened against the trend, while the Nasdaq and small-cap stocks faced pressure. The VIX rose to 15.85, up 4.76% for the day, indicating a marginal increase in market hedging sentiment, though absolute levels remain low. On one hand, the market traded on the possibility of the Treasury expanding long-term bond buybacks, causing the 10-year US Treasury yield to fall; on the other hand, it weighed down AI hardware and high-valuation tech stocks ahead of NVIDIA's earnings, the PCE data, and the Jackson Hole symposium. Market highlights focused on consumer staples, financials, and defensive sectors, while semiconductors, optical communication/modules, and AI storage saw notable pullbacks. In terms of major asset classes: the 10-year US Treasury yield was 4.704%, down 0.72%; gold was $4,652.50, up 1.07%; crude oil was $84.98, down 1.92%; Bitcoin was $78,740.00, up 1.47%; and the US Dollar Index was 98.9889, up 0.17%.

I. Major Events
1. The US Treasury may utilize the TGA to expand long-term US Treasury bond buybacks
Multiple media reports indicate that the US Treasury may deploy nearly $1 trillion from the Treasury General Account (TGA) to fund larger-scale long-term US Treasury bond buybacks. The Treasury had previously increased the scale of buybacks for 10- to 30-year US Treasuries to at least $4 billion per operation. The 10-year US Treasury yield fell 0.72%, temporarily easing pressure on long-end rates. Gold rose 1.07%, and the Dow Jones rose against the trend. However, technology and AI supply chain stocks remained suppressed by pre-earnings risks, and the decline in interest rates did not lead to a comprehensive repair in risk sentiment.
2. The US announces sanctions plan for "Operation Economic Outcast" against Iran
US Treasury Secretary Bessent announced "Operation Economic Outcast" targeting Iran, covering sectors such as digital assets, aviation, technology, gold, and shipping. He warned that countries and companies continuing to trade with Iran could face US sanctions. Following the announcement, oil prices did not continue to surge, with crude oil falling 1.92%. Energy stocks and oil & gas services faced pressure, inflation expectations eased somewhat, providing background support for the decline in US Treasury yields.
3. US-Canada trade talks collapse, tariff conflict escalates further
Following the breakdown of US-Canada trade negotiations, the US imposed a 50% tariff on approximately $20 billion worth of Canadian goods, prompting Canada to announce countermeasures. Trump also threatened to impose an additional 50% tariff on Canadian automobiles, auto parts, and steel starting January 2027. The escalation in tariffs has increased uncertainty regarding North American supply chains and inflation, putting pressure on the Canadian dollar and raising cost pressures across the automotive, steel, agricultural products, and housing materials sectors.
II. Major Trends
Over the past three months, the Dow Jones outperformed the Nasdaq, with returns of 5.84% versus -1.46%. Small-cap stocks (Russell 2000) also outperformed large-cap stocks (S&P 500) during the same period, returning 4.76% compared to 2.66%. The market leadership is shifting from tech giants toward value and cyclical sectors.
Market breadth is improving: The equal-weight S&P 500 ETF (RSP) rose 7.85% over three months, significantly outperforming the market-cap-weighted SPY's 2.66%. This rally is supported by a broader range of individual stocks rather than being driven solely by a few leaders.
The style rotation continues: Value ETFs rose 4.72% over three months, outperforming growth ETFs' 1.02%. In the past two weeks, growth stocks experienced a deeper correction (-2.76% vs. -0.62%), as capital flows favor the more defensive value sector.
The dominance of top stocks is marginally weakening: The Magnificent 7 weighted ETF fell 2.67% over two weeks, with momentum indicators turning negative. Combined with pre-earnings position reductions in chip stocks, the pricing power of tech giants is being diluted by broader sector rotation.
III. Market Sentiment
The VIX closed at 15.85, up 4.76% for the day, as index divergence and the tech pullback boosted demand for hedging. The CNN Fear & Greed Index stood at 55, unchanged from the previous reading, keeping overall sentiment in the neutral-to-optimistic zone. CBOE options data showed a total Put/Call ratio of 0.81, with index option Put/Call at 0.90 and equity option Put/Call at 0.78. The rise in VIX alongside higher Put/Call ratios indicates increased hedging ahead of NVIDIA's earnings, the PCE data release, and the Jackson Hole symposium. The stable Fear & Greed Index suggests this is not broad panic, but rather heightened defensiveness ahead of a cluster of key events.
IV. Market Scan
1. Index ETFs
Major index ETFs diverged on Monday. The S&P 500 ETF (SPY) fell 0.26%, the Nasdaq-100 ETF (QQQ) dropped 0.98%, the Dow Jones ETF (DIA) rose 0.20%, and the Russell 2000 ETF (IWM) declined 0.76%. DIA showed relative resilience, while QQQ and IWM were weaker, indicating capital outflows from growth and small-cap segments.
Country-specific ETFs saw limited overall volatility. $Ishares Inc Msci United Kingdom Etf (New) (EWU.US)$ Rose 0.33%, $iShares MSCI France ETF (EWQ.US)$ up 0.31%, $iShares MSCI Brazil ETF (EWZ.US)$ up 0.09%; $iShares MSCI South Korea ETF (EWY.US)$ down 2.64%, $iShares MSCI Japan ETF (EWJ.US)$ down 0.86%, $Ishares Msci Australia Index Fund (EWA.US)$ down 0.70%. The Korean tech supply chain is under the most significant pressure.
2. Sector Performance
Among primary sectors, $Consumer Staples Select Sector SPDR Fund (XLP.US)$ up 1.70%, $Financial Select Sector SPDR Fund (XLF.US)$ gained 1.29%, $Utilities Select Sector SPDR Fund (XLU.US)$ up 1.05%, $The Communication Services Select Sector SPDR® Fund (XLC.US)$ up 0.83%, $Real Estate Select Sector Spdr Fund (The) (XLRE.US)$ up 0.55%. $The Technology Select Sector SPDR® Fund (XLK.US)$ down 1.78%, $Energy Select Sector SPDR Fund (XLE.US)$ declined 0.83%, $Industrial Select Sector SPDR Fund (XLI.US)$ Down 0.69%.
From a sub-sector perspective, the consumption chain showed relative resilience, $SPDR S&P Retail ETF (XRT.US)$ up 1.30%, $Proshares Online Retail Etf (ONLN.US)$ up 1.28%, $Invesco Leisure & Entertainment Funds (PEJ.US)$ up 1.25%. Weakness was concentrated in the AI chain: $Roundhill Memory ETF (DRAM.US)$ down 5.89%, $VanEck Semiconductor ETF (SMH.US)$ down 2.43%, $Global X Robotics & Artificial Intelligence Thematic ETF (BOTZ.US)$ down 2.19%. The optical communication/optical module portfolio fell by an average of 6.48%, $Applied Optoelectronics (AAOI.US)$ down 13.77%, $Ciena (CIEN.US)$ down 6.02%, $Coherent (COHR.US)$ down 4.85%, $Lumentum (LITE.US)$ down 4.22%; the AI storage portfolio averaged a decline of 5.86%, $Seagate Technology (STX.US)$ down 6.51%, $Micron Technology (MU.US)$ down 5.83%, $Western Digital (WDC.US)$ down 5.24%.
3. The Magnificent Seven Tech Stocks
The Magnificent Seven showed divergent performance. Meta rose 1.66%, Microsoft (MSFT) gained 0.84%, Google (GOOG) increased 0.83%, and Apple (AAPL) edged up 0.15%; Netflix fell 1.12%, NVIDIA (NVDA) dropped 2.91%, and Tesla (TSLA) declined 3.83%. While Meta, Microsoft, and Google provided some support to the index, NVIDIA and Tesla exerted more significant downward pressure. Ahead of NVIDIA's earnings report, AI-related trading continued to cool off, with high-valuation tech stocks failing to rebound alongside the drop in US Treasury yields.
4. Chinese ADRs
Chinese concept stocks were generally weak. $KraneShares CSI China Internet ETF (KWEB.US)$ down 1.43%, $Futu Holdings Ltd (FUTU.US)$ down 6.33%, $NetEase (NTES.US)$ down 4.06%, $Bilibili (BILI.US)$ down 3.28%, $Tencent Music (TME.US)$ down 1.98%, $Baidu (BIDU.US)$ down 1.72%, $Alibaba (BABA.US)$ down 1.40%, $PDD Holdings (PDD.US)$ down 0.93%, $JD.com (JD.US)$ down 0.58%. Profit-taking was more pronounced among the previous session's strong performers, with Futu and NetEase leading the declines. News regarding Alibaba's financing continued to weigh on sentiment for Chinese tech stocks, and KWEB did not participate in the recovery seen in the Dow Jones and defensive sectors.
5. Cryptocurrencies
Bitcoin rose 1.47%, closing at $78,740.00. Cryptocurrency-related stocks did not strengthen in tandem, $Strategy (MSTR.US)$ up 2.83%, $Circle (CRCL.US)$ down 0.30%, $MARA Holdings (MARA.US)$ down 0.71%, $Coinbase (COIN.US)$ Down 2.52%, $Riot Platforms (RIOT.US)$ Down 3.50%, $Robinhood (HOOD.US)$ Down 4.17%. Crypto prices remain resilient, but exchanges and miners are starting to give back gains. The cryptocurrency sector has shifted from the broad-based rally of recent days to a divergent pattern where Bitcoin is outperforming related equities.
$S&P 500 Index (.SPX.US)$ $SPDR S&P 500 ETF (SPY.US)$ $NASDAQ 100 Index (.NDX.US)$ $Invesco QQQ Trust (QQQ.US)$ $Dow Jones Industrial Average (.DJI.US)$ $State Street® SPDR® Dow Jones Industrial Average® ETF Trust (DIA.US)$ $Russell 2000 Index (.RUT.US)$ $iShares Russell 2000 ETF (IWM.US)$ $Roundhill Magnificent Seven ETF (MAGS.US)$ $USD (USDindex.FX)$ $U.S. 10-Year Treasury Notes Yield (US10Y.BD)$ $iShares 20+ Year Treasury Bond ETF (TLT.US)$ $XAU/USD (XAUUSD.CFD)$ $SPDR Gold ETF (GLD.US)$ $CBOE Volatility S&P 500 Index (.VIX.US)$ $CME-Bitcoin RR Futures (SEP6) (BTCmain.US)$ $iShares Ethereum Trust ETF (ETHA.US)$ $NVIDIA (NVDA.US)$ $Tesla (TSLA.US)$ $Meta Platforms (META.US)$ $Amazon (AMZN.US)$ $Alphabet-C (GOOG.US)$ $Microsoft (MSFT.US)$ $Apple (AAPL.US)$
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments
to post a comment
8