NVIDIA's revenue doubles, beating expectations; is the AI trade narrative making a comeback?
[This Week's Market Watch] NVIDIA and the Central Bank Symposium Take Center Stage: Where Are US Stocks Headed? | Plus: Guide to 4 High-Dividend Stocks Going Ex-Dividend, Hot IPOs, and 4.25% Retail Bonds
Hello, fellow investors! Looking back at last week's market performance, the summary in one sentence is—High long-end US Treasury yields are putting pressure on growth stocks, Hong Kong stocks are showing structural resilience, and the trading logic for the AI sector is quietly being reshaped.So, what are the major market events this week? And how should we seize the investment opportunities within them? Let's take a look together.
I. Recap of Last Week's Market Trends
Before we dive into this week's macroeconomic and industry opportunities, let's start with a concise recap of last week's market to help you quickly clarify the underlying market logic:
– Macroeconomy
◦ US Treasuries remain the core pricing anchor: After the US Treasury expanded its long-term bond buyback program, the yield on 30-year US Treasuries quickly returned to around 5.25% following a brief dip. This reflects that buybacks can only improve liquidity but cannot resolve structural issues such as fiscal deficits. Valuations for long-duration growth stocks continue to face pressure.
◦ Cross-asset trading divergence: The market has diverged along two main lines: first, "fiscal credit concern trades" are driving strength in gold, silver, and Bitcoin (BTC, up approximately 20% for the week); second, geopolitical tensions in the Middle East are pushing oil prices higher and suppressing risk assets through inflation expectations.
◦ Expectation gaps emerge in the FX market: The phenomenon of "rising US Treasury yields coupled with a weakening US dollar" warrants continued observation. The Japanese Yen (JPY) remains weak near the 158–159 level despite rate hike expectations, presenting a potential trade setup worth waiting to confirm next week.
– Stock market
◦ US stocks weaken, but systemic risk is not evident: The S&P 500 fell ~1.4% and the Nasdaq dropped ~2.1% for the week. This is essentially a repricing of high-valuation assets in a high-interest-rate environment, as the market becomes more stringent about what level of growth justifies current valuations.
◦ Hong Kong stocks demonstrate structural resilience: The Hang Seng Index rose approximately 3.55% for the week, with innovative drugs and gold resources among the stronger-performing sectors. However, tech platform stocks have not yet seen a broad-based upward revision in earnings expectations, maintaining the characteristic of "prioritizing sectors and companies over the index."
◦ The trading logic for AI is quietly shifting: The AI sector is beginning to transition from a pure "demand narrative" phase to a "capital return" phase. Market attention has significantly shifted toward Free Cash Flow (FCF) and Internal Rate of Return (IRR) on projects, surpassing the focus on mere revenue growth.
Against this backdrop, this week will bring a series of impactful macroeconomic events, industry earnings reports, as well as notable dividend yield and fundraising opportunities in the Hong Kong stock market.
II. Key Macro Events and Market Opportunities
This week, the main theme at the macro level willcontinue to revolve around interest rate paths and inflation expectations,with these two core focal points directly determining the short-term success rates across major asset classes.
1. Dual test of US PCE and GDP data (Beijing Time, August 26)
The first key milestone this week is the release of the US Personal Consumption Expenditures (PCE) price index and the second estimate of Q2 GDP.
– Opportunity Analysis: If the PCE data comes in hot, it will push real interest rates higher, creating short-term volatility pressure for high-valuation tech sectors and gold, which is recently at historical highs. Conversely, if the PCE data is moderate but the 30-year US Treasury yield remains elevated, it suggests that "term premium pressure" (concerns over fiscal deficits) warrants greater caution.
– Investor Focus:Gold remains the trend asset with the most coherent investment thesis, but investors should be mindful of valuation risks at current highs. Regarding US Treasuries, long-duration bonds have not yet formed a clear bottom. Currently, assets such as short-term bonds or cash management products that offer stable interest income may provide better risk-adjusted returns.
2. Jackson Hole Central Bank Symposium
The annual Jackson Hole Global Central Bank Symposium is approaching,and the market will use this opportunity to reassess the next phase of the interest rate path. 。
– Opportunity Analysis:
The focus of the symposium is whether a credible framework for inflation and balance sheet policy can be established to effectively suppress long-end yields. If long-term rates continue to break through the 5.30%–5.35% range, chasing high-valuation US equity assets still carries a low probability of success.
III. Major Industry Events and Market Opportunities
At the industry and individual stock level, the earnings reports from US AI leaders and the intensive disclosure season for Chinese concept stocks listed in Hong Kong will provide new performance validation for the market.
1. The most important pricing anchor for US stocks this week—the release of NVIDIA (NVDA) earnings
– Opportunity Analysis:
Market expectations for NVIDIA are currently extremely elevated. Investors are not only demanding earnings that exceed guidance but also requiring strong performance in gross margins, revenue from the China market, and the quality of customer financing. Against the backdrop of high expectations and high long-term bond yields, a scenario of "meeting expectations but lacking surprises (a Beat that isn't impressive enough)" could still trigger sell-offs as investors take profits on the good news.
– Investor Focus:
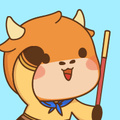
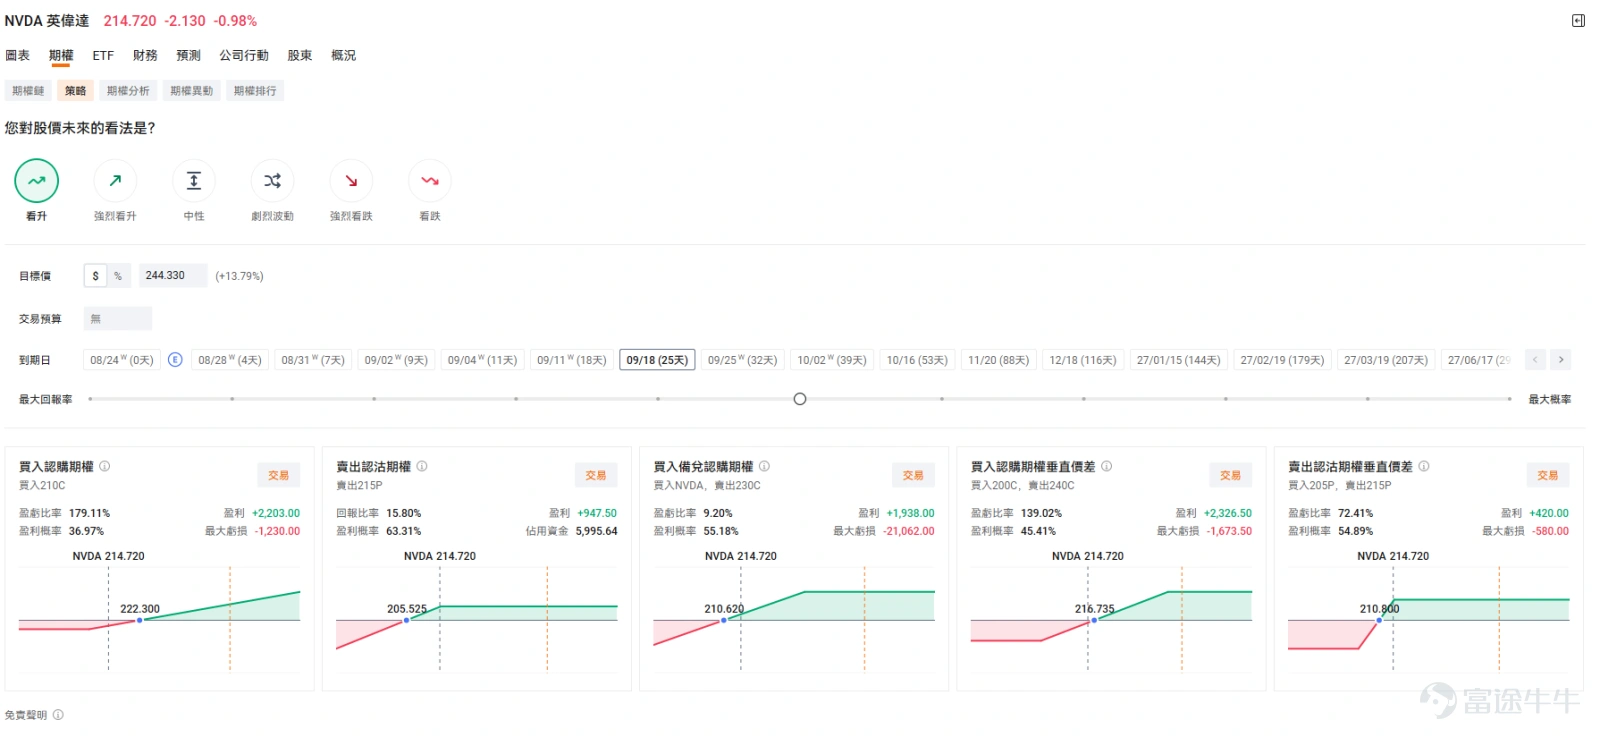
Investors should focus on the earnings guidance for the October quarter and the shipment progress of Blackwell chips. Market volatility may increase significantly before NVIDIA releases its financial report. In addition to holding the underlying stock, investors can use options strategies to amplify returns. You can explore these strategies in the Futubull app under Individual Stock Details > Options Strategies.
2. AI Main Theme: Transitioning from a "Demand Narrative" to "Capital Returns"
As US tech stocks continue to release their earnings reports, including $HP Inc (HPQ.US)$ 、 $CrowdStrike (CRWD.US)$ 、 $Marvell Technology (MRVL.US)$ the performance of AI-related companies has also become a market focal point.
– Opportunity Analysis:
The AI industry is undergoing a profound paradigm shift. The market no longer simply rewards companies for announcing increased AI capital expenditures (Capex); instead, it is strictly scrutinizing when these investments will translate into profits and cash flow. Currently, capital expenditures by Hyperscalers have exceeded $60 billion, with a rising proportion of debt financing. Consequently, the market is imposing stricter requirements on Return on Invested Capital (ROIC) and Free Cash Flow (FCF) regarding these substantial investments.
– Investor Focus:
When evaluating targets in the AI sector, investors should重点 compare each company'sAI revenue growth rate, gross margin, Operating Cash Flow (OCF)/Free Cash Flow (FCF), and guidance for the next quarter. It is particularly important to note that for highly leveraged Neocloud providers like CoreWeave, significant expansion in capital expenditure means that rising financing costs in the current high-interest-rate environment will suppress their profit margins far more severely than for cash-rich Mega-cap tech giants. Therefore, at this stage, tech giants with abundant cash flow and self-sustaining capabilities may offer a higher margin of safety compared to high-debt AI infrastructure concept stocks.
3. Heavy HK stock earnings season and Alibaba (BABA) placement
This week $MEITUAN-W (03690.HK)$ 、 $PDD Holdings (PDD.US)$ 、 $XPENG-W (09868.HK)$ 、 $LI AUTO-W (02015.HK)$ 、 $BILIBILI-W (09626.HK)$As leading Chinese concept stocks are set to release their earnings reports in quick succession, while $BABA-W (09988.HK)$ facing the market's capacity test following a proposed HK$80 billion placement.
– Opportunity Analysis:
Alibaba faces short-term pressure from discounted placements and share dilution, but the medium-term focus lies in whether new AI capital can drive cloud business profits and Free Cash Flow (FCF) growth that outpaces equity expansion. The ability to quickly secure capital support near the placement price holds greater forward-looking market significance than simply discussing the "negative impact of the placement."
– Investor Focus:
$BABA-W (09988.HK)$$Alibaba (BABA.US)$ On the technical side: Closely monitor the support level for the HK-listed stock price near the placement price of HK$112.7. As this placement has already been oversubscribed by long-term capital such as sovereign wealth funds, if the stock price can stabilize above the placement price, market confidence will be significantly boosted. Additionally, continue to track the growth trajectory of its AI Annual Recurring Revenue (ARR) (currently exceeding RMB 49.5 billion), as well as management's progress in recouping AI investment costs within the expected 2 to 3 years.
Regarding earnings reports from other leading Chinese concept stocks: This quarter's earnings require a close examination of the extent to which the subsidy war between Meituan and Alibaba in food delivery and instant retail has eroded short-term profit margins. Meanwhile, the latest guidance from XPeng and Li Auto on AI autonomous driving, Robotaxi deployment, and gross margins for new models will directly determine the valuation recovery potential for the new energy vehicle sector.
4. Dividend Opportunities: Selected 4 High-Yield Stocks Going Ex-Dividend This Week
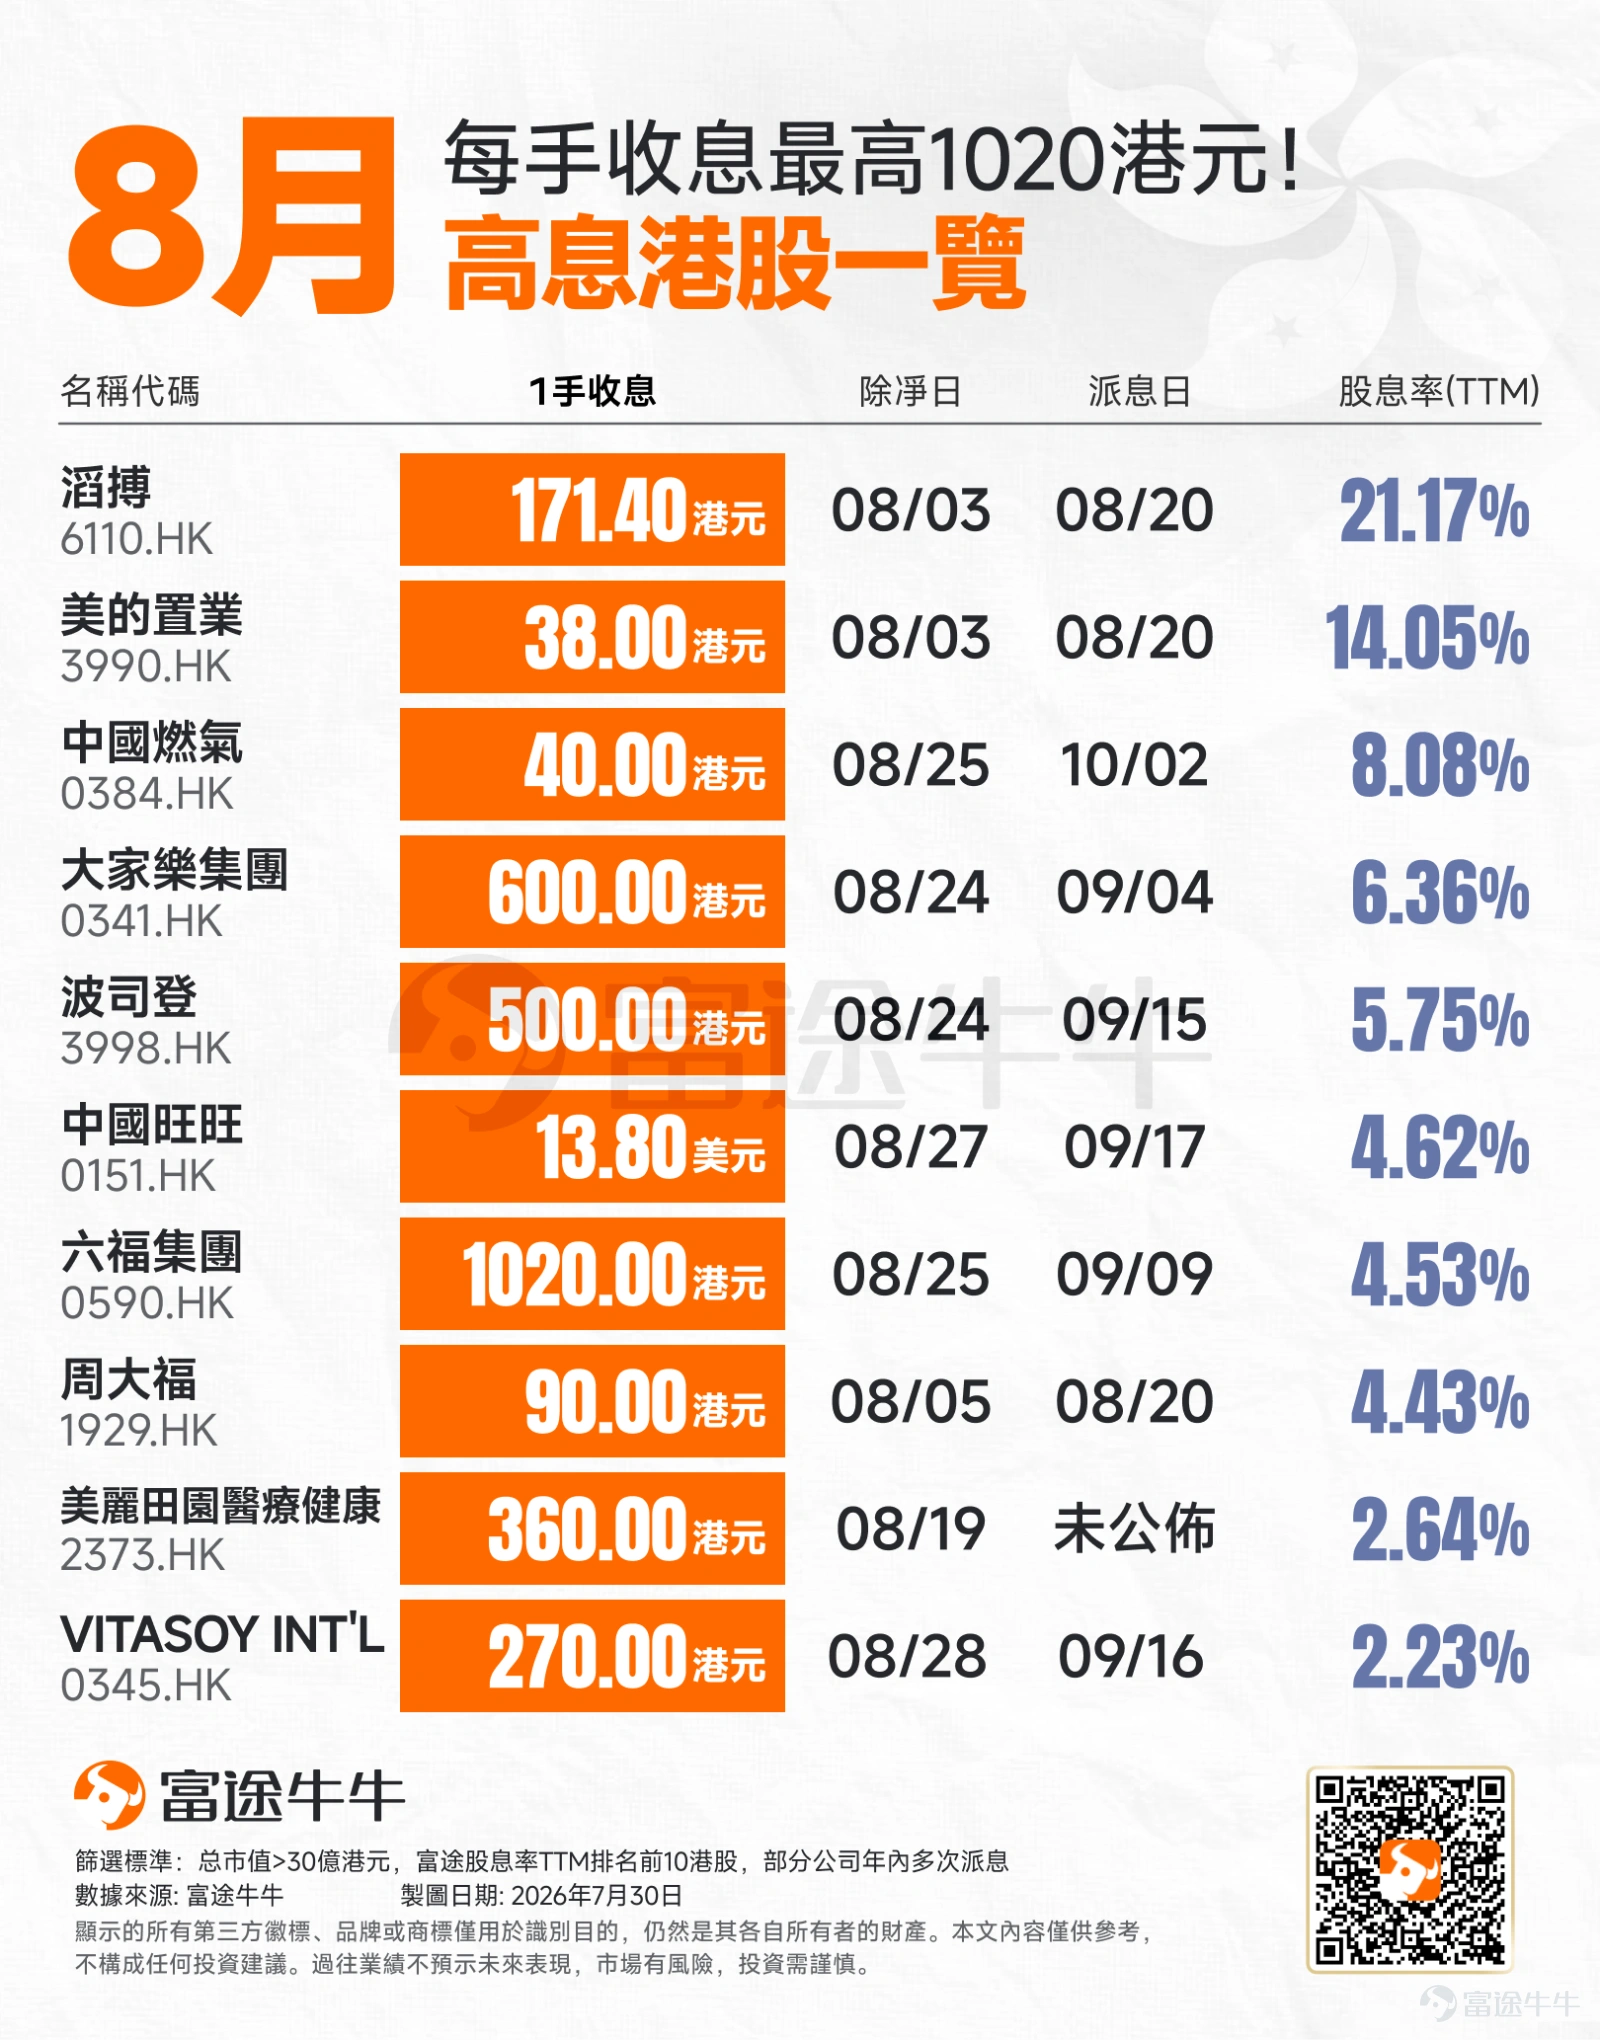
During periods of market volatility, high-certainty dividend-paying stocks often serve as a "defensive safe haven" in asset allocation. This week, four high-yield stocks in the HK market are approaching their ex-dividend dates; investors should pay close attention to:
– Dividend Yield: 8.08%
– Key Schedule: The company will be on 08/25 Ex-dividend date on 10/02 Dividend payment date on
– Entry barrier: Dividend per lot (200 shares) HKD 40.00。
– Dividend Yield: 4.62%
– Key Schedule: The company will be on 08/27 Ex-dividend date on 09/17 Dividend payment date on
– Entry barrier: Dividend per lot USD 13.80。
– Dividend Yield: 4.53%
– Key Schedule: The company will be on 08/25 Ex-dividend date on 09/09 Dividend payment date on
– Entry barrier: Dividend per lot HKD 1,020.00。
– Dividend Yield: 2.23%
– Key Schedule: The company will be on 08/28 Ex-dividend date on 09/16 Dividend payment date on
– Entry barrier: Dividend per lot HKD 270.00。
5. IPO Opportunities: Embodied AI, Cross-border E-commerce Giants, and Stable Silver Bonds
In the IPO subscription and bond markets, this week also features many highlights, covering new technology, new retail, and government-backed silver bonds:
– Subscription deadline: August 27
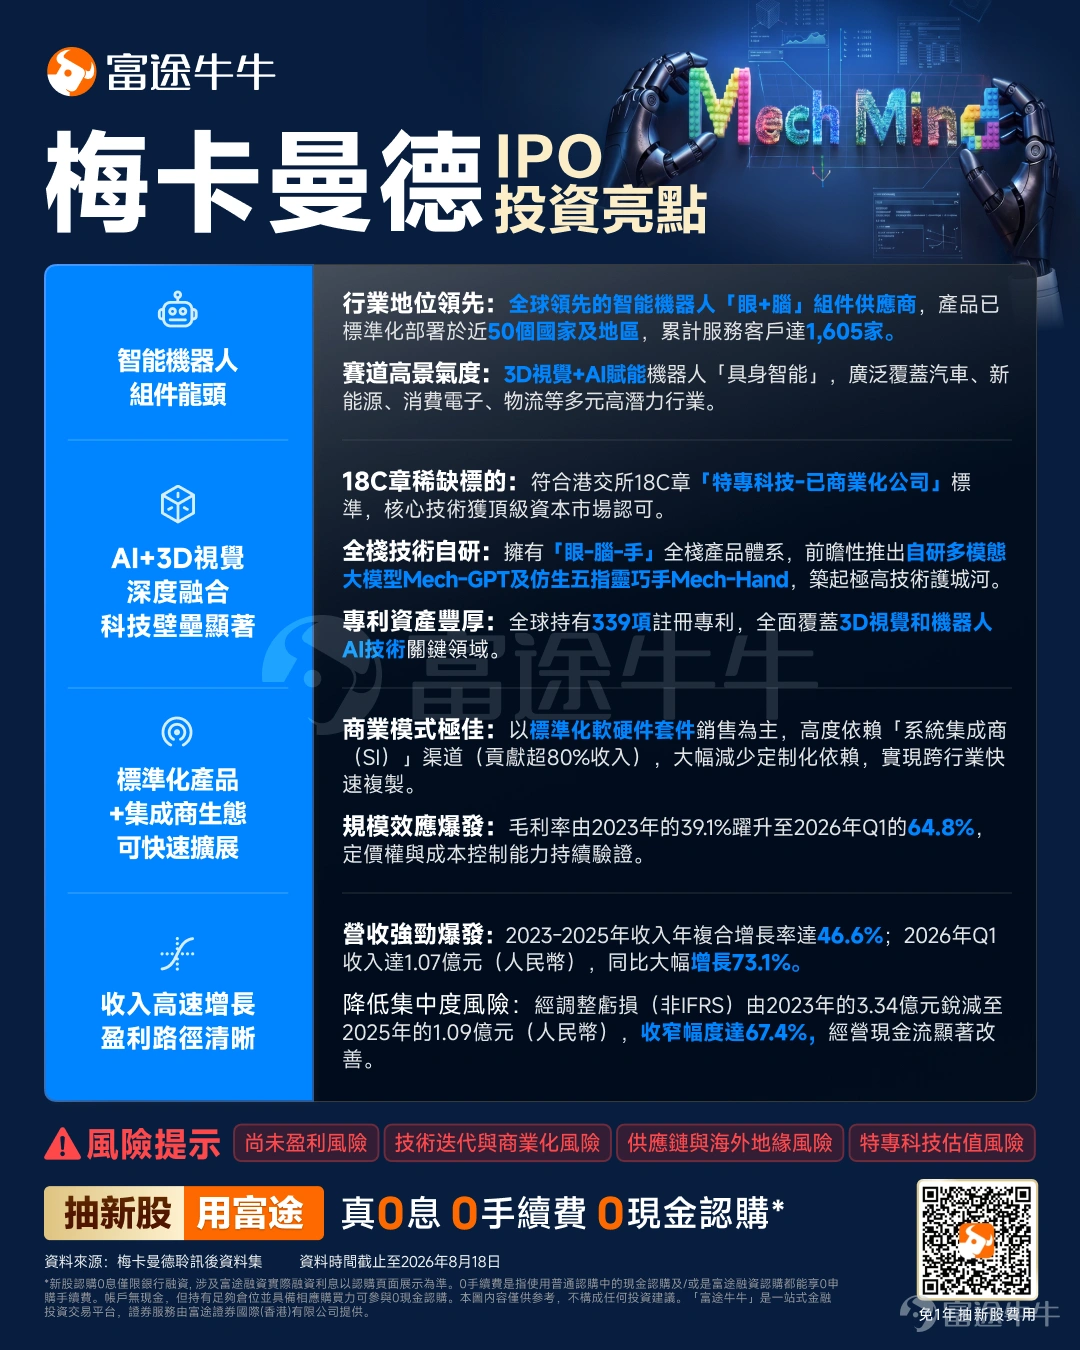
– Project Highlights:Mech-Mind is a recently highly sought-after "embodied AI" concept stock by capital markets, focusing on intelligent robot "eye + brain" components, with a global customer base. The company has launched its own multimodal large model, Mech-GPT, specifically designed for robotic brain decision-making. This listing follows the HKEX's Specialized Technology Companies (Chapter 18C) mechanism, with cornerstone investors accounting for a high 64%, nearly maxed out, demonstrating institutional investors' favor towards its technological prospects and commercialization potential.
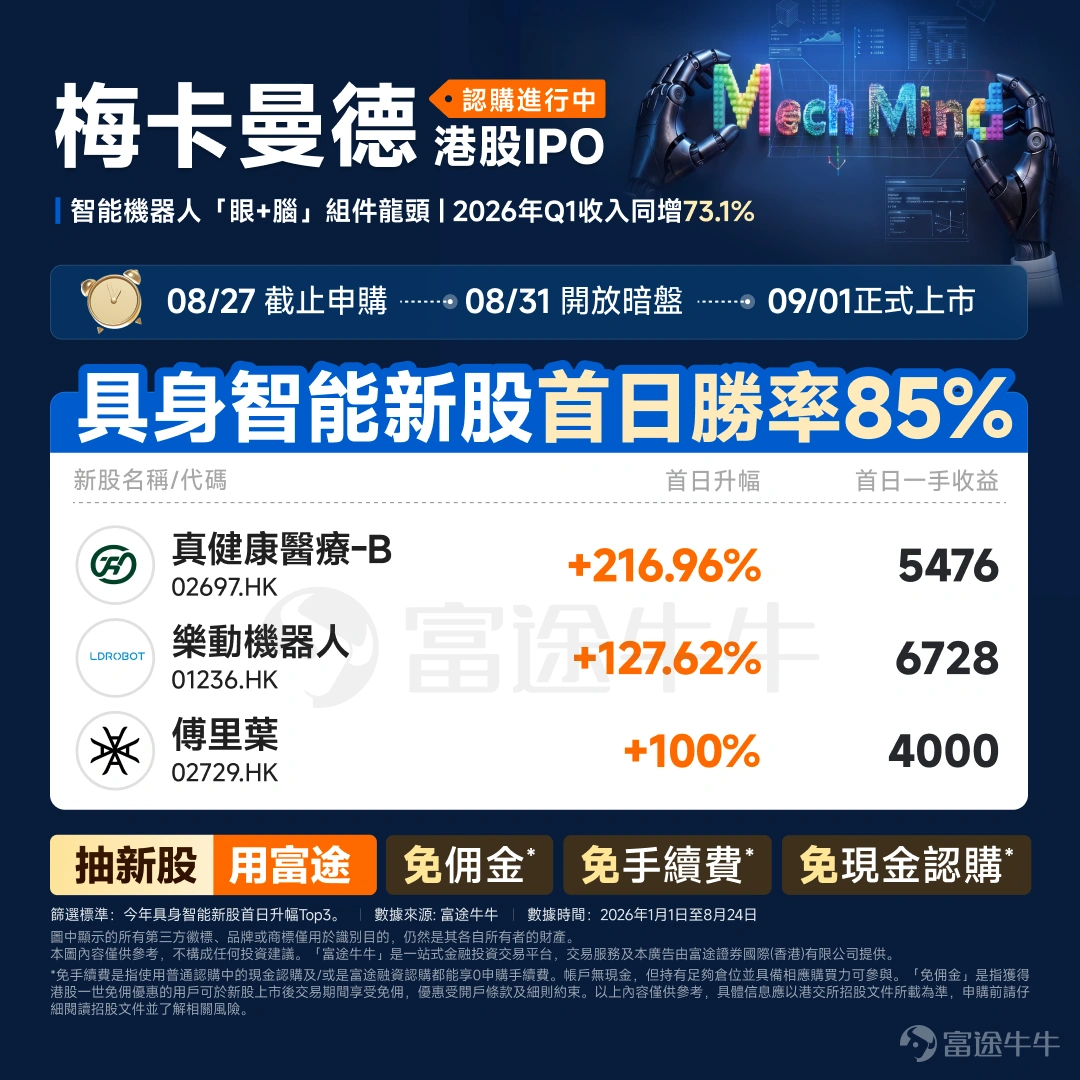
Meanwhile, the first-day win rate for embodied AI IPOs in 2026 is 85%.
– Subscription deadline: August 27
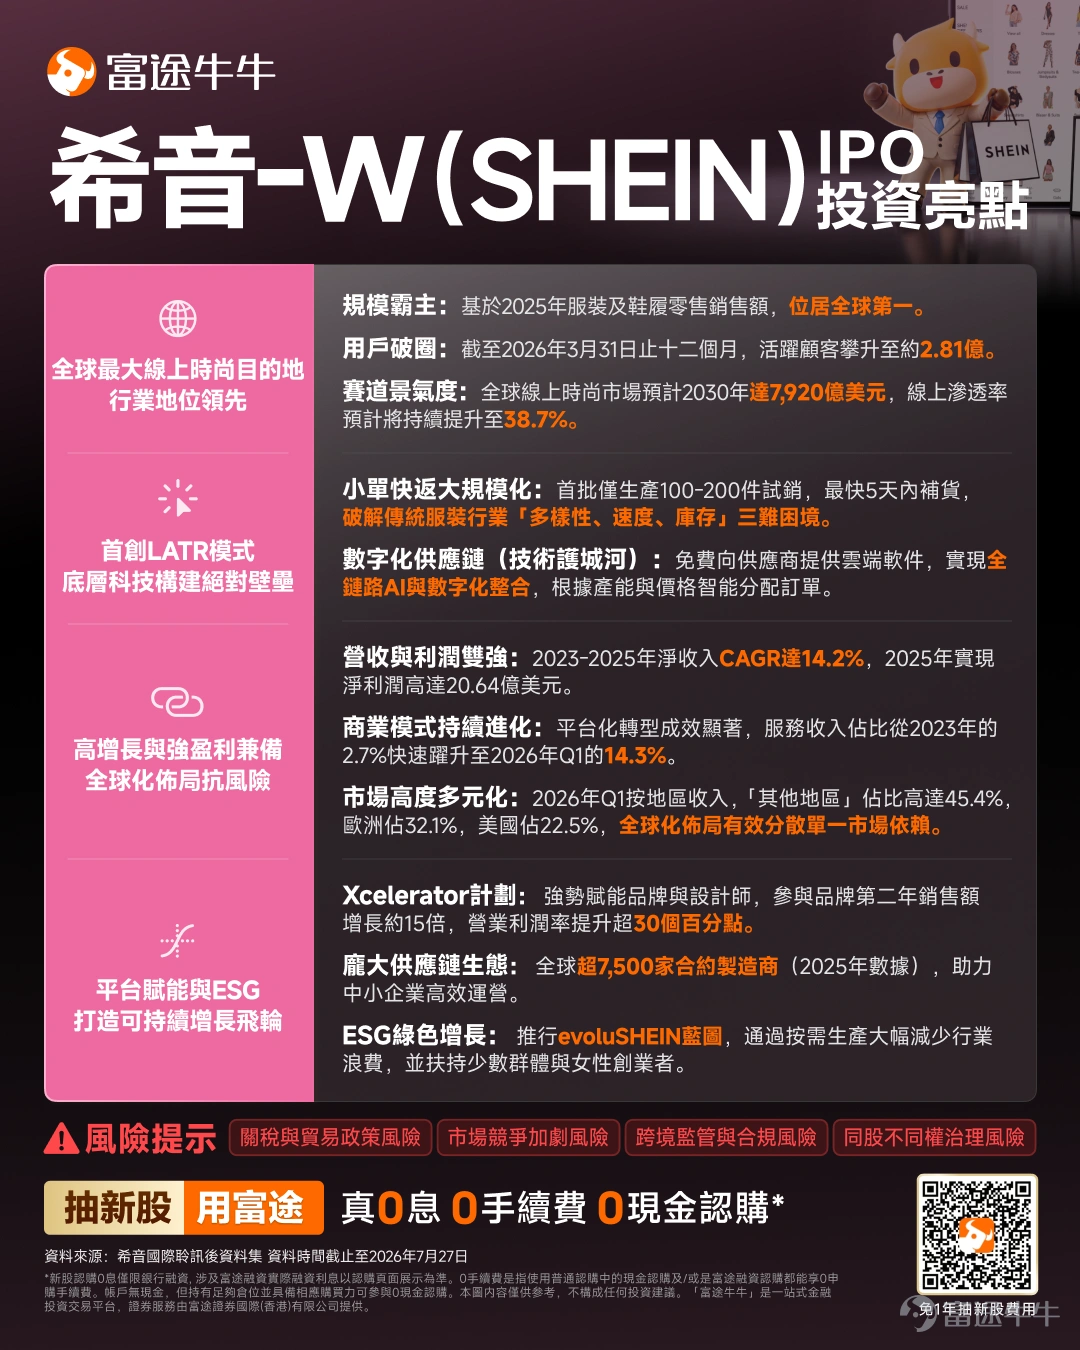
① Note: Source: Shein prospectus, based on 2025 apparel and footwear retail sales.
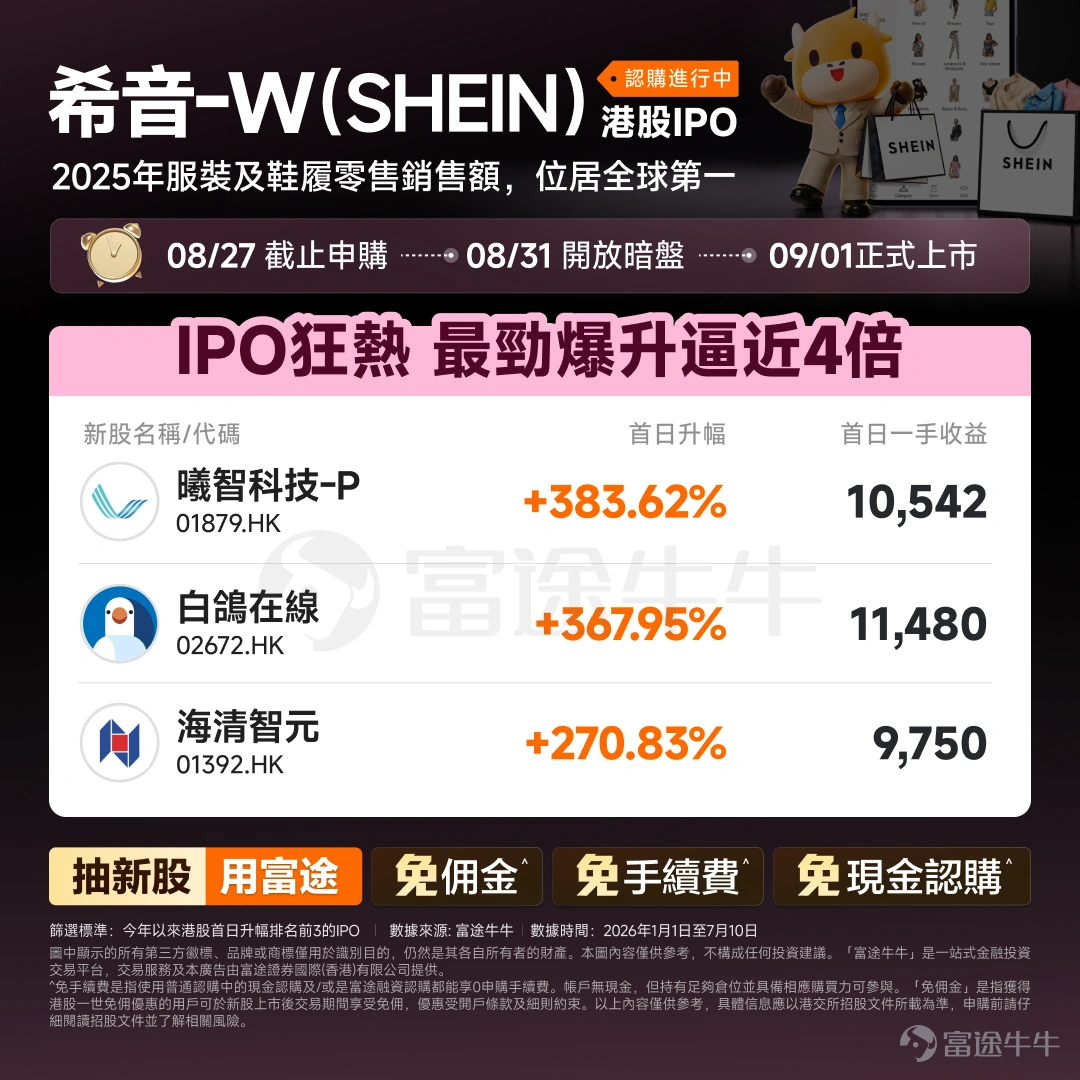
– Project Highlights:As a global retail giant, Shein ranked first worldwide in apparel and footwear retail sales in 2025. Its core moat lies in the scaling of its "small-batch, quick-reorder" model: initial production runs of only 100–200 units are used for test marketing, with restocking completed in as little as 5 days. This effectively resolves the traditional apparel industry's trilemma of variety, speed, and inventory. The financial data is impressive, with a net income compound annual growth rate (CAGR) of 14.2% from 2023 to 2025, and net profit reaching $2.064 billion in 2025. Additionally, the company provides cloud software to suppliers free of charge, achieving end-to-end AI and digital integration, and intelligently allocating orders based on capacity and pricing.
– Subscription deadline: September 4
– Project Highlights:For older investors (Hong Kong residents aged 60 and above) who are unwilling to endure stock market volatility, the Government Silver Bonds offer up to a guaranteed interest rate of 4.25% (fixed rate). Against the backdrop of rising expectations for global rate cuts, locking in a low-risk return of 4.25% for the next three years is quite attractive.
– Futu Exclusive Benefits:To help our investor friends subscribe with ease,Futu is specially launching the "Nine Waivers" super value offer! All fees related to subscribing to silver bonds are fully waived, including:Subscription handling fees, application fees, custody fees, dormant account fees, transfer-in fees, transfer-out fees, interest collection handling fees, early redemption fees, and maturity redemption fees. All fees are completely waived, allowing for zero-cost participation, making your asset growth purer and more worry-free!
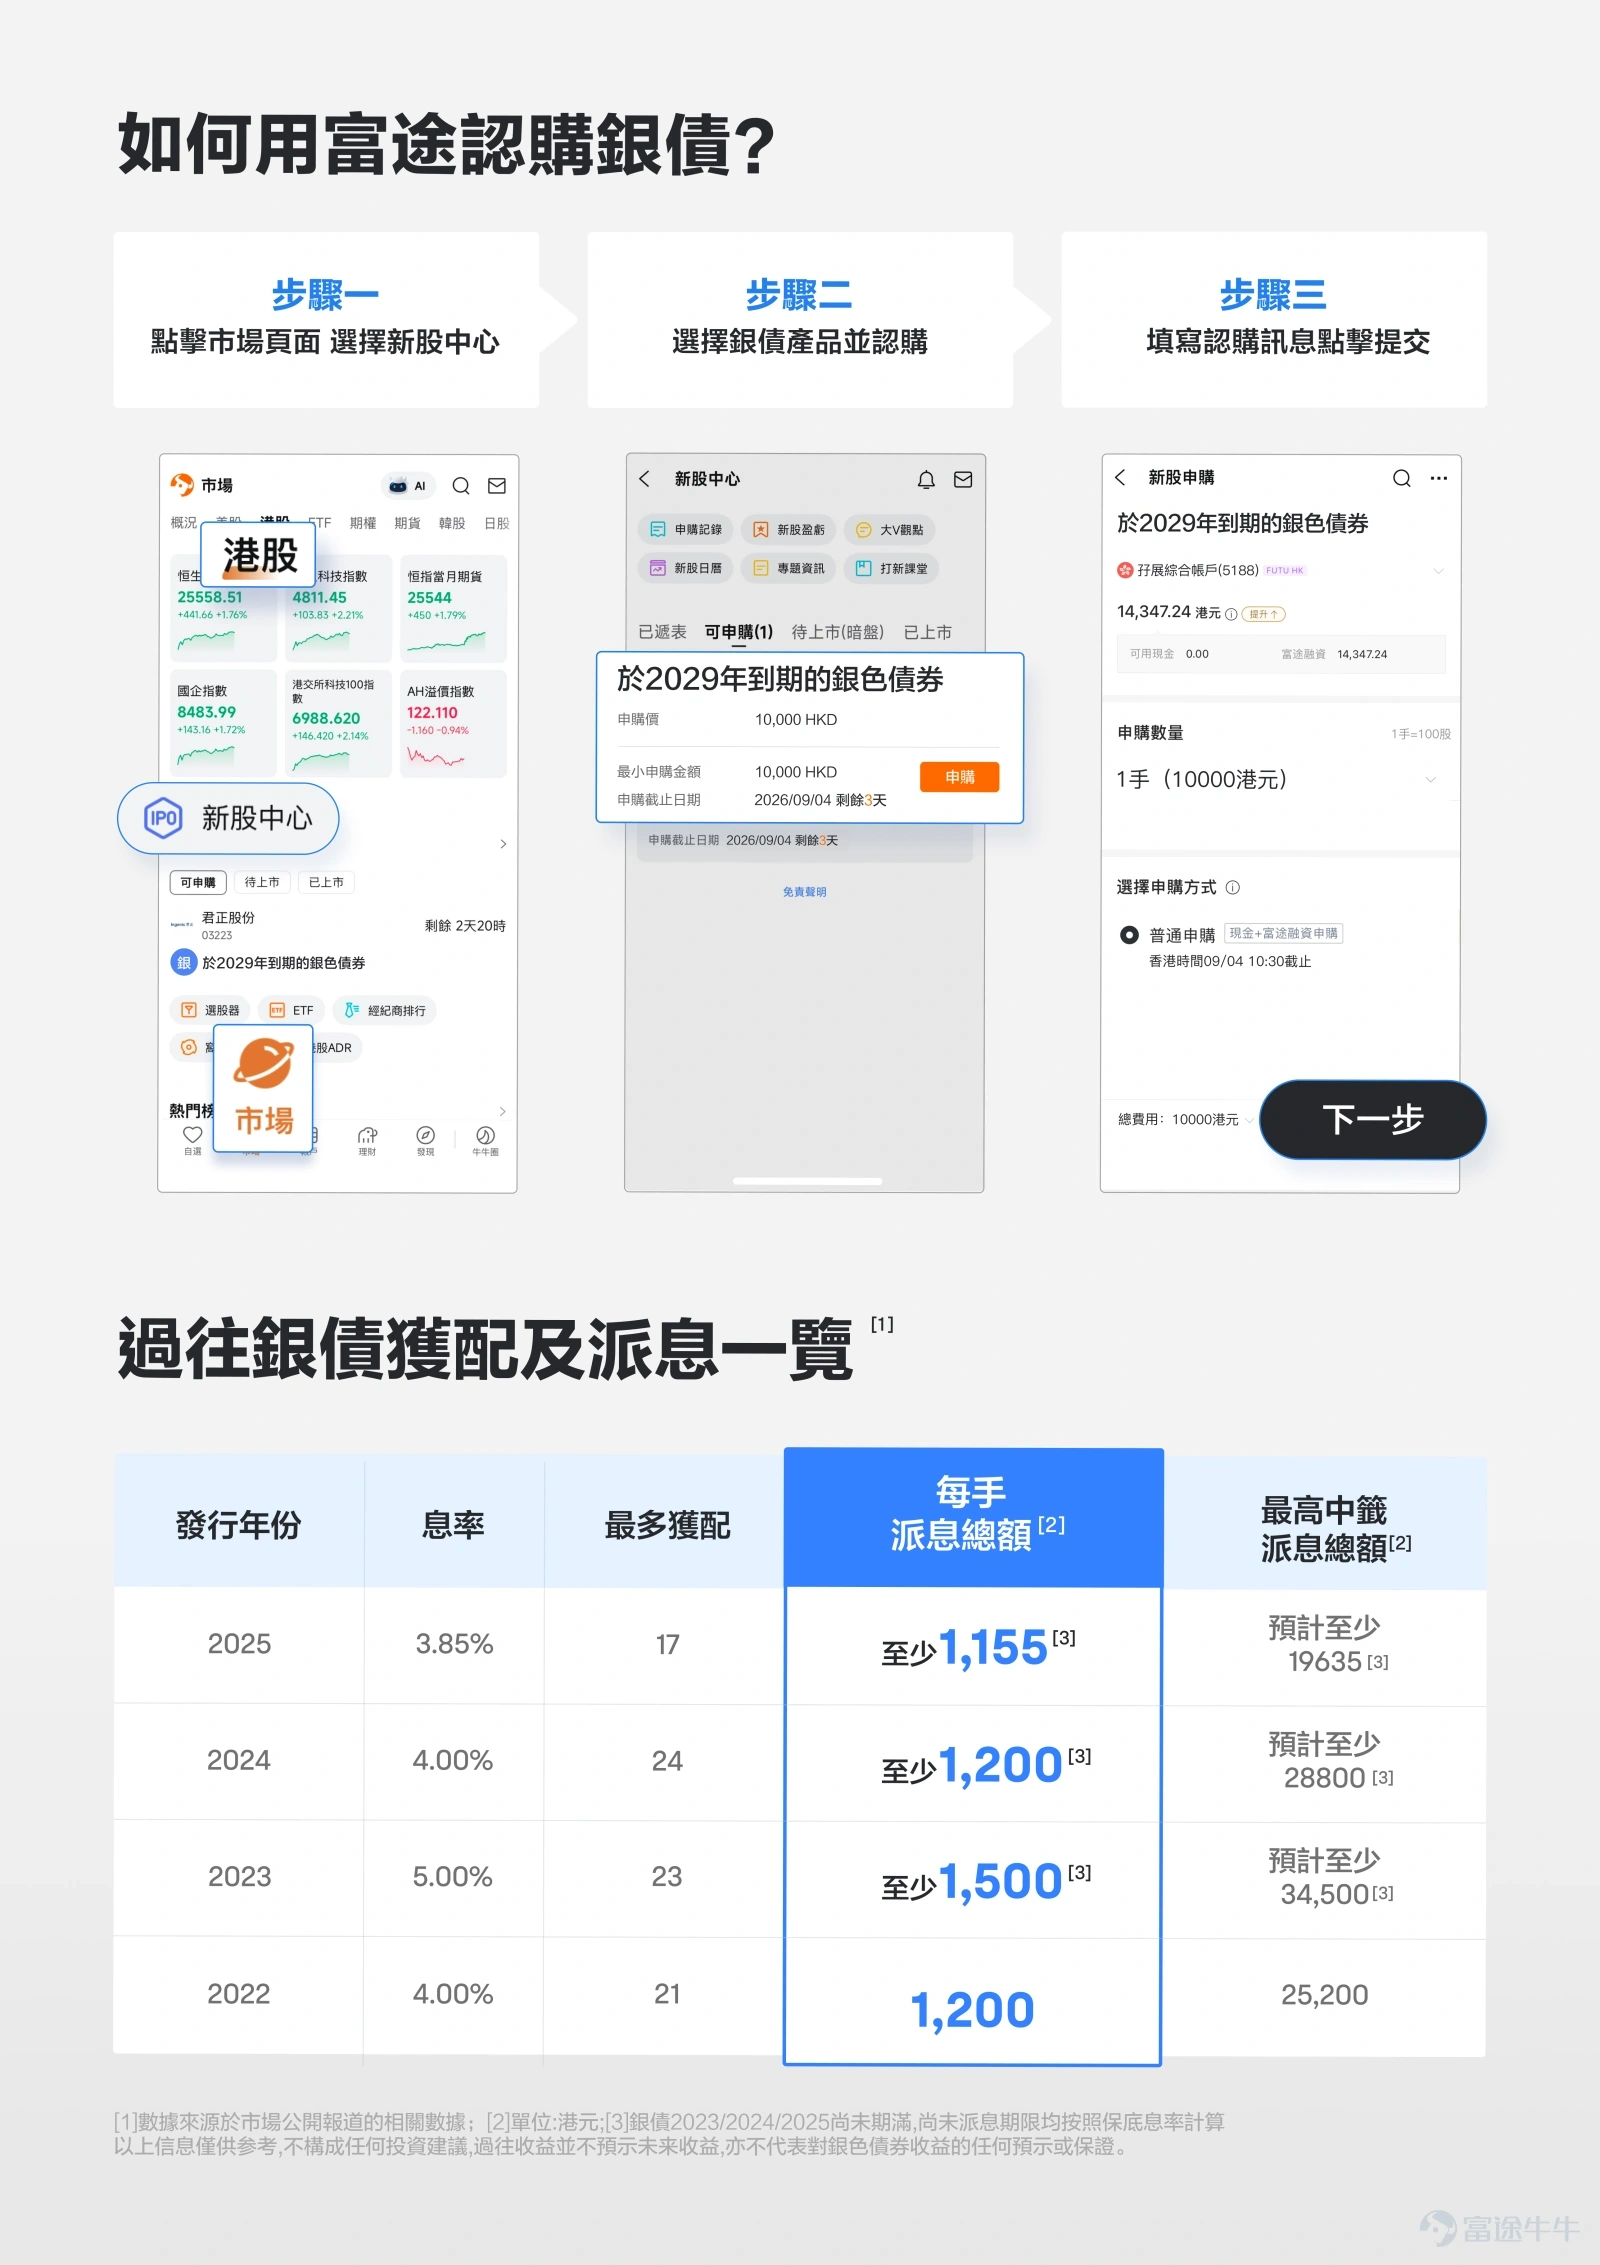
Click the image to learn more about the silver bond issuance
Overall, the market is in a critical "price discovery" phase this week. Whether it's NVIDIA's earnings test or the US PCE data confirming inflation trends, both could trigger significant short-term market volatility.
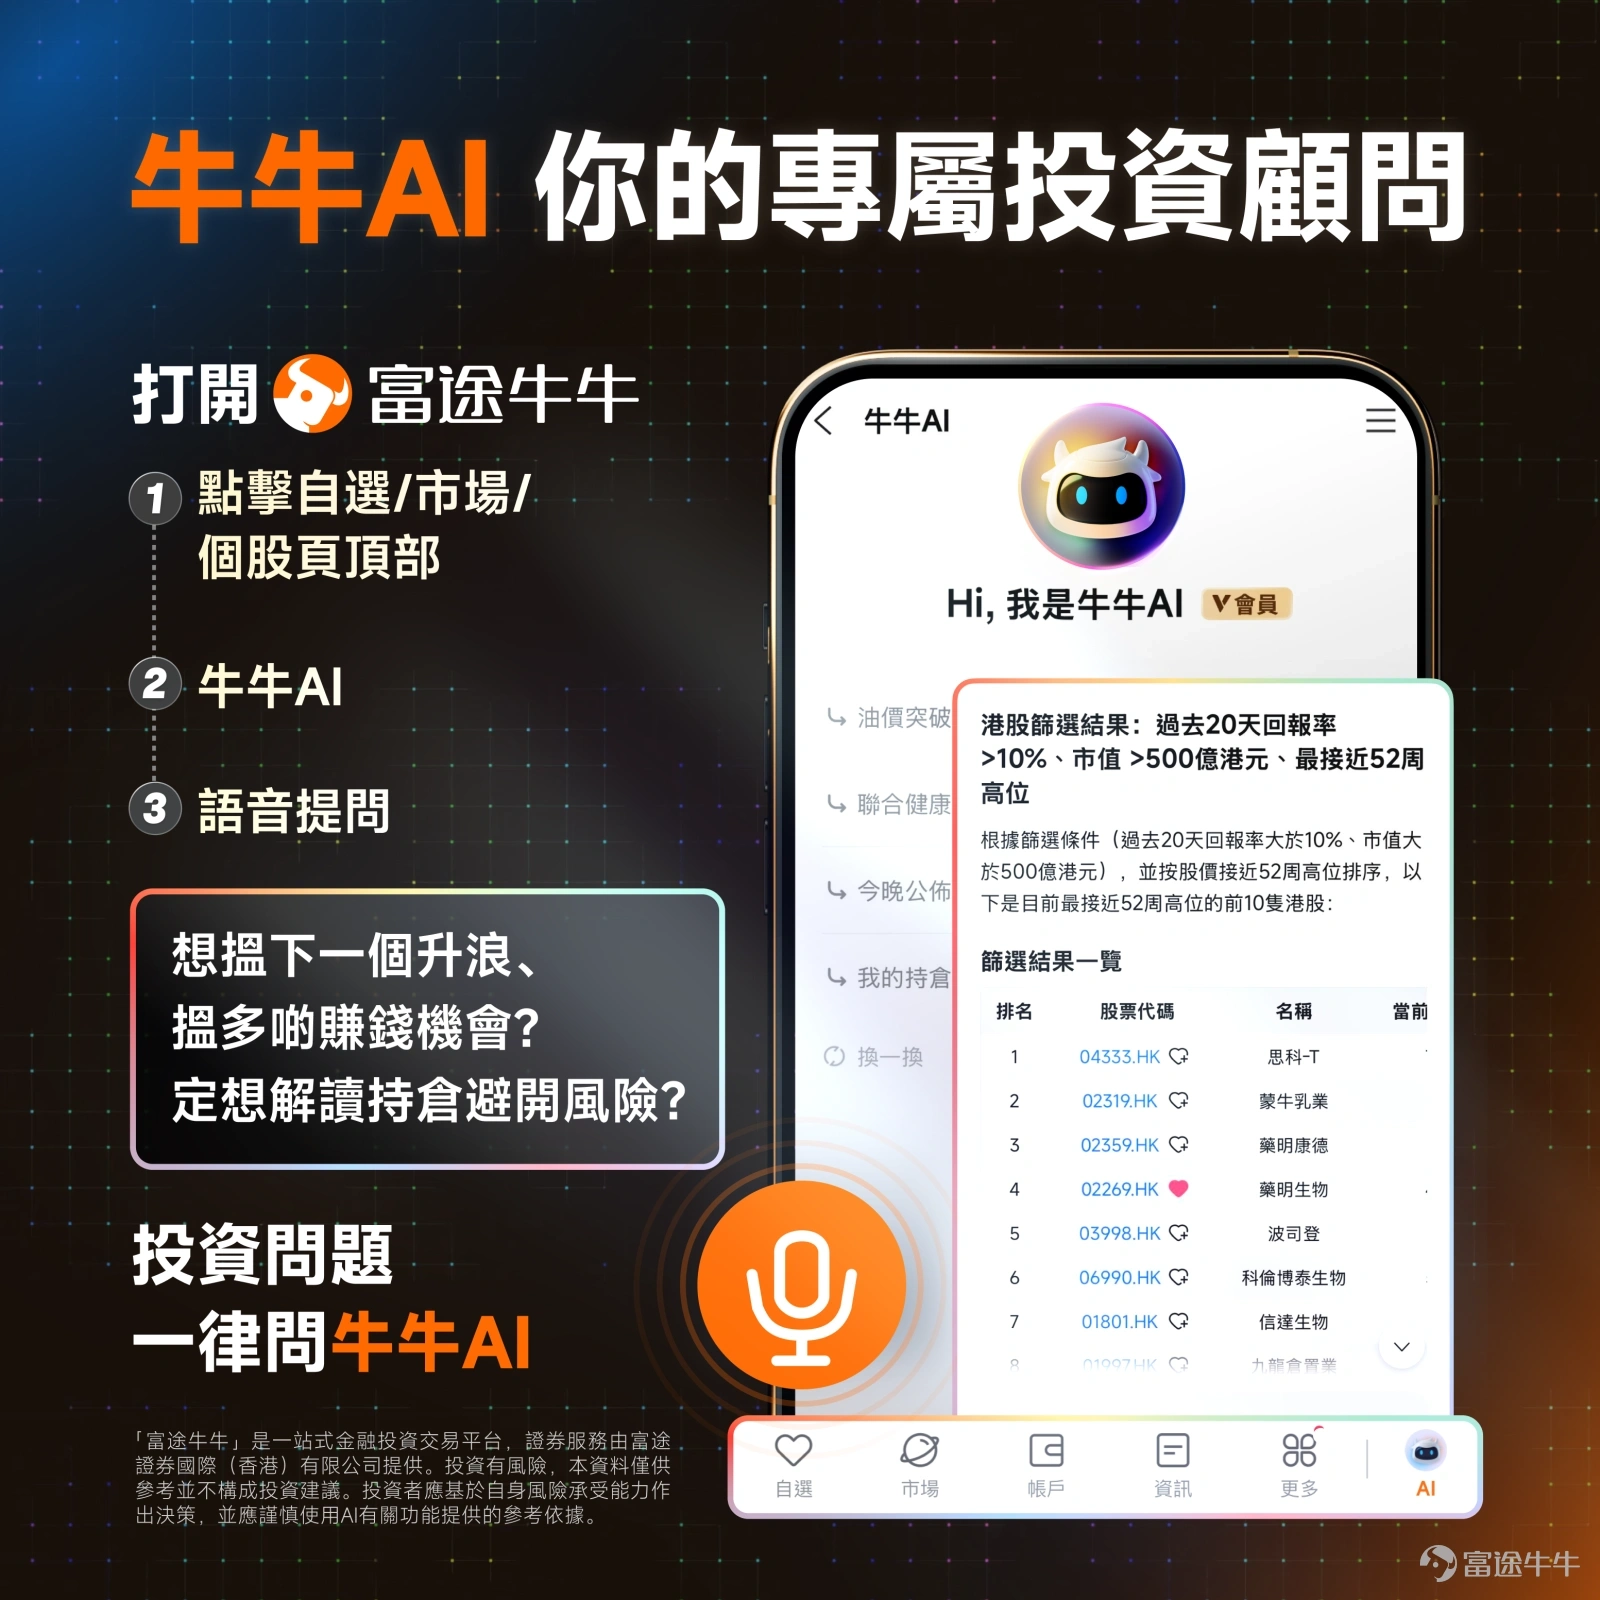
Amidst such a dense flood of information and a volatile market, we recommend that investors focus on tracking one or two core events (such as NVIDIA's earnings report or the performance of Chinese concept stocks).If you are currently unsure or wish to conduct a deeper fundamental analysis of specific stocks, you can use "Futubull AI".
With Futubull AI, you can ask complex questions about earnings highlights, valuation comparisons, or capital flows in individual stocks at any time. Let AI be your dedicated intelligent investment assistant, helping you cut through the market noise and capture high-probability investment opportunities.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comment (1)
to post a comment
46
18