Non-farm payrolls significantly exceeded expectations, reigniting speculation about a September rate

Long-term bond yields soar, tech stocks pull back in unison: Is this a crisis or a stress test for the AI bull market?
Global markets are once again being choked by US Treasuries.
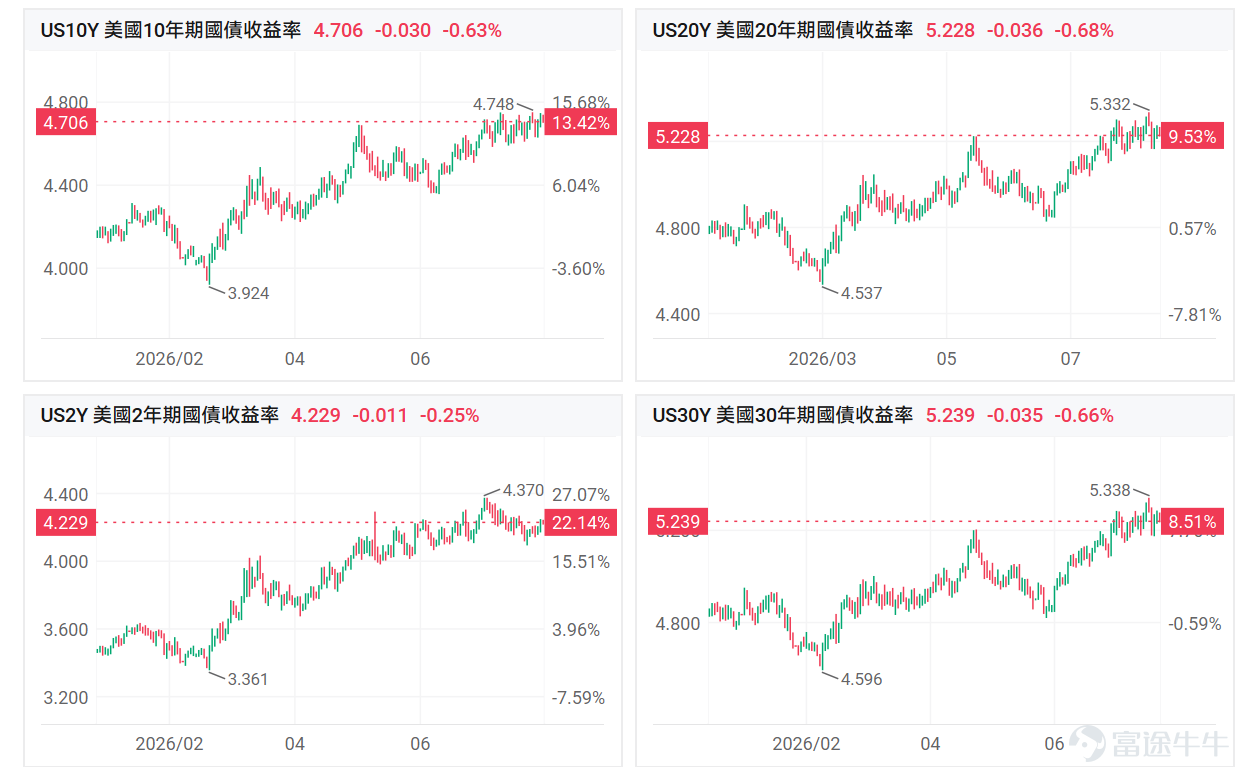
As of August 24, $U.S. 10-Year Treasury Notes Yield (US10Y.BD)$ rose to 4.706%, $U.S. 30-Year Treasury Bonds Yield (US30Y.BD)$ reached 5.228%. Long-term bond prices were sold off, leading to a pullback in tech stocks. The US Treasury also announced that it would raise the single repurchase limit for 10- to 30-year US Treasuries from $2 billion to at least $4 billion, in an attempt to improve long-term bond liquidity.

--
--
--
The market's most pressing question is:Why did US Treasuries suddenly drop? Will this round of adjustments in US stocks evolve into a larger liquidity crisis?
Why have US Treasury yields surged, and why have US stocks fallen?
On the surface, the recent decline in US Treasuries stems from increased supply. The US Treasury expects net borrowing of $739 billion in the third quarter, which, combined with debt financing by tech giants, has raised concerns about long-term capital being heavily competed for by a surge in bond issuance.
In reality, supply has not spiraled completely out of control. Nearly half of the U.S. Treasury issuance for the third quarter was completed in July, with long-dated bonds accounting for only about 15% of the planned net issuance.
The real issue is that investors' willingness to hold long-dated bonds has declined.CICC estimates show that since the end of June, the yield on the 10-year U.S. Treasury note has risen by approximately 34 basis points, of which the term premium increased by about 30 basis points, while changes in policy rate expectations were relatively limited.
In other words, investors are not unwilling to hold all US Treasuries; rather, they demand higher returns to bear the uncertainty over the next ten or even thirty years. There are three main reasons behind this:
1. The US fiscal deficit and long-term debt supply continue to increase;
2. Policy statements since Walsh took office have been ambiguous, leading to a lack of market confidence in the Federal Reserve's reaction function;
3. The AI industry lacks new earnings catalysts, prompting the market to reassess the financing costs and return on investment of tech giants.
For US equities, Treasury yields serve as the 'discount rate' for asset valuation. The higher the long-end interest rates, the lower the present value of future earnings. Consequently, high-valuation, crowded-tech stocks are the first to face sell-offs.
Is this a liquidity crisis?
From the current perspective, not yet.
According to CICC data, as of August 17, the SOFR-OIS spread remained at low levels, and credit bond spreads widened only slightly; the VIX stood at approximately 15.84, and the MOVE Index (US Treasury volatility) was around 74.98, neither entering crisis territory. Bank reserves accounted for about 11.7% of total assets; while not particularly abundant, there was no significant shortage.
This indicates that current pressure is primarily concentrated on the pricing of long-end US Treasuries, rather than a breakdown in the USD funding chain.Liquidity shocks typically cause severe volatility, but markets are expected to recover once the central bank or treasury provides liquidity; a true debt crisis requires a chain reaction involving high leverage, collateral devaluation, forced liquidations, and credit defaults.
These signals have not been observed so far.However, if falling US Treasury prices trigger sell-offs that further push up yields, we must remain vigilant against negative feedback loops evolving into genuine liquidity issues.
Reviewing six US stock market corrections: US Treasuries were the trigger, but not the ultimate direction
According to statistics from GF Securities, there have been six notable corrections in the US stock market since 2023, lasting an average of about 40 trading days. $S&P 500 Index (.SPX.US)$ The average decline was 8.8%, with the Magnificent 7 (MAG7) dropping an average of 13.4%, $PHLX Semiconductor Index (.SOX.US)$ Average decline of 17.6%. Among them,U.S. Treasuries have repeatedly served as the trigger for market corrections, but fluctuations in yields alone do not determine the direction of U.S. equities.

Since 2023, liquidity has been the trigger for several corrections in the U.S. stock market, but it has not altered the overall trend.During liquidity shocks, the market experiences phased corrections; however, once liquidity issues are resolved, the market returns to its original upward trend.
Specifically, there have been six corrections in the U.S. stock market's upward trend since early 2023. The primary cause of the first three corrections was liquidity shocks, including the Silicon Valley Bank incident in March 2023, Treasury issuance in Q3 2023, and the unwinding of yen carry trades in August 2024. The latter three corrections resulted from liquidity constraints compounded by exogenous shocks such as macroeconomic disturbances, tariffs, and geopolitical tensions. Nevertheless, as the AI industry remains on an upward trajectory, the market's bullish direction has remained unchanged.

Therefore,When judging the direction of tech stocks, the first principle remains the earnings cycle: corporate earnings serve as the numerator, while U.S. Treasury yields act as the denominator.When AI earnings continue to rise, higher U.S. Treasury yields typically only cause short-term volatility. A true 'double whammy' on both the numerator and denominator occurs only when AI earnings estimates are revised downward amidst rising interest rates.
How can this round of U.S. Treasury turmoil truly come to an end?
The market needs to see three signals.
First, pressure from U.S. Treasury supply gradually decreases.Nearly half of the Q3 issuance was completed in July, and supply disruptions are expected to ease from August to September. The Treasury's expansion of long-term bond buybacks can improve market liquidity to some extent, but its role is more oriented toward stabilizing the market and should not be equated with QE.
Second, Warsh restores policy credibility.The market does not necessarily demand an immediate dovish pivot from the Fed, but it requires clearer stances on inflation, conditions for rate hikes, and a framework for liquidity support. The upcoming Jackson Hole Annual Economic Symposium will serve as an important window for observation.
Third, and most critically, AI revalidates investment returns.If NVIDIA's earnings, cloud providers' capital expenditures, and large model revenues continue to exceed expectations, earnings growth will be capable of absorbing higher financing costs, and the suppressive effect of US Treasury yields on tech stocks will diminish.
Overall,This round of US Treasury turmoil appears more like a valuation shock triggered by rising term premiums rather than a systemic liquidity crisis.As long as the repo market, credit spreads, and bank reserves remain under control, and the AI earnings trend remains upward, US Treasuries are more likely just the trigger for a correction in US equities rather than the decisive factor ending the bull market.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments (6)
to post a comment
59
100