HBM shortages drive up chip prices: Is the memory supercycle continuing?
Analysis of SK Hynix's Major Share Buyback and Cancellation | Behind the Memory Sector Rebound, Cyclical Stocks Attempt to Reshape Valuation Logic ❣️
Last night, US stocks were boosted by news that the scale of long-term bond buybacks had doubled. The three major indices ended a three-day losing streak and rebounded, but the AI hardware sector remained under pressure: Lumentum and Coherent plummeted over 5% and 6%, respectively; SanDisk fell 3.5%, while Micron edged down 0.4%. SK Hynix opened 5% higher but retreated, ultimately closing with a slight gain of 0.4%.
Major post-market news: SK Hynix announced a KRW 40 trillion (approximately USD 28.6 billion) share buyback and cancellation of treasury stock, while committing to return at least 50% of its free cash flow to shareholders from 2025 to 2027. 💡
I. Why is the company able to allocate so much capital for buybacks now?
1. The current supercycle in AI memory has generated substantial profits. Operating profit in the second quarter reached KRW 60.5 trillion, with an operating margin as high as 76%. Net cash on hand stood at KRW 69.4 trillion, meaning this buyback will consume nearly 58% of its net cash reserves.
2. The company is simultaneously executing large-scale dividends and buybacks without reducing capacity investment. Capital expenditure for 2026 has been raised by 45% to KRW 40 trillion, with continued increased investment in HBM and advanced packaging.
In the capital-intensive memory industry, it is rare to see aggressive capacity expansion coinciding with significant shareholder returns, which demonstrates the company's strong self-sustaining cash flow capability.
II. Key Point: This is a buyback and cancellation, not a standard buyback
Standard buybacks often retain shares as treasury stock for equity incentives, offering limited benefit to existing shareholders. Cancellation, however, effectively reduces the share capital.
- This cancellation involves approximately 24.07 million shares, representing 3.3% of the total share capital, to be completed within three months. Assuming net profit remains unchanged, this will directly boost EPS by approximately 3.4%, while also driving up ROE, which is positive for valuation.
- This precisely offsets the equity dilution caused by the July follow-on offering of US-listed ADRs, not only neutralizing the 2.5% dilution but also achieving a net reduction in share capital, thereby protecting existing shareholders' interests.
This move was largely intended to soothe market anxiety regarding cyclical risks.
After hitting an all-time high in June, SK Hynix experienced a maximum drawdown of nearly 48%. The market is not questioning its current profitability but rather fearing a repeat of the old narrative: once the AI hype fades, companies may engage in aggressive capacity expansion again, replaying the cyclical tragedy of overcapacity and price wars. 🌟

3. Comparison with SanDisk's shareholder return plan
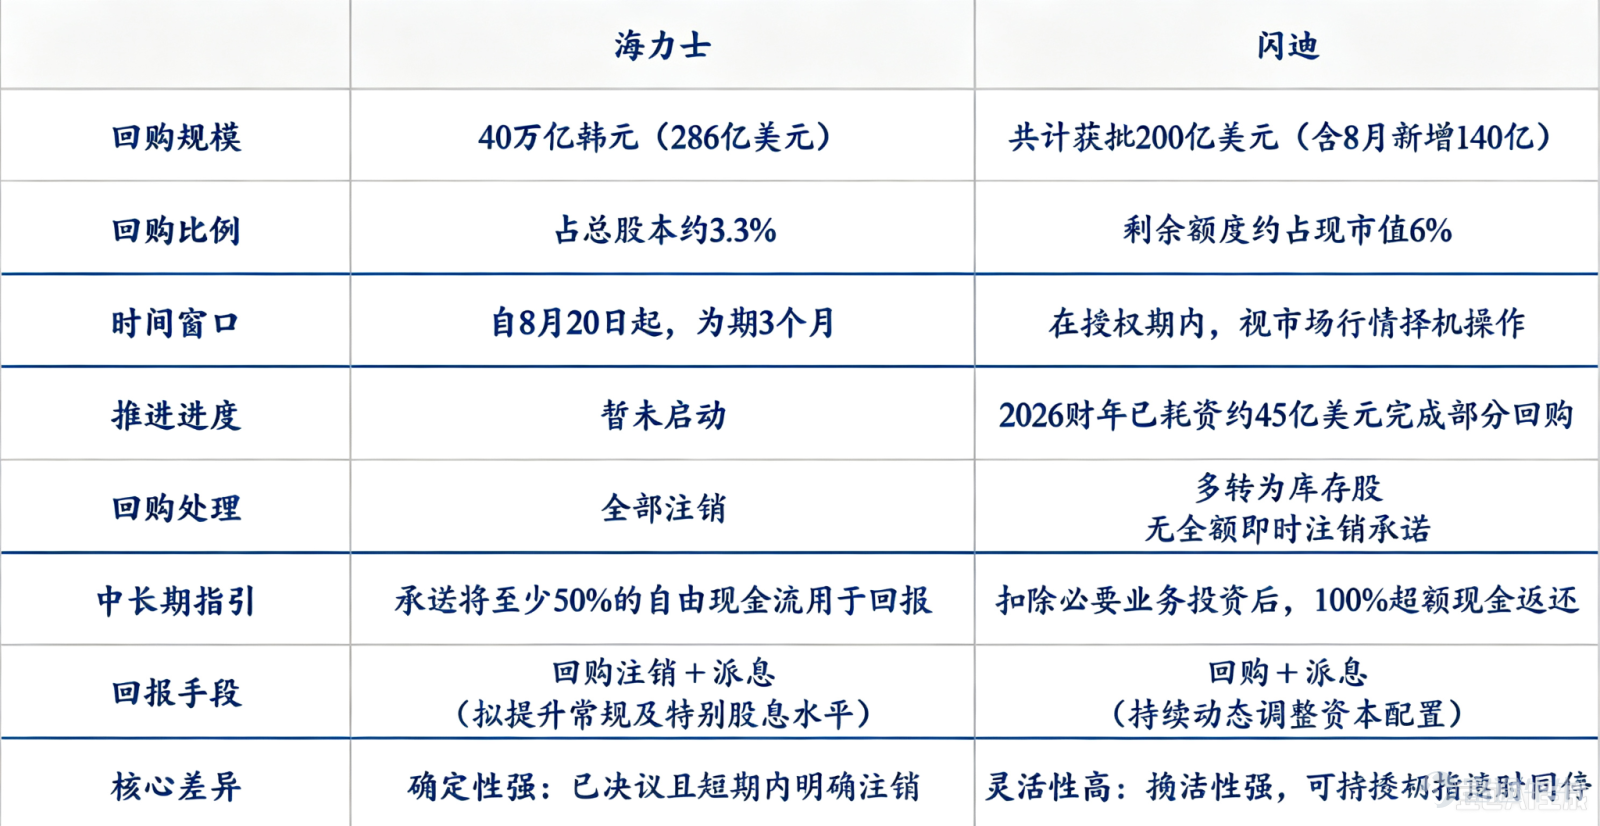
Both companies have announced substantial return plans, but there are significant differences in the details:
1. Execution certainty
SanDisk has authorized a $15.5 billion buyback program, which serves only as a theoretical ceiling; the actual amount repurchased depends on management's discretion, offering considerable flexibility.
SK Hynix has a mandatory cancellation plan approved by the Board of Directors for execution within three months, providing higher certainty of implementation.
2. Cash rules & share treatment
SanDisk: Prioritizes business investments first, then returns all remaining cash; there is no commitment yet to cancel the repurchased shares;
SK Hynix: Directly commits over 50% of free cash flow, with transparent rules; all repurchased shares will be canceled, directly reducing share capital.
4. The Core Intent Behind the Move 💎
The pace of memory price increases has already slowed, and the market is widely concerned that the cycle has peaked.
SK Hynix's maneuver is essentially an attempt to shift its market positioning: transforming from a purely cyclical stock driven by price speculation into an AI infrastructure asset capable of delivering stable cash flows.
Rather than spinning lengthy narratives about the AI industry, distributing actual cash to shareholders better proves the authenticity of profits and management's confidence in medium-to-long-term earnings. This also provides support for the volatile stock price and may even pressure peers like Samsung to follow suit, benefiting the entire memory sector.
However, blind optimism is unwarranted; three key risks should be noted:
1. Buybacks cannot reverse the cyclical turning point: If the industry is at the peak of its cycle, a downturn in the memory cycle will mean buybacks can only cushion the stock price, not reverse the downward trend. The core factors to watch remain HBM market share, spot DRAM prices, and the sustainability of cloud providers' capital expenditures.
2. Monitor actual implementation: Track the execution intensity of the buyback over the next three months, with a close eye on the Q3 report, to see whether the commitment to return 50% of free cash flow materializes as cash dividends.
3. New stock selection criteria: As the memory sector enters a phase focused on performance delivery and shareholder returns, prioritize companies with robust cash flows, disciplined capital expenditure, and a willingness to reward shareholders.
Information provided is for reference only and does not constitute investment advice
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comments
to post a comment
3