Hong Kong and US pharmaceutical stocks remain active; have you positioned your portfolio?
Review of 2Q26 Performance by Leading Overseas CDMOs: Global CDMO Recovery Accelerates
1. Since 2025, the global financing environment for innovative drugs has improved. Coupled with the advancement of late-stage clinical projects and the release of commercialization demand, the CDMO industry is gradually emerging from its trough, with overseas leaders showing signs of recovery. Lonza's revenue in 1H26 increased by 16% year-over-year, while its EBITDA margin continued to rise. ADC/bioconjugate CDMO services have become a key growth driver, indicating that the global CDMO industry has entered a new expansion cycle.
2. In terms of specific segments, emerging CDMO fields such as large molecules, ADCs, and TIDES (oligonucleotides and peptides) are experiencing significantly higher prosperity than traditional small-molecule businesses. The global CDMO competitive landscape is shifting. Overseas leaders are strengthening regional supply capabilities by acquiring or building local capacity in the US to meet multinational pharmaceutical companies' needs for supply chain security and a global dual-supply system. Wuxi Bio is actively advancing its global layout in the US, Europe, and Singapore. Wuxi Apptec is constructing a facility in Delaware, US, expected to begin production by the end of the year. Currently, Wuxi XDC's ADC manufacturing remains primarily in China, with Singapore as the focal point for its overseas expansion.
3. Since 2025, the market has gradually become desensitized to US policy risks, reducing the short-term impact of individual events on stock prices. However, from a medium-to-long-term perspective, US geopolitical and regulatory uncertainties remain significant constraints on the recovery of Chinese CXO companies. Future CXO competition will shift from the previous "China/Asia efficiency" model to comprehensive competition based on "Asia efficiency + local manufacturing in Europe and the US + global dual supply."
This article represents personal opinions only and does not constitute investment advice. Please assume all risks yourself.
I. Acceleration of Global CDMO Recovery
Referencing Lonza's performance, both small-molecule and large-molecule CDMOs globally have shown clear recovery and growth since 2025. Specifically, Lonza's revenue in 1H26 grew by 16% year-over-year, and its EBITDA margin increased by 4.4 percentage points year-over-year to 34.8%. The primary growth driver was the rapid expansion of its ADC/bioconjugate CDMO business.
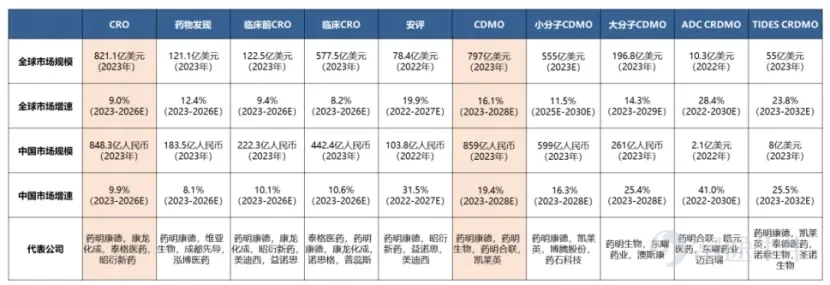
Since November 2025, I have been tracking the Wuxi Apptec group's CXO businesses: Wuxi Apptec (small molecules + peptides), Wuxi Bio (large molecules), and Wuxi XDC (ADCs). As shown in the chart below, emerging segments in the CDMO sector—such as large molecules, ADCs, and TIDES—are growing significantly faster than small molecules.
Chart 1: Market Size and CAGR of CXO Sub-segments

Source: Frost & Sullivan
Wuxi Apptec released its interim results on August 3, 2026, significantly exceeding market expectations: Wuxi Apptec: 1H26 Results Beat Expectations; Full-Year Guidance Raised
The TIDES business primarily benefited from increased outsourcing demand driven by the boom in GLP-1 drugs, with its high growth rate largely in line with expectations. The true surprise came from the high growth in small molecules (excluding TIDES). Excluding TIDES, small molecule D&M revenue reached RMB 14.99 billion in 1H26, a year-on-year increase of 73%. The market views small molecule business as a traditional, mature segment where overall drug sales growth is typically 5-10%. Even assuming continuous gains in market share, growth should ideally be around 1.5x the industry average.
In my view, the rapid growth in the small molecule business may mainly stem from: 1) an increased proportion of high-value complex molecules; and 2) incremental volume from Eli Lilly and Co's oral GLP-1 small molecule drug, Foundayo. However, simple linear extrapolation is not advisable, as the first half may have been influenced by concentrated demand due to one-time inventory stocking. Foundayo is still in the early stages of ramping up volume, and oral GLP-1 weight-loss drugs are attracting mostly new patients who have never used GLP-1 injectables for weight loss. Even in the US, the penetration rate of GLP-1 weight-loss drugs in the total addressable market is only around 8%, suggesting that the high prosperity in this sector is likely to persist in the coming years.
I believe that in the coming years, Wuxi Apptec's main growth drivers will continue to be its peptide TIDES business and select blockbuster oral small molecule drugs. Key leading indicators include sales volumes of Eli Lilly and Co's tirzepatide injections, as well as prescription and sales volume changes (year-over-year and quarter-over-quarter) for oral Foundayo.
The change in revenue structure at Polypeptide, a peptide CDMO company, along with its high growth rate since 2025, indirectly confirms the high prosperity in the peptide CDMO sector. In July 2026, Samsung Biologics announced its intention to acquire Polypeptide, primarily aiming to expand its CDMO capabilities from antibodies and ADCs to include peptide drugs such as GLP-1s. This move also leverages Polypeptide's technology, late-stage project pipeline, and global production network across Europe, the US, and India to accelerate its multi-technology platform and globalization strategy.
Wuxi Bio and Wuxi XDC will release their interim results on August 25 and August 24, respectively. You are welcome to register for the post-1H26 results NDR hosted by Wuxi XDC on our platform (August 31 at 4:00 PM).
In the large molecule CDMO sector, both Lonza and Samsung Biologics have shown accelerating growth trends. There are market concerns about whether Samsung Biologics will capture orders from Wuxi Bio after expanding capacity. Based on my research, Samsung's large-scale single-product automated manufacturing plants and global customer system do offer certain competitive advantages in areas such as monoclonal and bispecific antibodies. During the domestic CDMO capacity shortage in 2021-22, Samsung Biologics captured some CMO orders from multinational pharmaceutical companies through low-price competition. Customer shifts were reflected in adding suppliers, splitting orders, and reducing the weighting of original suppliers.
Meanwhile, in 2024-25, Samsung Biologics also indirectly benefited from multinational pharmaceutical companies' geopolitical hedging driven by the Biosecure Act, leading to rapid growth in revenue and backlog. According to the latest data, Samsung Biologics' quotes for similar projects are approximately 20% higher than those of domestic CDMOs.The author believes that in the short term, capacity in the large-molecule CDMO sector remains tight, making price competition unlikely.
In the ADC field, R&D pipelines continue to show strong growth. For instance, Wuxi XDC's continuously growing backlog reflects robust demand for outsourced R&D and manufacturing. This aligns with market consensus. However, there is significant divergence in the certainty of these R&D projects ultimately converting into commercial products. The recent positive progress of Merck & Co/Kelun Biotech's sac-TMT provides positive validation, while Daiichi Sankyo's downward revision of expectations for certain ADC projects indicates that not all ADC projects will successfully realize their expected commercial value.Key indicators for investors will include the clinical progress of potential blockbuster ADC drugs, the visibility and growth rate of late-stage PPQ batches, as well as the number and scale of CMO projects.
The high activity level in ADC R&D pipelines has already been priced in by the market, but there is still disagreement on whether the late-stage ADC sector can mass-produce blockbuster drugs. This may also explain why Wuxi XDC's stock price performance lagged behind its global CXO peers this year.
Chart 2: Year-to-date percentage change in stock prices of comparable global CXO companies

Source: Frost & Sullivan
After Trump returns to power in 2025, policies such as tariffs, reshoring of drug manufacturing, and tax incentives will further push multinational pharmaceutical companies' previous global expansion towards 'US reshoring.' Meanwhile, it can be observed that overseas CDMOs such as Lonza, Samsung Biologics, and Fujifilm have either acquired US factories or plan to build facilities in the US to meet local capacity needs and stay close to customers. Wuxi Bio has clearly advanced its global layout in the US, Europe, and Singapore, while Wuxi Apptec is building a facility in Delaware, US, expected to start production by the end of the year. Wuxi XDC's ADC factories are currently mainly located in China, with Singapore being the focus of its overseas expansion.
Since 2025, as the market has repeatedly博弈 (game/negotiate) over US policy risks, investors have gradually become desensitized to geopolitical disruptions, and the marginal impact of single policy events on stock prices has significantly weakened. However, from a medium-to-long-term perspective, US geopolitical and regulatory uncertainties have not been fully cleared from fundamental pricing. In other words, the 'risk premium' for policy risks still exists, with its impact shifting more from short-term earnings expectations to a continuous suppression of valuation ceilings. The author believes that while CXOs previously competed on 'China/Asia efficiency,' future competition will be based on 'Asia efficiency + US/Europe local manufacturing + global dual supply.'
Regarding valuation, compared to overseas CXO peers such as Lonza and Samsung Biologics, Chinese CXOs generally offer better value. Considering growth potential, Wuxi Apptec, Wuxi XDC, and Wuxi Bio appear more attractive. Even after the stock price recovery since 2025, the valuations of the Wuxi-series CXOs have not returned to their five-year average levels. This partly reflects that as these companies mature in their growth stages, the market has not assigned them the high growth premiums of the past.
Figure 3: Valuation Table of Comparable Global CXO Companies

Note: Net profit attributable to shareholders for A-share and Hong Kong-listed CXO companies is denominated in CNY, while for foreign stocks it is in USD.
Source: Consensus forecasts from Wind for A-shares and H-shares; consensus forecasts from Seeking Alpha for foreign stocks; company-disclosed consensus for Lonza. Compiled by the author.
II. Lonza: Significant Growth in ADC/Bioconjugate CDMO Business with Higher Profitability
Revenue reached CHF 3.4 billion in 1H26, up 16% year-over-year; Core EBITDA stood at CHF 1.2 billion, rising 27% year-over-year. The Core EBITDA margin was 34.8%, an increase of 4.4 percentage points year-over-year. The margin expansion was driven by efficient operational execution, operating leverage from the maturation of new capacity ramp-ups, optimization of product mix, and favorable effects from the phased settlement cycle of orders.
Note: 1 Swiss Franc ≈ 8.1 RMB
By segment:
Integrated Biologics (Large-molecule Biologic CDMO):Revenue amounted to CHF 1.87 billion in 1H26, a 10.0% year-over-year increase. Revenue growth was primarily driven by the gradual ramp-up of previously added capacity and expansion projects, along with steady growth in the existing base business. Revenue recognition at the Vacaville facility was front-loaded in the first half; however, the company expects full-year 2026 revenue to remain largely flat compared to 2025, thus limiting its incremental contribution to full-year year-over-year growth.
Advanced Synthesis (Small-molecule Chemical Drugs + ADC/Bioconjugate CDMO):Revenue in 1H26 reached CHF 830 million, a 28% year-on-year increase. The strong growth was driven by improved asset utilization and a low base for ADC/bioconjugates last year. The segment's core EBITDA margin expanded by 6.8 percentage points to 48%, supported by product mix optimization and increased operating leverage.
Specialty Formulations (cell and gene therapy, microbial fermentation, mRNA, and analytical tools for life sciences):Revenue in 1H26 reached CHF 550 million, up 23% year-on-year, reflecting a low base from the previous year.
Chart 4: Lonza has transformed into a pure-play CDMO over the past two years by divesting non-core businesses.

Source: Lonza earnings presentation
The company raised its full-year core EBITDA margin guidance to 33-34% (previously >32%), while maintaining the full-year revenue growth forecast at 11-12%.
During the 1H26 earnings call, an analyst asked whether the 16% revenue growth in 1H26, coupled with the unchanged full-year revenue growth guidance of 11-12%, implied weaker revenue growth in 2H26 and beyond. Management responded that this was primarily due to the timing of revenue recognition. 1H25 had a low base, while 2H26 faces planned shutdowns for upgrades at the Vacaville facility and a higher year-on-year comparison base. In our view, ...
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more
Comments
to post a comment