Zhipu's earnings surge as AI commercialization breaks new ground! What are the opportunities?
[Comment to Win Points] Alibaba, Kuaishou, and Baidu Take the Stage: Are Large AI Models Sparking a "Value Verification" Storm?
Earnings season for tech and internet stocks is heating up again! This week,Alibaba, Kuaishou, and Baiduwill sequentially release their results for the new quarter. In the past, discussions around AI focused on large model benchmarks and computing power races, but market sentiment has clearly shifted. Instead of asking "who can train a stronger model," investors are now more concerned with whether the substantial capital invested in AI can translate into tangible financial returns.
Within this theme of "AI Value Verification," Alibaba, Kuaishou, and Baidu are undoubtedly the three most representative companies, yet their AI narratives differ significantly.Alibabaleans more towards infrastructure output via "AI + Cloud",Kuaishoubets on productivity tools through "AI + Content",Baiduwhile focusing on ecosystem restructuring via "AI + Search." For investors, what truly matters may not be which model has more parameters, but whether AI can genuinely penetrate their respective business scenarios and become a solid new pillar on the income statement.
Alibaba: Can AI Cloud Support the "Second Growth Curve"?
$BABA-W (09988.HK)$$Alibaba (BABA.US)$ Will announce its Q1 FY2027 financial results on August 20 (Beijing Time).Institutions expect Alibaba to report revenue of RMB 268.343 billion for Q1 FY2027, an 8.35% year-over-year increase; EPS is expected to be RMB 1.475, a 34.44% year-over-year decrease.
Alibaba Cloud's AI-related product revenue has maintained triple-digit growth over the past few quarters, becoming the core engine driving cloud business growth. Alibaba's strategic investments in AI infrastructure are shifting from "building pipelines" to "securing orders." However, significant investments in strategic businesses such as Taobao Instant Shopping are putting clear pressure on short-term profits. The market will next observe whether the high-margin growth of "AI + Cloud" can continue to offset the heavy investments in e-commerce and local services, thereby improving the group's overall profitability structure. After all, once the scale effects of AI Cloud are realized, the rate of marginal cost reduction could far exceed that of traditional businesses.
Kuaishou: Watching how Kling AI supports new narratives beyond "live streaming e-commerce"
$KUAISHOU-W (01024.HK)$ Will release its Q2 FY2026 earnings report on August 19 (Beijing Time).Institutions expect Kuaishou to report revenue of RMB 35.491 billion for Q2 FY2026, a 1.27% year-over-year increase; expected EPS is RMB 0.697, a 38.33% year-over-year decrease.
Against the backdrop of slowing growth in live streaming e-commerce and peaking user growth, Kuaishou's Kling AI has emerged as a new variable attracting market attention. Kling AI has already established an independent commercialization path, with its AI video generation services for creators and enterprises rapidly scaling up. However, behind this high growth, the massive computing power costs for AI training and inference are eroding profits. The essence of Kuaishou's AI story is finding a new balance between "monetizing traffic" and "monetizing technology." What investors really need to watch is not just how fast Kling AI can grow, but whether it can gradually improve its unit economics while maintaining high-speed growth, moving from "trading losses for scale" to "unlocking scale effects."
Baidu: Watching to see if AI Cloud and AI Agents can create a new growth engine
$BIDU-W (09888.HK)$$Baidu (BIDU.US)$ Will release its Q2 2026 financial report on August 18 (Beijing Time).Institutions expect Baidu to achieve revenue of RMB 31.986 billion in Q2 2026, a year-on-year decrease of 2.22%; EPS is expected to be RMB 1.15, a year-on-year decrease of 54.72%.
Compared to Alibaba and Kuaishou, Baidu's AI entry point more precisely targets "reconstructing search and cloud computing with AI." Baidu Intelligent Cloud has maintained significant growth recently, while AI-native applications and the AI agent ecosystem are accelerating their implementation. The market's core focus on Baidu lies in whether AI can truly activate a new growth engine beyond search advertising. If AI Cloud growth continues to accelerate and AI agents convert search traffic into higher-value commercial activities, Baidu could see a market re-rating. After all, search remains one of the most core traffic gateways on the internet, and the potential for AI-transformed search is far greater than that of traditional advertising models.
So the question arises: Among Alibaba, Kuaishou, and Baidu, which one represents the true main theme for validating AI value?
🔎For this round of tech stock earnings reports, the focus is on three key questions:
First, can AI investment shift from being a "cost item" to a "profit contributor"?
Over the past few quarters, all three companies have heavily invested in AI infrastructure without exception. Alibaba has continued to increase capital expenditure on AI Cloud, Kuaishou has ramped up investment in Kling AI computing power, and Baidu has sustained its investment in AI Cloud and AI agents. However, for investors, the true litmus test is whether AI investments can translate into sustainable profit contributions. Alibaba Cloud's AI revenue share continues to rise, Kuaishou's commercialization is accelerating, and Baidu's AI Cloud revenue is growing steadily. Whether these trends can persist will determine if AI businesses can transition from a "long-term narrative" to "current performance."
Second, can core businesses stabilize the foundation to provide a safety cushion for AI investments?
Alibaba's China Commerce Customer Management Revenue (CMR) continues to grow, Kuaishou's live streaming and advertising businesses face pressure on growth rates, and Baidu's search advertising still needs to navigate macroeconomic challenges. During this phase of massive AI investment, the cash-generating ability of core businesses directly determines how far a company can run in the AI race. If core business revenue is stable and cash flow is healthy, the market is willing to give AI initiatives more patience; conversely, if the foundation weakens, AI spending could become a "bleeding point" that drags down overall valuation.
Third, regarding their respective AI differentiation strategies, who can establish a true competitive moat?
Alibaba is pursuing an "AI infrastructure platformization" strategy, building its moat through scale and technological leadership; Kuaishou is following an "AI content productivity tool" path, monetizing directly through products like Kling AI; Baidu is adopting an "AI-native application ecosystem" approach, reconstructing traffic value through search + intelligent agents. While none of these three paths is inherently superior, the one that first validates its business model and achieves scalable profitability will gain the upper hand in the next phase of AI competition.
What should we really focus on this time?This time, the market may be looking beyond the short-term financial figures of Alibaba, Kuaishou, and Baidu, focusing instead on whether tech internet stocks can truly realize AI monetization:
✅ Can AI-related revenue continue to grow at a high rate while gradually improving profit margins?
✅ Can core businesses such as e-commerce, advertising, and live streaming remain stable and continue to provide financial support for AI development?
✅ Who can faster establish a differentiated moat: Alibaba Cloud's AI scale effects, the commercialization speed of Kling AI, or the ecosystem expansion of Baidu AI Cloud?
✅ Will the market's valuation logic for AI shift from "looking at input" to "looking at output"?
If the AI rally in the first half of the year was driven by "who has models," then the AI narrative in the second half is shifting to "who can monetize." Tech internet stocks are no longer just the "shovel sellers" providing AI computing power; they are becoming the "ultimate scenarios" for AI application deployment—but the prerequisite is that AI must truly grow into a new pillar of profitability on the income statement.
🏆 Event: Bull Circle Opinion King ✨
Alibaba, Kuaishou, and Baidu have all released their financial reports. Which company do you see as having the most promising prospects for validating its AI value?
Welcome to share your views in the comments section:
1️⃣ Among Alibaba, Kuaishou, and Baidu, whose AI commercialization path do you favor the most?
2️⃣ During this period of heavy AI investment, do you prioritize "revenue growth rate" or "profit quality"?
3️⃣ Which model do you believe has a higher ceiling: the scale effects of AI cloud, the commercialization of AI content tools, or the ecosystem restructuring of AI search?
4️⃣ If the AI rally in tech stocks continues, which company offers greater upside elasticity?
Now, it's time to hear from our fellow investors! Share your views in the comments section and participate in the interaction to win point rewards! 👇👇Share your thoughts in the comments below:
✅ At least 30 words ✅ Original viewpoint ✅ Complies with community guidelines
Meet the requirements to share in the 30,000 points prize pool!
Click to reserve:
Note: All activities above will end at 16:00 (Beijing Time) on August 20; rewards will be distributed uniformly after the conclusion of this earnings season.
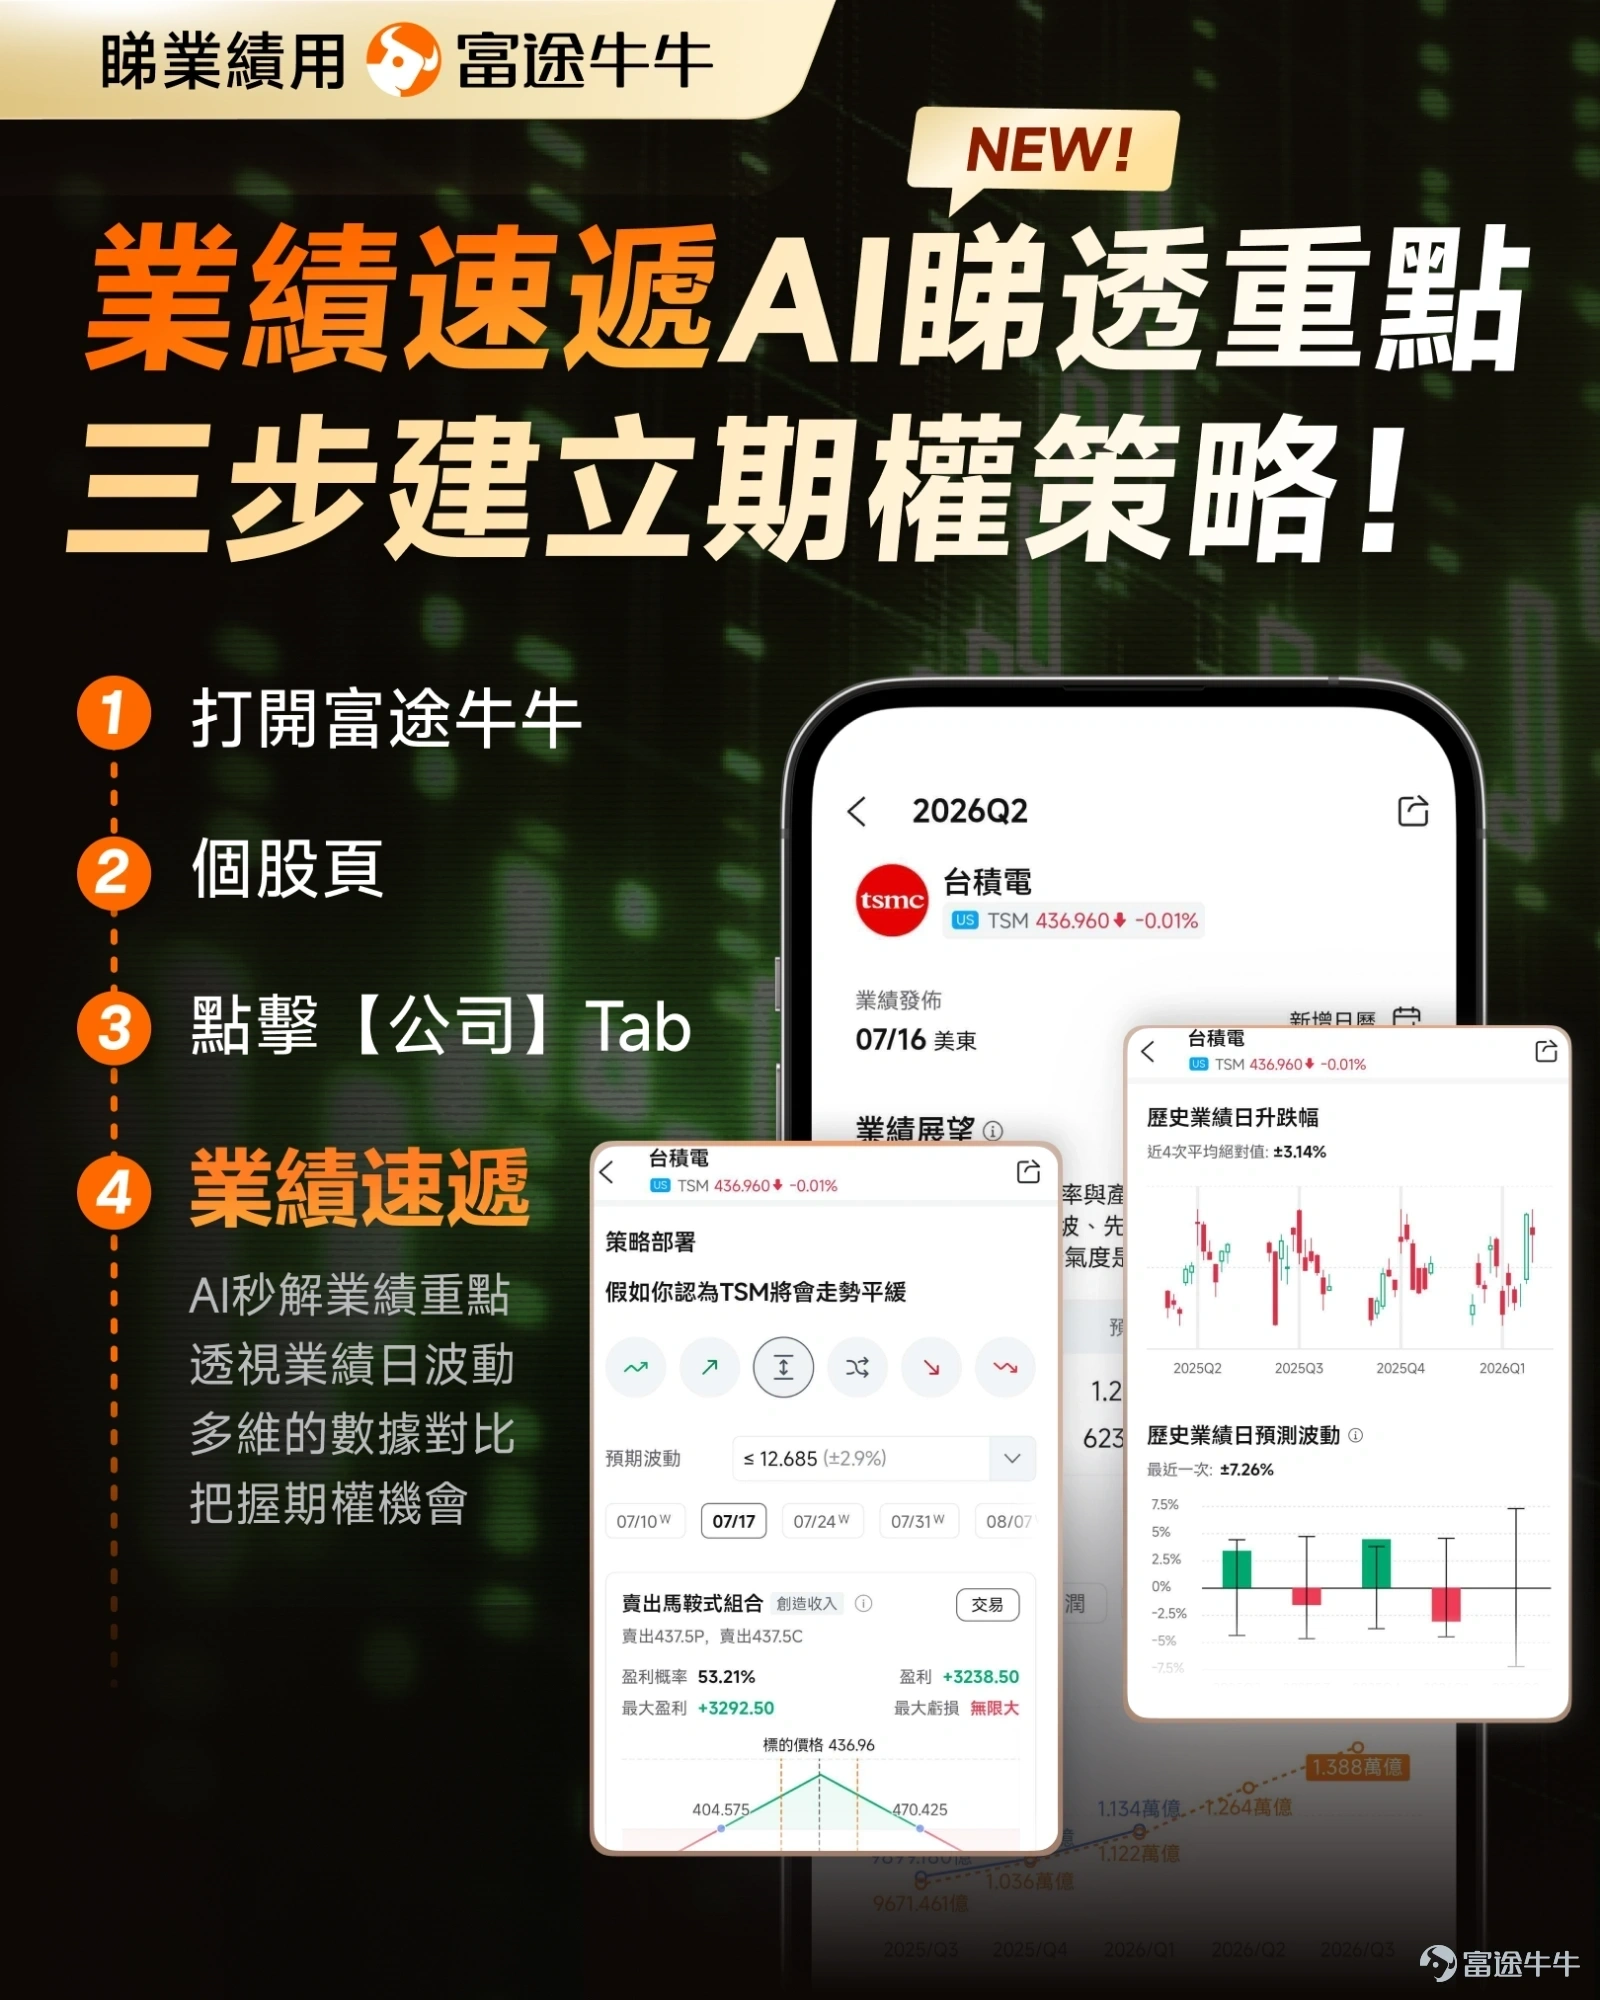
Click to reserve:‘Earnings Express’ has been fully upgraded—with three key features to help you get ahead during earnings season!
 Futubull AI Get instant answers to your questions, use intelligent stock selection to target promising upward momentum, and analyze your holdings to seize opportunities and avoid risks!

Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comments (69)
to post a comment
24
11