Non-farm payrolls significantly exceeded expectations; will CPI trigger a rate hike in September?
Gaozhan Weekly Rate Analysis | PPI Cools, Oil Prices Surge, Curve Bear-Steepens: Why Are Rate Hike Expectations Receding Faster?
Issue No. 202622
In last week’s column, we unpackedNon-farm payrolls came in much weaker than expectedHow to reverseinterest rate hikeexpectations, andFed Chair Warsh's passive tighteningThe logic behind the strategy facing its first data test. This issue will further analyze on this basisPPIHow the dual cooling of retail data acceleratesThe ebbing tide of rate hikes, as well as soaring oil prices and the curvebear steepeningthepricing paradox。
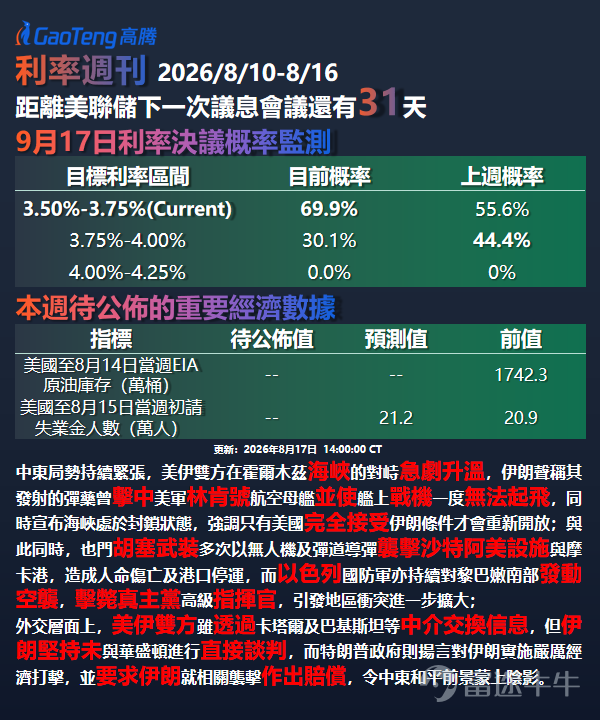
last weekwithin which U.S. JulyPPIgrowth slowing more than expected,retail salesunexpectedly declined in Septemberinterest rate hikeProbability fell from44.4%plummeted to30.1%。
Meanwhile, $Brent Last Day Financial Futures (DEC6) (BZmain.US)$ surged6.97%to$84.21, $U.S. 10-Year Treasury Notes Yield (US10Y.BD)$ upside to4.698%—rising oil prices andthe ebbing tide of rate hikescoexist, with the curve showing a typicalbear steepeningpattern.
This article will systematically analyze the core issues of this period from three dimensions: data shocks, curve patterns,the Bank of Japan's rate hikeaccelerationPricing logic。
▌ FedWatch Data Snapshot
CME FedWatch(As ofAugust 16) shows that until the nextFOMCWith 31 days remaining until the meeting, the probability of holding interest rates steady has receded from nearly 50% a week ago to less than 30%.With 31 days remaining until the meeting, the probability of holding interest rates steady has receded from nearly 50% a week ago to less than 30%.With 31 days remaining until the meeting, the probability of holding interest rates steady has receded from nearly 50% a week ago to less than 30%.3.50%-3.75%Probability is69.9%,interest rate hiketo3.75%-4.00%Probability is30.1%。
With 31 days remaining until the meeting, the probability of holding interest rates steady has receded from nearly 50% a week ago to less than 30%.August 7),interest rate hikeWith 31 days remaining until the meeting, the probability of holding interest rates steady has receded from nearly 50% a week ago to less than 30%.44.4%—just seven trading daysinterest rate hikeWith 31 days remaining until the meeting, the probability of holding interest rates steady has receded from nearly 50% a week ago to less than 30%.
The drivers were July's unexpectedly slower-than-expected growth andPPIThe drivers were July's unexpectedly slower-than-expected growth andan unexpected decline in retail sales, leading to a significant drop in short-end yields.an unexpected decline in retail sales, leading to a significant drop in short-end yields.
▌ Cooling PPI and retail sales accelerate the retreat of rate hikes
JulyCPIFully in line with expectations,PPIGrowth slowed more than expected, traders lowered Septemberinterest rate hikeProbability fell from48%consecutive cuts to32%。
Subsequentlyretail salesunexpectedly declined, traders further reduced bets on2027more than one hike before mid-terminterest rate hike.
Traders have no longer fully priced in this year'sinterest rate hikeScenario—Rate hike expectations have been fully priced inat a pace far exceeding previous data windows.
Goldman SachsIt is expected thatThe Federal Reserve in 2026is expected to keep interest rates unchanged throughout the year,CITIC Securitiesand still forecasts for the full yearHold position and take no action, a view shared by multiple institutions,that inflation is coolingtrend.
▌ Fed Dynamics: Waller Reduces Transparency as Hawk-Dove Standoff Intensifies
WallerSigned an ethics agreement to complete the divestiture of financial assets, while it was also revealed that they are considering reducing the frequency of rate-setting meetings and cutting backPreliminary Guidance。
This move wasWall Streetwarned could come at a cost—reduced communication will compress the market's ability to anchor expectations forpolicy pathinterest rates.
US President Trumppublicly confirmed frequent calls withWallerthe Fed Chair; White House officials stated this does not impede independence, but the shadow of political interference continues to expand.
▌ Focus of the Hawk-Dove Debate
hawkish:Cleveland Fed President MesterReiterated that action must be taken nowinterest rate hike, citing concerns about an overheating economy;Boston Fed President Collinswarned that a Septemberinterest rate hikerate hike may be imminent. The twohawkishofficials' stances remain unshaken by cooling data, but market pricing has diverged from their views.
dovish:Chicago Fed President Goolsbeebelievesinflationnoted slight improvements in data and expressed hope for continued progress on prices. His remarksprovide marginal support at the official level for the ebbing tide of rate hikes.
Centrists:Richmond Fed President Barkinstatedinterest rate hikeFor various reasons, the US economy remains resilient.Waller reductionPreliminary Guidancemakingthe pricing implications for centristseven more ambiguous.
▌ Key Data: July PPI and Retail Sales
According toBLSandUS Department of Commercedata,PPIthe slowdown exceeded expectations, traders lowered Septemberinterest rate hikeProbability fell from38%to32%。
Retail salesunexpectedly declined, traders reduced their bets on2027the mid-term periodinterest rate hikemore than once.
Pricing implications: Traders are no longer fully pricing in this year'sinterest rate hikescenario; the decline in short-end yields reflectsthe clearing of rate hike expectations。
▌ Yield Curve: Bear Steepener Returns
last weekShort end down, long end up — $U.S. 1-Year Treasury Bills Yield (US12M.BD)$ Closed at3.978%(-0.67%), $U.S. 3-Year Treasury Notes Yield (US3Y.BD)$ Closed at4.253%(-0.27%), $U.S. 5-Year Treasury Notes Yield (US5Y.BD)$ Closed at4.364%(+0.20%), $U.S. 10-Year Treasury Notes Yield (US10Y.BD)$ Closed at4.698%(+1.05%), $U.S. 30-Year Treasury Bonds Yield (US30Y.BD)$ Closed at5.260%(+1.10%)。
The short end reflectsinterest rate hikeExpectations of easing, while the long end is pricing in the impact of rising oil prices,term premiumexpansion and concerns over fiscal sustainability.
Key yield spreadsThe widening reflects the market's repricing of long-endinflationrisks, which deviates significantly from officials'hawkishstatements.
▌ Historical perspective
October 2023Soaring oil prices coupled with weakening economic data,US Treasuriesthe curve similarly showedbear steepening,the 10-yearyieldsupply shocksbreaking below 5%. At that time,interest rate hikethe cycle was nearing its end, and the long-end rally reversed after lasting about six weeks.
▌ Scenario Analysis
Scenario 1 (SeptemberHold position and take no action):interest rate hikeThe probability further receded toLess than 25%, with the short end catching up on the decline, and the curvebear steepeningdeepens,Goldbenefiting fromreal interest ratesPullback.
Scenario 2 (Septemberinterest rate hike): Short-end rates surged, curvebull flattenerinversion,Goldand pressuring equities.
Currently leaning towards Scenario 1, but a sustained rise in oil prices could reverseinflationexpectations.
▌ Market Sentiment Snapshot
interest rate hikeExpectations coexist with rising oil prices, with the marketpricing cooling inflationandsupply shocksbetweendivergence.Short-end pricingsignals the end of rate hikes.Long-end pricingSticky inflation— Investors' confidence inpolicy pathcontinues to waver.
▌ Other Major Central Bank Developments
People's Bank of China: The Q2 monetary policy report maintains a moderately accommodative tone, with consecutive weeks of no net liquidity injection and the launch oftrillion yuan in outright reverse repos. In July, gold holdings increased by19.9 tonsto76.08 million ounces, marking the highest monthly increase since the resumption of gold purchases.
Bank of Japan: The government and the central bank regarding recentinterest rate hikeConsensus reached, probability of tightening in September hits74%。Bank of Japan Governor Kazuo Uedahinted at Septemberinterest rate hikeprompting joint US-Japan intervention,US-Japan interest rate differentialExpectations for narrowing have strengthened.
Reserve Bank of Australia: holds interest rates4.35%unchanged,RBA Governor Michele Bullockstatedinflationupside risks remain.RBA Deputy Governor Kentbelieves policy is already restrictive, with limited room for furtherinterest rate hiketightening.
▌ Market Reaction: Oil prices surge while rate hike expectations fade
Brent crudesurges to6.97%to$84.21, $Crude Oil Futures (OCT6) (CLmain.US)$ Rising5.72%to$81.49, $Gold Futures (DEC6) (GCmain.US)$ slight gain0.70%to$4,432.0。
Rising oil prices should have reinforcedinterest rate hikeexpectations, but the market priced it in assupply shocksrather than overheated demand—namely,term premiumexpansion rather than an upward revision to the policy rate path.
Goldlimited gains reflect the suppression from rising long-endreal interest ratesyields.
US TreasuriesThe coexistence of short-end declines and long-end increases highlights the curve'sbear steepeningPricingsupply shocksanddual logic of receding rate hikes.
▌ Note at the End
Core Highlights of This IssuePricing logicisPPIThe cooling in retail sales is acceleratingas the tide of rate hikes recedes,the yield curvebear steepeningreveals a divergence between short-end and long-endpricing.。
Investors should closely monitor the remarks at the late-AugustJackson Holeannual symposiumWallerand theSeptember FOMCmeeting—ifinflationData remains moderately soft,interest rate hikeprobability will compress toBelow 20%; if oil prices break throughUSD 90,supply shocksor reverseinflationexpectations.
Bank of JapanSeptemberinterest rate hikeConstituting additionalcross-assetvariables.
$GaoTeng WeInvest Money Market Fund (HK0000478930.MF)$ $GaoTeng WeValue USD Money Market Fund (HK0000584752.MF)$ $GaoTeng WeFund-GaoTeng Asian Income Fund (HK0000447943.MF)$ $Hang Seng Index (800000.HK)$ $Hang Seng TECH Index (800700.HK)$ $Dow Jones Industrial Average (.DJI.US)$ $S&P 500 Index (.SPX.US)$ $Nasdaq Composite Index (.IXIC.US)$ $USD (USDindex.FX)$
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comments
to post a comment
3
1