
US CPI data released Wednesday! Combined with major Hong Kong stock earnings reports, what should yo
Market Outlook | Rate hike narrative cools down, AI investment thesis becomes increasingly solid
This week's market outlook is out; feel free to book a session for deeper insightsLive at 4:30 PM, face-to-face online consultation:

Guiding you through this week's strategies for the US and Hong Kong markets:
CPI cools off while retail sales stagnate: What's next for US rate hike expectations?
HK stock pricing shifts toward earnings realization; where do the recovery opportunities lie?
I. Macro Observation
1.1 International Macro: US July core CPI hits lowest level since 2021, easing pressure on Fed rate hikes
US July core CPI rose 0.215% month-over-month, with year-over-year growth slowing to 2.478%; excluding months where data was artificially depressed due to missing figures from government shutdowns,This is the lowest year-on-year growth rate for core CPI since 2021.Breakdown details were generally moderate: core goods prices rose slightly, rent and owners' equivalent rent (OER) saw a slight increase in growth, while service prices showed mixed movements.
The year-on-year increase in overall CPI for July narrowed to3.4%, with a month-on-month increase of0.1%, with no signs in the data indicating a resurgence of inflationary pressures,which is insufficient to support a Fed rate hike.Market focus remains on the extent to which rising energy costs are transmitted to core inflation: airfare, the component most sensitive to energy price increases within core inflation, rose 2.2% in July; other service prices diverged, with healthcare services showing slight strength, while demand for leisure and personal services remained weak; notably, the recent sharp decline in motor vehicle insurance slowed as expected, falling 0.3% month-on-month in July.
US PPI was flat month-on-month in July, with the year-over-year rate falling to4.7%, and core PPI year-over-year dropping to4.2%, primarily due to declining energy prices and a slowdown in service price growth. Prices for final demand goods fell 0.7% month-on-month in July, marking the second consecutive monthly decline following June's 1.4% drop. Within this, energy prices fell 3.1% and food prices dropped 0.9%, while goods prices excluding food and energy rose only 0.1%. Service prices continued to rise but at a slower pace; final demand service prices increased 0.2% month-on-month in July, down from 0.5% in June. Services excluding trade, transportation, and warehousing rose 0.6%, while transportation and warehousing services fell 1.8%, and trade services declined 0.1%.The widening divergence between CPI and PPI reflects pressure on corporate profit margins., Market expectations for Fed rate hikes remain unchanged; the urgency for short-term policy adjustments is limited, and future inflation trends will continue to depend on energy price movements.
Breakdown of US July Inflation
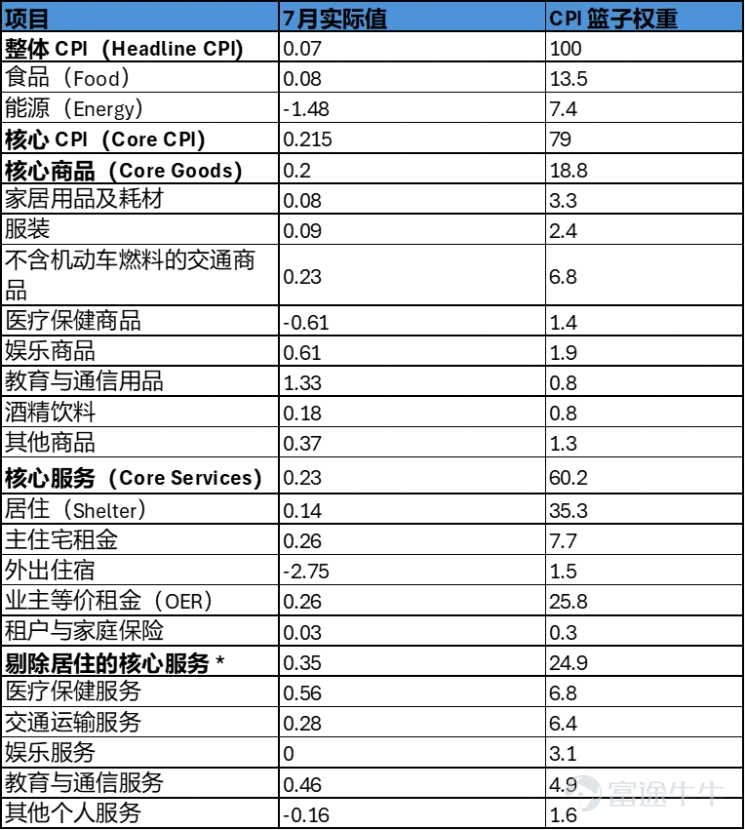
Source: BLS, 2026-08-16
Implied Probability of Fed Rate Hikes
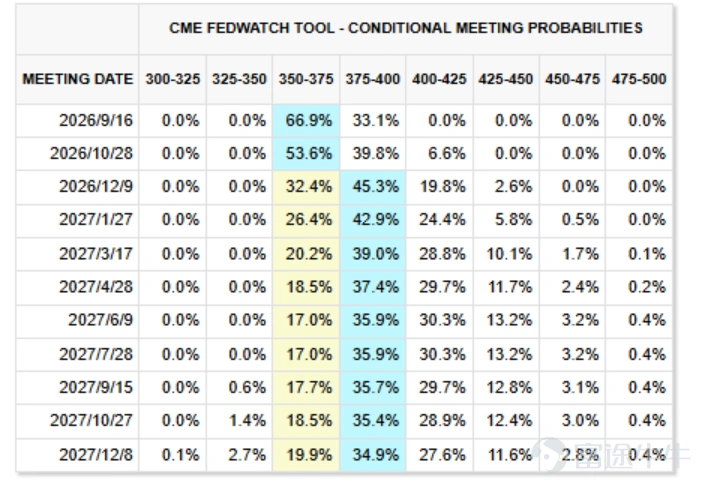
Source: CME FedWatch, 2026-08-16
1.2 Domestic Macro: Weak Social Financing and Credit + Low CPI; Counter-cyclical Adjustments May Intensify in Q4
Cumulative Incremental Social Financing in the First Seven Months of 2026RMB 22.25 trillion, a year-on-year decrease ofRMB 1.74 trillionAt the end of July, the outstanding stock of aggregate financing to the real economy (AFRE) grew by 7.4% year-on-year. M2 increased by 7.7% year-on-year, while M1 grew by 4%, narrowing the M2-M1 scissors difference to 3.7 percentage points, which was slightly below expectations overall. Credit to the real economy decreased by RMB 589.6 billion, a year-on-year increase in the decline of RMB 160 billion (the average monthly year-on-year incremental decrease for the first six months was -RMB 329.3 billion).Macro factors affecting credit include net repayments driven by debt resolution, household deleveraging, and substitution by direct financing. On August 12, the People's Bank of China (PBOC) released its Q2 Monetary Policy Implementation Report, stating that it will promptly plan and introduce practical and effective incremental policies in the next stage, and strengthen counter-cyclical adjustments.Corresponding policies are expected to be implemented in the fourth quarter.
In July 2026, the national Consumer Price Index (CPI) rose by 0.5% year-on-year and fell by 0.1% month-on-month; the Producer Price Index (PPI) rose by 3.5% year-on-year and fell by 0.7% month-on-month. The larger-than-expected month-on-month decline in PPI was mainly due to the lagged impact of the significant correction in global oil prices in June. Excluding the impact of oil prices, July's CPI inflation was 0.44% year-on-year, a slight decrease from 0.49% in June. For PPI inflation, excluding external drivers such as petroleum, non-ferrous metals, and chips, the year-on-year rate in July was 0.4%, flat compared to June.The mid-year Politburo meeting in July sent signals that Chinese policymakers may intensify efforts to stabilize growth in the second half of the year. It is expected that the PBOC will take corresponding actions to maintain exchange rate stability as expectations for external rate hikes ease, and a reserve requirement ratio (RRR) cut remains possible in the second half of the year.
July CPI
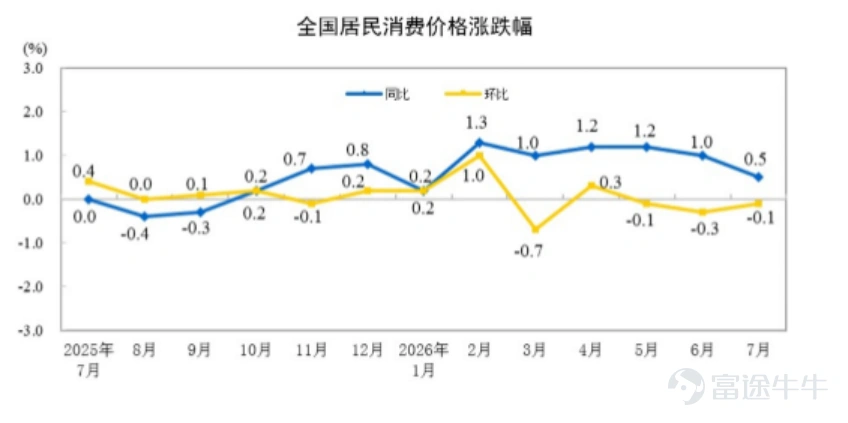
July PPI
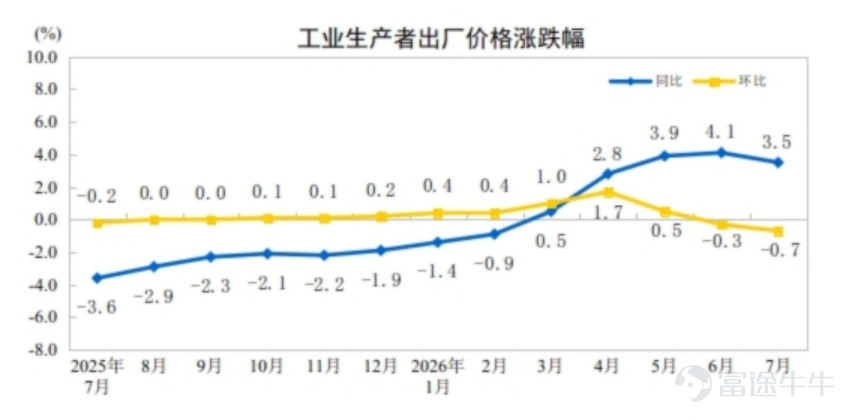
Source: National Bureau of Statistics of China, 2026-08-16
II. Market Views
2.1 U.S. Equity Market
Last Week's Review
The S&P 500 rose 0.36% for the week, hitting a new all-time high, while the Nasdaq gained 0.14%, but large-cap tech stocks stagnated. Market rotation signals were evident: early in the week, energy and cyclical sectors led gains due to oil price shocks; later in the week, oil prices fluctuated; subsequently, the market recovered further driven by mild July CPI and PPI data, increased probability of the Fed holding rates steady in September, and continued validation of strong earnings in the AI supply chain; however, on August 14, it dipped slightly as retail sales fell 0.6% month-over-month, triggering repricing concerns over slowing growth.
This Week's Outlook
💡 US stocks remain relatively strong among risk assets, maintaining a volatile but bullish bias, though internal rotation between high and low performers is accelerating. Sensitivity to tail risks from rate hikes remains high, but this concern is weakening directionally—July CPI met expectations, further easing inflation worries.Indices do not lack upward momentum, but stronger earnings breadth is needed to support elevated valuations, driven by semiconductors and tech leaders; after retail sales turned negative on August 14, the market immediately renewed concerns about growth,indicating extreme sensitivity to growth missing expectations at current levels. Before the September FOMC meeting, as long as inflation data does not deteriorate further and AI supply chain earnings continue to materialize,The core trend of US stocks remains relatively strong, but further gains will increasingly depend on earnings reports and the prosperity of specific sub-sectors. Semiconductors/memory chips are showing greater strength, optical communications are experiencing higher volatility, while software and certain platform stocks are undergoing share-based transformations.
Basis for Viewpoint
July CPI largely aligned with market expectations; the anticipated secondary rise in inflation did not materialize in July. Subsequently, the month-over-month flatness in July PPI continued to support the narrative that there is no urgent need for rate hikes in the short term. The yield on the 10-year US Treasury note fell from August 10,at 4.72% to 4.63% on the 13th,,which is beneficial for long-duration growth stocks.。
Performance in AI infrastructure and semiconductors continues to validate the thesis, with the profitability logic remaining intact: CoreWeave's Q2 revenue reached $2.58 billion, exceeding the expected $2.56 billion, with a backlog of approximately $104 billion; Super Micro Computer provided next-quarter revenue guidance of $14.5–15.5 billion, significantly higher than the market expectation of $11.99 billion; internal forecasts from Anthropic suggest revenue could reach $190–200 billion by 2028.
US retail sales declined month-over-month in July,0.6%significantly underperforming the expected +0.1% increase, marking the largest drop since May last year; core retail sales also fell 0.3% month-over-month. Traders further reduced bets on future rate hikes, but US stocks did not continue to surge as a result. Instead, the three major indices declined on August 14,indicating that while falling inflation and lower rate expectations benefit valuations, synchronized weakening in demand may impair earnings expectations.
S&P 500 forward 12-month P/E ratio: 21.2 (as of August 13)
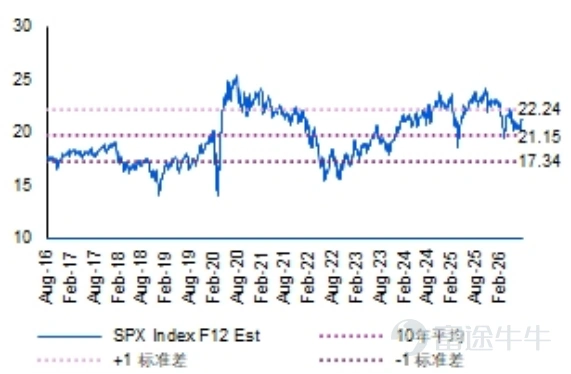
Source: Bloomberg, compiled by Futu Wealth Management
Key stock views: $Lumentum (LITE.US)$
Lumentum's FY26 Q4 results and guidance both exceeded expectations, entering the phase of earnings realization: Full-scale production of Spectrum-X confirms that CPO has moved from validation to ramp-up, with downstream mass production milestones achieved; NPO represents incremental growth rather than substitution, with clear delivery timelines starting from H2 2027.NPO expands TAM and smooths out the pace of CPO earnings realization., As long as ELS orders continue to expand, UHP laser revenue ramps up, more formal customer announcements for NPO are made, and OCS continues to exceed guidance in the coming quarters, there is still room for further upward revisions to the market's FY27-FY28 revenue and EPS estimates. The stock price has rebounded rapidly since early August, with the current forward 12-month P/E ratio at +1 standard deviation above its one-year historical average.
Basis for Viewpoint
FY26 Q4 Revenue$1.006 billion, EPS$3.23, gross margin50.4%, indicating early realization; midpoint of FY27 Q1 revenue guidance$1.25 billionMedian EPS$4.20, the company achieved its quarterly revenue target of $1.25 billion more than a quarter ahead of schedule, significantly exceeding consensus expectations.
On August 14, it was officially announced that NVIDIA Spectrum-X Ethernet Photonics would enter full mass production. Performance improvements include: a 4x reduction in the number of lasers, a 5x reduction in power consumption, and a 10x increase in MTBI. Management clarified that NPO is incremental to CPO,NPO-related shipments are expected to begin in Q4 2027, with volume ramping up in 2028, Total NPO volume expectations have been revised upward from approximately 30 million units to over 50 million units, with deliveries anchored to start in the second half of 2027.
The supply-demand gap for EML exceeds 30%. Management stated that 200G EML already accounts for over 25% of EML revenue and is expected to exceed 50% by mid-2027;The essence of the gross margin improvement lies in the stronger bargaining power of lasers as a bottleneck component.。
LITE forward 12-month valuation
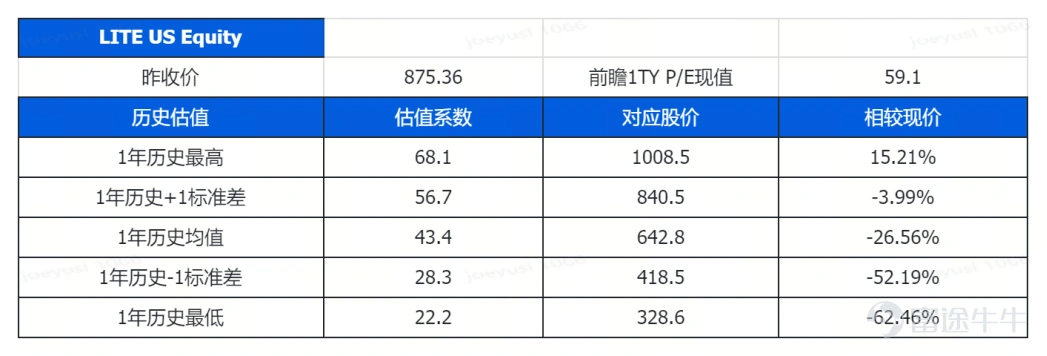
Source: Bloomberg, compiled by Futu Wealth Research
2.2 Hong Kong Stock Market
Last Week's Review
Hang Seng Index declined weekly2.15%, with average daily turnover ofHKD 237.2 billion, a decrease of approximately HKD 24 billion from the previous week, with average daily turnover shrinking further. The cumulative net inflow via Stock Connect was approximately HKD 89 million, a month-on-month decrease of about HKD 9.87 billion. HK stocks started high and ended low: early in the week, expectations of improved external liquidity, combined with the continued recovery in tech/internet and gold sectors, drove gains; mid-week, the index weakened amid pre-earnings caution and a pullback in southbound capital. As major companies released their interim results, the Hang Seng Tech Index faced pressure, while semiconductors remained relatively strong. The top three buys by southbound capital were MiniMax, Tencent, and SMIC.
This Week's Outlook
HK stocks are oscillating with a weak bias,after the valuation repair rally since late June hit resistance, the market has shifted to pricing based on earnings realization and the strength of capital flows., Structural opportunities remain concentrated in AI, semiconductors, and innovative drugs, with earnings performance becoming the core variable driving divergence. While the index consolidates and stock-specific earnings pricing strengthens, the main investment themes remain intact, though generating profits has become more difficult.The primary reason is that following the earlier rebound, the market has entered a phase of earnings realization and valuation rebalancing. Additionally, while the earnings reports from leaders like Tencent and JD.com had highlights, they also exposed divergences in capital expenditure, revenue growth rates, free cash flow, or growth trajectories. Nevertheless, the tech theme in HK stocks persists, with innovative drugs remaining active. Allocation should focus on sub-sectors with earnings beats and continued support from southbound capital.
Basis for Viewpoint
Southbound capital shifted from significant net inflows last week to nearly flat levels (with cumulative net inflows of only about HK$89 million), recording net outflows on three trading days.
Sectors such as Lenovo, SMIC, Hua Hong Semiconductor, Kingboard Laminates, and YOFC rotated in performance throughout the week,indicating that the tech style in Hong Kong stocks has not dissipated, but is now more biased towards the hard technology chain with verified prosperity.。 The second main theme is innovative drugs: following the weakening of non-farm payrolls data and the retreat in rate hike expectations, valuations for long-duration assets like innovative drugs and CXO have seen a repair.
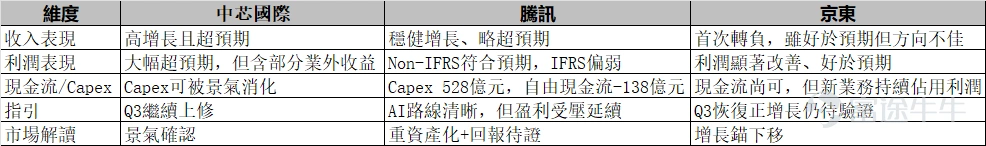
The pricing framework for the Hong Kong stock interim reporting season is"Earnings Realization + Quality Stratification": The market first looks at whether revenue guidance can prove that prosperity persists, secondly at whether profit improvements stem from operational quality, and thirdly at whether capital expenditures can be justified as high-return investments. Hence, SMIC outperformed Tencent, and Tencent outperformed JD.com—the former met the criteria of prosperity, volume-price dynamics, and guidance, while the latter two were constrained by high Capex suppressing cash flow and negative revenue growth suppressing valuations, respectively.
Breakdown of the core reasons for the divergent market reactions among the three companies
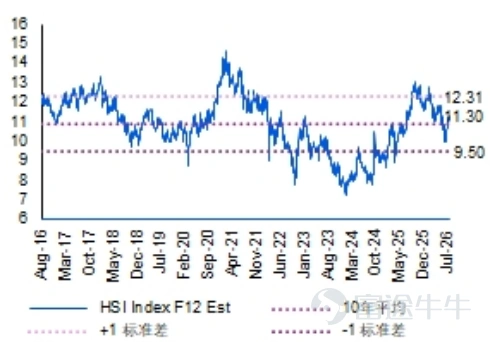
Hang Seng Index forward 12-month P/E ratio: 11.3 (as of August 14)
Source: Bloomberg, compiled by Futu Wealth Management
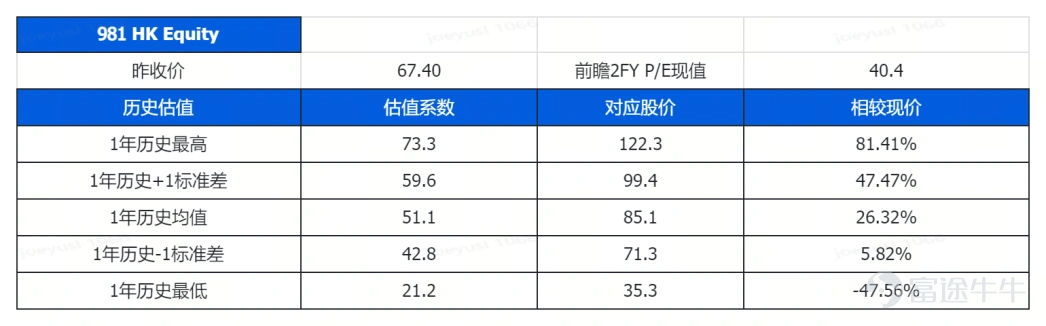
SMIC disclosed its Q2 earnings, with overall performance significantly exceeding market expectations: the company's quarterly revenue surpassedthe $3 billion mark for the first time,while profits demonstrated strong upward elasticity. Over the past year, the biggest divergence in market views on SMIC centered on the concern that high capital expenditures and high depreciation might suppress profit margins in the long term. The Q2 results show that while the company has not shaken off depreciation pressure,it has already gained the ability to navigate through the depreciation cycle. The improvement in gross margin this round has shifted from being driven by depreciation impacts to a profit model driven by pricing and product mix. From a valuation perspective, the company's forward P/E ratio for 2027 is around 40x, slightly below the historical average of the past two years,making the valuation attractive with considerable long-term growth potential.
Basis for Viewpoint
Capacity expansion did not lead to low utilization rates; instead, it validated the leading player's ability to absorb demand: the average capacity utilization rate for full-year 2025 reached 93.5%-95.7%; in Q1 2026, monthly capacity increased to 1.078 million wafers/month (converted to 8-inch standard logic), with utilization remaining at 93.1%; in Q2 2026, monthly capacity continued to rise to 1.0965 million wafers/month, with utilization further increasing to 93.7%; management expects that in Q3 2026, utilization will remain around 95%, even including new capacity.The company can shift capacity to more scarce processes through platform adjustments and order screening; meanwhile, order reshoring driven by the restructuring of the local supply chain is sufficient to cover the new supply.。
The AI-driven boost to SMIC is not limited to advanced computing chips themselves,but is also reflected in the broad-based demand for mature process nodes driven by the spillover from AI infrastructure.。 In Q1 2026, the ASP was approximately $938 per wafer, a quarter-on-quarter increase of about 2.5%; in Q2, the ASP rose to approximately $991 per wafer, a further quarter-on-quarter increase of about 5.7%. The company explicitly stated that new prices negotiated with customers earlier have been gradually implemented since the second quarter. The proportion of wafers sold at new prices will further increase in the third quarter, leading to a more significant contribution to revenue and gross margin.
SMIC Valuation
Source: Bloomberg, compiled by Futu Wealth Research
3. Key Focus This Week
August 17, China will release July data on total retail sales of consumer goods and value-added industrial output above designated size. The market expects year-on-year growth in total retail sales of consumer goods1.5%, with the previous figure at1%. Pressure from the high base effect of trade-in programs is easing, while service consumption and offline spending are recovering during the summer holiday season. The year-on-year growth rate of value-added industrial output above designated size is expected to decline from the previous 5.3% to 5%, mainly due to seasonal downturns and extreme weather conditions.
August 19Around this time, Unitree Robotics is expected to officially list, with an initial diluted P/E ratio reaching219x。Previous valuations for humanoid robots were entirely derived from the primary market. After its listing, Unitree's price-to-sales (P/S) and price-to-earnings (P/E) ratios will serve as a benchmark for repricing the entire global sector.。
4. Major Bank Perspectives
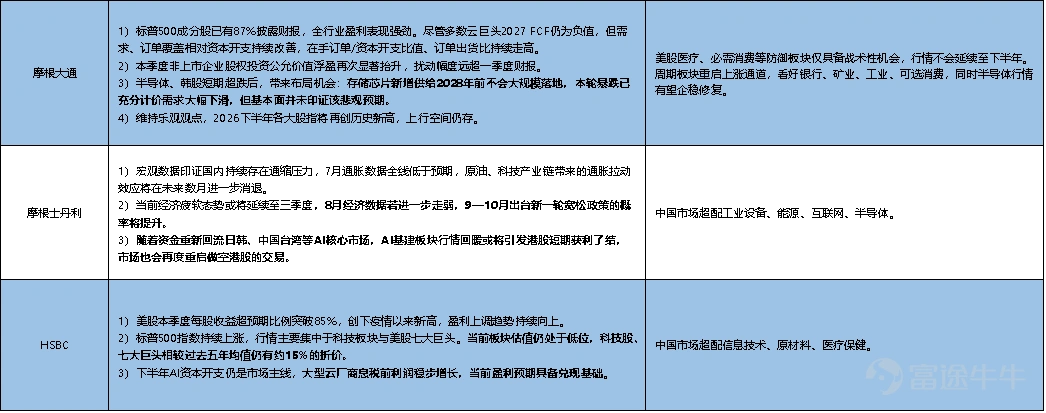
US Market Summary: The indices do not lack upward momentum, but stronger earnings breadth is needed to support high valuations, driven by semiconductor and tech leaders. After retail sales turned negative on August 14, the market immediately renewed concerns about growth,indicating extreme sensitivity to growth missing expectations at current levels. Before the September FOMC meeting, as long as inflation data does not deteriorate further and AI supply chain earnings continue to materialize,The core trend of US stocks remains resilient。 With 87% of S&P 500 constituents having reported earnings, sector-wide profitability remains robust. AI capital expenditure continues to be the market's main theme in the second half of the year; major cloud providers are seeing steady growth in EBITA, providing a solid foundation for current earnings expectations to materialize. Large-scale implementation of new memory chip supply is not expected before 2028.The recent sharp decline has fully priced in a significant drop in demand, but fundamentals have not confirmed this pessimistic outlook.
Hong Kong Equity Summary: The market is shifting towards pricing based on earnings realization and capital flow strength. Structural opportunities remain concentrated in AI, semiconductors, and innovative drugs, with earnings performance becoming the core variable driving divergence. Last week, HK stocks rose first and then fell, mainly because the market entered a phase of earnings realization and valuation rebalancing after the earlier rebound. Additionally, leaders like Tencent and JD.com showed divergences in capital expenditure, revenue growth rates, free cash flow, or growth trajectories.As capital flows back into core AI markets such as Japan, South Korea, and Taiwan, the rebound in the AI infrastructure sector may trigger short-term profit-taking in Hong Kong stocks, leading to a resurgence of short-selling activity. However, the probability of China introducing a new round of easing policies in September and October is expected to rise.
[Investment Advisory Information]
Yu Shilin, Licensed Representative, CE Number: ATQ882
Yang Yi, Licensed Representative, CE No.: BUR210
Sun Bihan, Licensed Representative, CE No.: BWS708
Disclaimer
This report is prepared by Futu Securities International (Hong Kong) Limited ("Futu Securities"). Without the prior written consent of Futu Securities, this report and the information contained herein may not be (i) reproduced, copied, or stored in any form, or (ii) directly or indirectly distributed or forwarded to any other person for any purpose. The information in this report is derived from sources that Futu Securities believes to be accurate and reliable as of the date of publication. However, this report is not intended to contain all information necessary for an investor’s decision-making and may be subject to delays, obstructions, or interceptions in transmission. Futu Securities makes no express or implied representation or warranty as to the adequacy, accuracy, completeness, reliability, or fairness of such information or opinions. Accordingly, Futu Securities and its affiliates (collectively, the "Futu Group") shall not be liable for any losses of any kind (including but not limited to direct, indirect, or consequential losses) arising from any third party’s reliance on the content of this report. The views, recommendations, suggestions, and opinions expressed in this report do not necessarily reflect those of Futu Securities or its affiliates and are subject to change without notice. Futu Securities has no obligation to update any information or opinions contained herein. This report is provided for general informational purposes only and is intended solely for the general reading of Futu Securities’ clients, without regard to any specific recipient’s investment objectives, financial situation, or particular needs. Nothing in this report constitutes or should be construed as an offer, recommendation, or solicitation by any member of the Futu Group to buy or sell any securities, investments, or other financial instruments. It should not be interpreted as an offer or invitation to purchase or sell securities. Any decision to purchase securities mentioned in this report should be based on publicly available information, including relevant prospectuses. The products discussed herein may not be suitable for all investors, and readers should fully consider relevant factors and seek professional advice before making any investment decisions. This report is provided to recipients on the basis that they are capable of independently evaluating investment risks and exercising independent judgment in investment decisions. In certain jurisdictions or countries, the distribution, issuance, or use of this report may violate local laws, regulations, rules, or licensing requirements. This report is not intended for distribution to or use by any person or entity in such jurisdictions or countries. Hong Kong investors with questions regarding Futu Securities research reports should contact Futu Securities directly. The Central Entity (CE) numbers of the authors’ SFC licenses are disclosed next to their names on the front page of this report. The analyst primarily responsible for preparing this report confirms that: (i) the opinions expressed accurately reflect his/her personal views regarding the listed corporation(s) covered in this report; and (ii) his/her compensation, past, present, or future, directly or indirectly, is not tied in any way to the specific recommendations or views expressed in this report. The analyst also confirms that neither he/she nor any related party has traded the securities of the listed corporation(s) covered in this report during the 30 calendar days prior to and the three business days following the report’s publication. Neither the analyst nor any related party serves as a senior officer of the listed corporation(s) covered in this report or holds any financial interest therein. In this report, Futu Securities holds no financial interest amounting to 1% or more of the listed company’s market capitalization and has had no investment banking relationship with the company in the past 12 months. None of the company’s employees are employed by the listed company.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comments
to post a comment
3
3