3x Bitcoin ETFs Are Coming: Dangerous Leverage Donning a Compliance Cloak
By: Xiao Bing
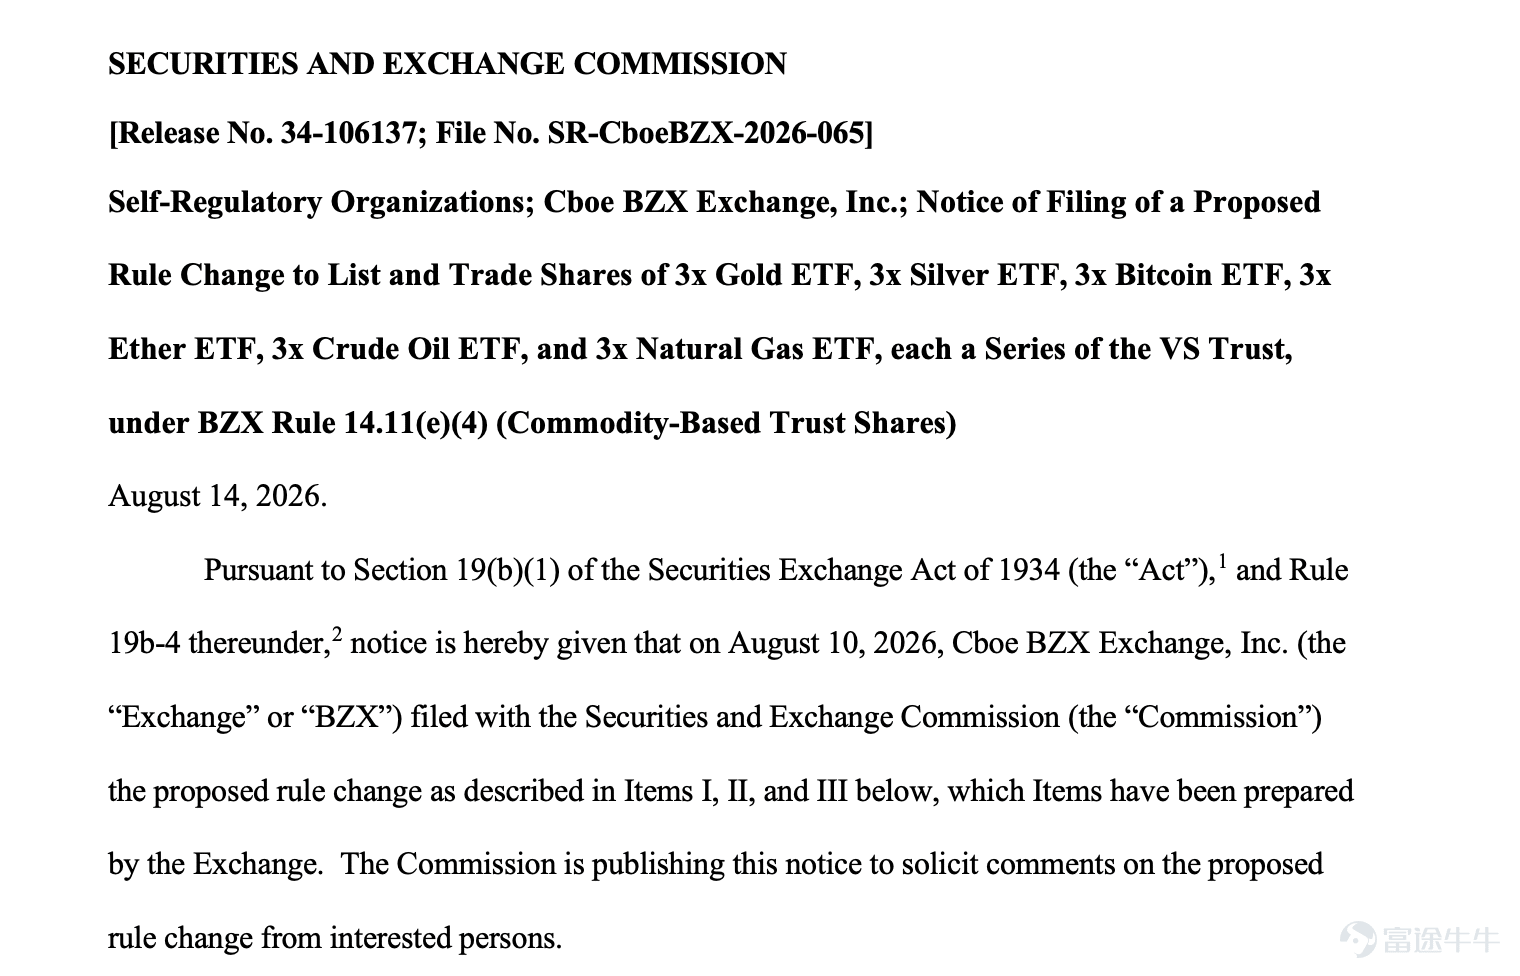
On August 14, the SEC issued a notice officially accepting the rule change proposal (File No. SR-CboeBZX-2026-065) submitted by Cboe BZX Exchange, which seeks to list a series of 3x leveraged commodity ETFs, including 3x Bitcoin ETFs and 3x Ethereum ETFs.

The applicant, Volatility Shares LLC, already operates 2x Bitcoin and Ethereum strategy ETFs in the U.S. market with a live track record. Cboe cited data in its application indicating that approximately 67 leveraged ETP products with 3x or inverse 3x exposure are currently listed on U.S. national securities exchanges. In other words, 3x leveraged ETFs have long existed in equity and commodity sectors, with crypto assets being the final piece of the puzzle.
The SEC will issue an approval or denial within 45 days, or initiate an extended review period of up to 90 days.
The most dangerous high-leverage trading in the crypto market is moving from offshore perpetual contract exchanges into standard U.S. securities accounts.
Let's start by looking at its structure.
The 3x Bitcoin ETF aims to deliver daily investment returns equal to three times the daily performance of Bitcoin prices, before fees. If Bitcoin rises 2% in a day, the fund targets a 6% gain; if Bitcoin falls 3%, the fund targets a 9% loss.
Note the key qualifier here: "daily."
The fund does not hold Bitcoin directly. It gains exposure by holding Bitcoin futures contracts on the CME Group (Chicago Mercantile Exchange), primarily in the front-month and second-month contracts. Each month, there is a five-day rolling window to roll over expiring contracts into the next month's contracts, with approximately 20% of the position rolled each day. Cash and cash equivalents serve as margin collateral for the futures positions.
Legally, this fund is structured as a registered commodity pool, regulated by the CFTC and NFA, and is not registered under the Investment Company Act of 1940. This choice makes sense, especially after the SEC rejected ProShares' application for a 3x crypto ETF in late 2025 by citing Rule 18f-4 of the 1940 Act (which limits fund leverage to no more than 200%). Volatility Shares chose to bypass this path by adopting a commodity pool structure.
This is a mathematical trap inherent to all leveraged ETFs, but it is amplified to the extreme with Bitcoin.
Suppose Bitcoin rises 10% on the first day and falls 10% on the second. Over these two days, Bitcoin's net value becomes: 1.10 × 0.90 = 0.99, representing a 1% loss.
Over the same period, the net value of the 3x leveraged ETF becomes: 1.30 × 0.70 = 0.91, representing a 9% loss.
Bitcoin was down only 1%, while the 3x ETF fell 9%. The loss magnitude was nine times that of Bitcoin, far exceeding the nominal threefold leverage.
This phenomenon is known as "volatility decay" (or volatility drag). Leveraged ETFs recalculate their benchmarks daily based on that day's price movements, amplifying gains on a higher base and losses on a lower base. In volatile markets, even if the underlying asset returns to its starting point, the net asset value (NAV) of the leveraged ETF will continue to decline.
Bitcoin's annualized volatility typically ranges between 50% and 80%, three to four times that of the S&P 500. Higher volatility leads to more severe volatility decay. While the NAV erosion of a 3x S&P 500 ETF in a choppy market is already alarming, switching the underlying asset to Bitcoin would amplify this decay exponentially.
Let's illustrate this with a simplified simulation.
Assume Bitcoin experiences an average daily volatility of ±5% over 30 days, ultimately returning to its starting price. Investors holding the spot asset break even. However, investors holding the 3x ETF would lose approximately 20%-30% of their principal solely due to volatility decay, depending on the specific path and sequence of price movements.
The Cboe acknowledged this in its application. The fund sponsor, Volatility Shares, was required to include explicit warnings in its prospectus:"The Fund is not suitable for investors who do not intend to actively monitor and manage their investment portfolios."
Taking a broader view, what is unfolding is a migration of leverage.
Over the past decade, high-leverage trading in the crypto market has been concentrated on offshore exchanges: BitMEX invented perpetual contracts, while Binance and Bybit made 100x leverage a standard feature. These products are not subject to U.S. securities laws, lack investor suitability reviews, and liquidations due to margin calls are commonplace.
Currently, similar leveraged exposure (albeit with significantly lower multiples) is entering the US regulated securities market through ETFs. These products are wrapped in a layer of compliance: prospectuses, exchange listing rules, CFTC oversight, and FINRA suitability requirements are all in place. However, the core risk-return profile remains unchanged. Leveraging an asset with annualized volatility exceeding 50% by three times is an aggressive trade, regardless of what the trading interface looks like.
The European market has already taken the lead. In November 2025, LeverageShares launched the world’s first 3x long and 3x inverse Bitcoin and Ethereum ETPs, listed on European exchanges. Cboe cited this precedent in its application as one of the arguments for why the US market should follow suit.
If the SEC approves these products, we can anticipate the following:More issuers will follow. ProShares, Direxion, and GraniteShares have already filed applications for 3x crypto ETFs. Competition will drive down fees and diversify products; 3x SOL, 3x XRP, and 3x inverse Bitcoin will each find their own audience.
The supply side of crypto leverage is being completely reshaped. The question used to be 'How do I open a Binance account?' In the future, it will become 'Should I include a 3x Bitcoin ETF in my retirement account?'
As everyone knows, holding a 3x long SK Hynix position over the long term is ill-advised, but that won’t stop it from becoming one of the most popular products in the market.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments (2)
to post a comment
10
3