Net profit reached RMB 44.5 billion in the first half of the year; six months into Kweichow Moutai's market-oriented reforms: iMoutai revenue surged 270%, while domestic distributors decreased by 266.
Source: Times Finance; Author: Lin Xinlin
Kweichow Moutai has fallen into a situation of "rising revenue but stagnant profits."
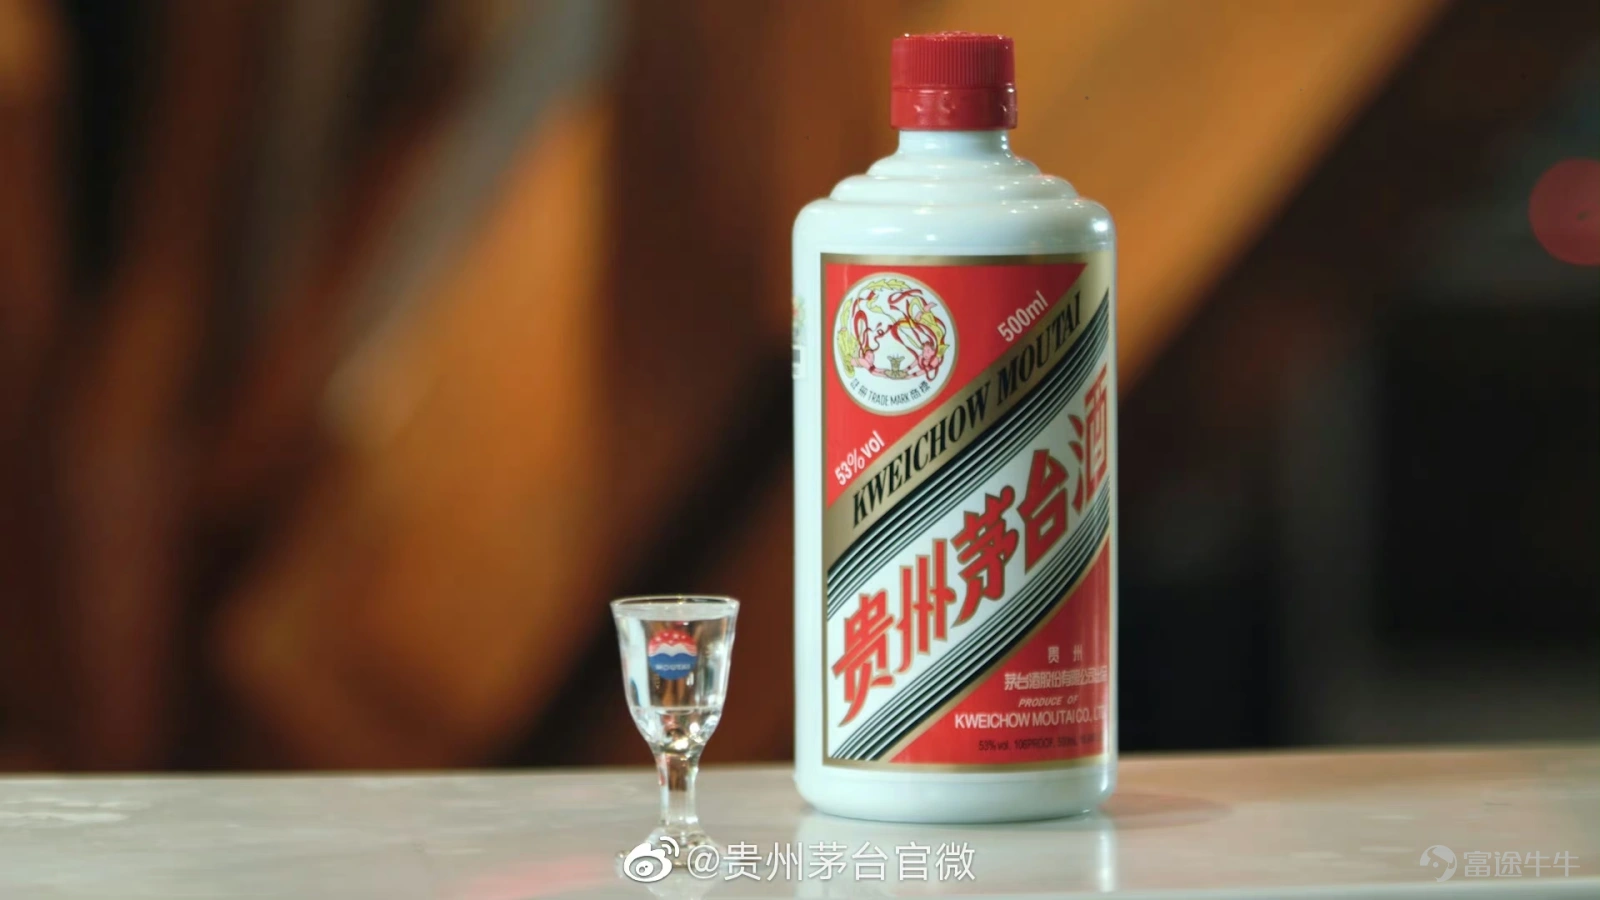
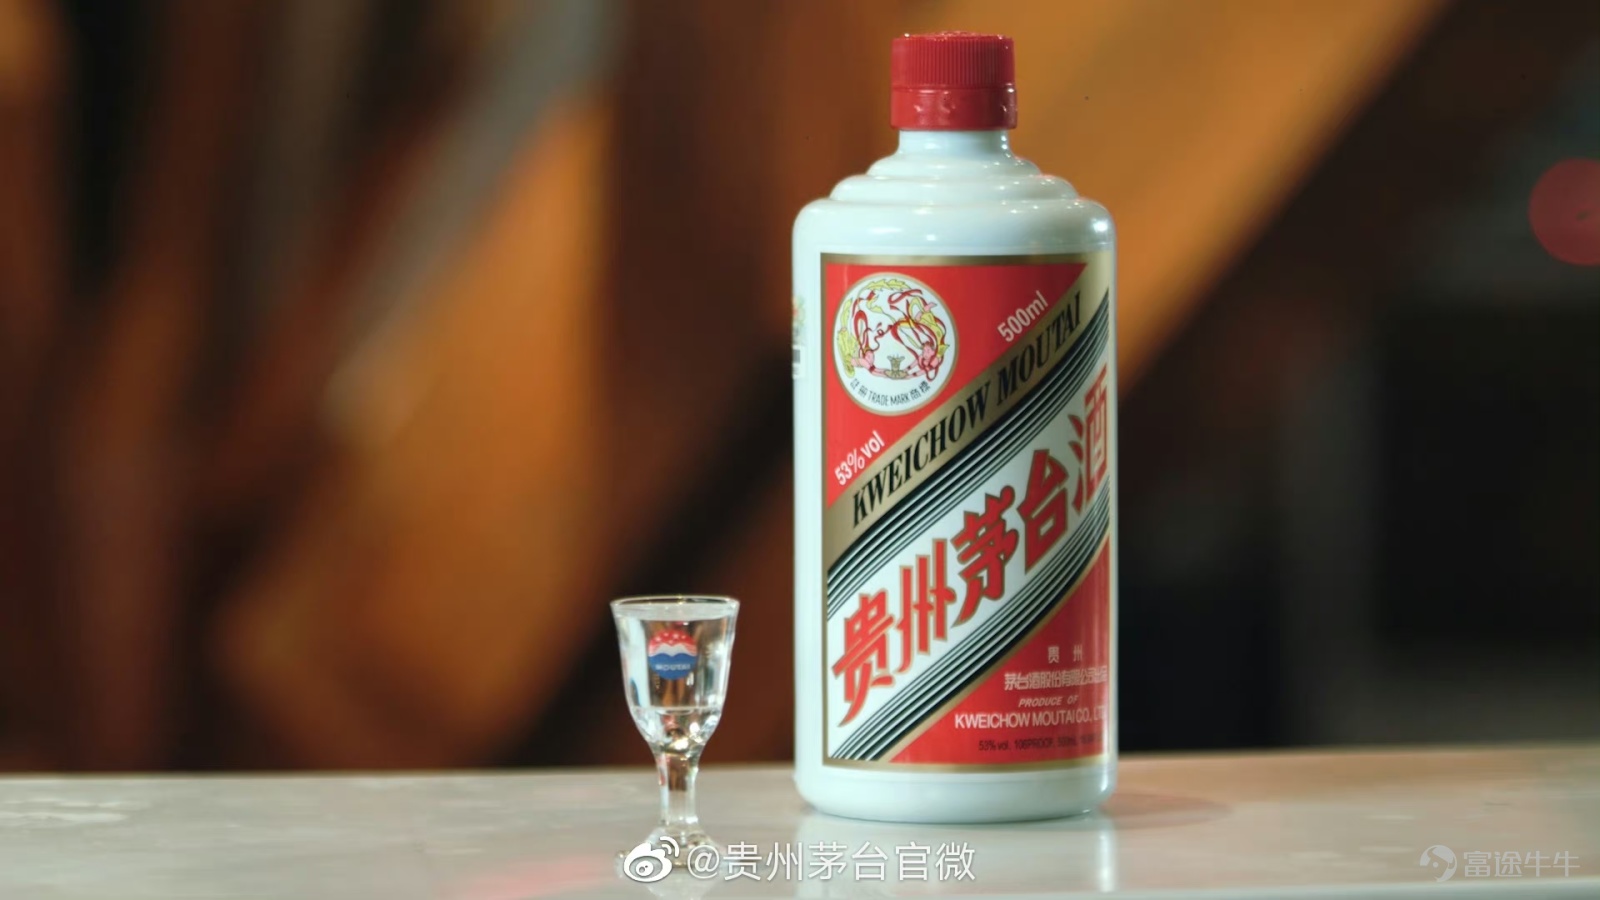
Image source: Official WeChat account of Kweichow Moutai
On the evening of August 14, Kweichow Moutai (600519.SH) announced its financial results for the first half of 2026. During the period, it achieved operating revenue of RMB 90.703 billion, a year-on-year increase of 1.47%; net profit attributable to shareholders of the listed company was RMB 44.517 billion, a year-on-year decrease of 1.95%. The production volume of base liquor for Moutai liquor was approximately 41,000 tons, while that for series liquors was approximately 31,000 tons.
"The company demonstrated strong developmental resilience amid cyclical and structural adjustments in the industry, laying a solid foundation for achieving full-year targets," Kweichow Moutai stated in its financial report. This year, Kweichow Moutai did not disclose specific performance growth targets for 2026, with management repeatedly emphasizing a stance of "not being solely driven by metrics."
Shareholders continue to flock in. As of the end of the reporting period, the total number of ordinary shareholders of Kweichow Moutai stood at 296,400, an increase of nearly 40,000 from the end of the first quarter.
Direct sales account for over 57% of revenue, reaching RMB 51.9 billion in the half-year
Compared to the rebound in the first quarter, Kweichow Moutai's revenue growth slowed significantly in the second quarter. Recent earnings pre-announcements from multiple listed liquor companies also indicate that at least seven firms are facing declining profits or losses.
In its financial report, Kweichow Moutai pointed out that revenue growth was primarily driven by an increase in sales volume during the period.
From a product perspective, in the first half of this year, Moutai liquor, the flagship product with annual revenue exceeding RMB 100 billion, generated RMB 77.724 billion in revenue, a year-on-year increase of approximately 2.8%, indicating a slowdown in growth. As the second growth curve, series liquors recorded RMB 12.934 billion, marking a rare 6% decline. These products mainly include Moutai Prince Liquor, Moutai 1935, Han Jiang Liquor, and Lai Mao Liquor. For the entire first half, Moutai liquor and series liquors accounted for 85.7% and 14.27% of total revenue, respectively.
Since launching market-oriented reforms at the end of last year, the contribution share of different channels has become a key metric closely watched for Kweichow Moutai.
In the first half, wholesale and agency channels generated RMB 38.697 billion in revenue, a year-on-year decrease of 21.57%. In contrast, direct sales channel revenue surged by 29.88% to RMB 51.962 billion. Based on these figures, wholesale/agency and direct sales channels accounted for 42.68% and 57.32% of total revenue, respectively. The share of direct sales increased by more than 7 percentage points compared to 50.1% at the end of last year.
According to observations by Times Finance, Kweichow Moutai has consistently outperformed its wholesale channel through direct sales for several consecutive quarters since the fourth quarter of last year.
Behind the shift in revenue structure across channels lies, on one hand, the proactive effort to clear channel pressure. This follows multiple statements by Kweichow Moutai's current Chairman, Chen Hua, emphasizing that the company does not adhere strictly to metrics and will not force targets in violation of market dynamics.
As of the end of the reporting period, Kweichow Moutai had 2,307 domestic distributors, with 220 added during the period and 266 removed. According to Times Finance's analysis, this represents the largest contraction in its distributor network since 2021. Prior to this, the last time Kweichow Moutai undertook such a large-scale adjustment to its distributor system was during the restructuring initiated in 2019–2020.
Since launching market-oriented reforms at the end of last year, management has repeatedly emphasized maintaining channel resilience and market stability, stressing that Kweichow Moutai and its various channel partners are not in a zero-sum competitive relationship but rather form a closely linked community of shared interests. Over the past six months, Kweichow Moutai has reduced the burden on distributors by eliminating the distribution model and significantly cutting quotas for non-standard products.
On the other hand, Kweichow Moutai has been continuously strengthening its direct sales infrastructure, including the iMoutai platform.
According to previous disclosures by Wang Li, Acting General Manager of Kweichow Moutai, as of May 31, the platform had added approximately 16.67 million new registered users in 2026, bringing the cumulative total to 96.15 million. The average monthly active users stood at approximately 9.56 million, with around 7.13 million transactions completed.
In the first half of this year, Kweichow Moutai generated RMB 40.264 billion in tax-exclusive alcohol revenue through its "iMoutai" digital marketing platform. In comparison, iMoutai's revenue for the same period last year was RMB 10.76 billion, representing a year-on-year increase of 274.2%. For the full year last year, iMoutai's total revenue was RMB 13 billion, meaning that this year's first-half performance has already exceeded three times the full-year scale of the previous year.
Three price hikes within the year; benefits from price increases have yet to be fully realized
In the first half of the year, Kweichow Moutai rarely took action to adjust prices for its flagship products.
Historically, Kweichow Moutai last adjusted the contract price and retail market price of Feitian Moutai in 2013 and 2018, respectively. However, since the beginning of this year, the company has repeatedly signaled potential price increases.
Specifically, the first round of price adjustments took place on March 30, when Kweichow Moutai raised the ex-factory price of its 500ml Feitian Moutai (53% vol) from RMB 1,169 per bottle to RMB 1,269 per bottle, and increased the self-operated retail price from RMB 1,499 per bottle to RMB 1,539 per bottle.
Subsequently, in May, Kweichow Moutai implemented a second round of price hikes targeting non-standard products, raising the retail prices for certain non-standard items sold through direct channels, such as the 15-year aged Moutai, Premium Moutai, and the Year of the Horse zodiac edition.
Beyond balancing supply and demand and optimizing the pricing structure, the price adjustments are more significantly aimed at boosting Moutai's financial performance while alleviating pressure from volume expansion. Previously, a research report by China Merchants Securities noted that the Feitian price hike was projected to increase Moutai's annual revenue by RMB 3.4 billion and contribute approximately 2.3% positively to its full-year earnings forecast.
However, the latest financial report shows that in the first half of the year, Kweichow Moutai's net profit attributable to shareholders of the listed company amounted to RMB 44.517 billion, a year-on-year decline of 1.95%, reflecting a scenario of rising revenue but stagnant profits.
According to Times Finance, although the self-operated retail price and circulating wholesale price of Feitian Moutai have risen compared to last year, the actual price adjustment for Feitian only took effect on March 31. This coincided with the start of the traditional off-season for baijiu after March. Additionally, distributors had already made payments early in the year to lock in part of their quotas, which may limit the positive impact on second-quarter profits.
Xiao Zhuqing pointed out to Times Finance that the slight increase in revenue coupled with a small decline in profit represents transitional pain caused by the restructuring of the distribution channel system. It also reflects that the entire baijiu industry has fully entered an era of zero-sum competition in a saturated market, with industry leaders bidding farewell to the past era of high growth. He believes that as higher-margin products like the Premium and Zodiac editions are increasingly channeled into self-operated sales, the profit pressure stemming from the channel structure will be gradually offset and repaired.
On July 18, Moutai initiated the second large-scale price adjustment for Feitian Moutai this year, raising the self-operated retail price on the 'i Moutai' platform from RMB 1,539 to RMB 1,639; the contract price was increased from RMB 1,269 to RMB 1,369; furthermore, the retail price for the 1L Feitian Moutai (53% vol) on the 'i Moutai' platform was adjusted from RMB 3,119 per bottle to RMB 3,269 per bottle.
Notably, Kweichow Moutai has now established a dual pricing system across its online and offline channels. Recently, at Kweichow Moutai's offline self-operated stores, the selling price of Feitian Moutai has risen to RMB 1,753 per bottle. This follows a previous increase to RMB 1,719 per bottle in late July, creating a price gap of over RMB 100 compared to online prices.
Recently, Zheshang Securities pointed out in a research report that Kweichow Moutai's early price adjustment during the off-season may help further stabilize market prices, compress speculative margins, and lay the foundation for price stability in the subsequent peak season.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more
Comments
to post a comment