Oracle reports earnings in the early hours of Friday; could cloud computing provide a new catalyst?
Rising despite losses! Is AI compute leasing the next bubble or a genuine trend?
The AI computing power leasing sector exploded last night.
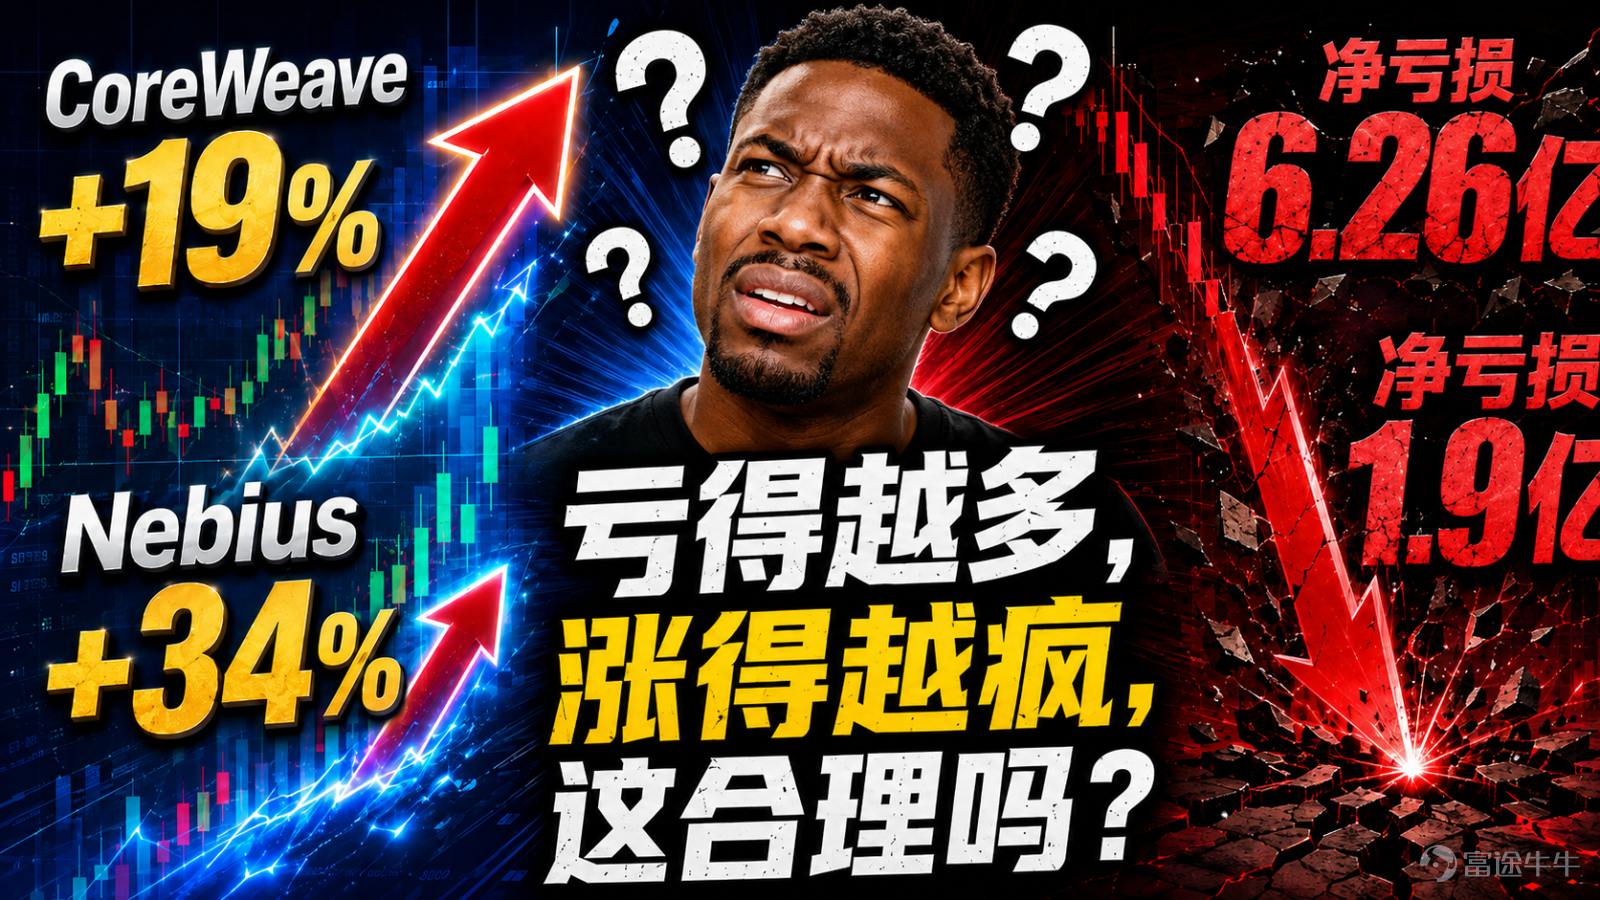
CoreWeave (CRWV) surged 19.28%, with its market cap approaching $60 billion. Nebius (NBIS) was even more extraordinary, skyrocketing 34.14% and breaking through a $70 billion market cap.Two AI computing leasing companies reported results on the same day, pushing their combined market cap to $120 billion. I’ve seen this scene before—NVIDIA rallied in the same way in 2023.$CoreWeave (CRWV.US)$$NEBIUS (NBIS.US)$

Let’s look at CoreWeave first.
Revenue reached $2.575 billion, doubling year-over-year and exceeding expectations.Backlog orders totaled $104 billion.Enough to keep them busy for several years.Meta just signed a $21 billionAI cloud computing supply agreement, extending the contract directly to 2032. And then?Net loss of $626 million.High earnings, even higher cash burn. What’s more alarming is thatDebt stands at $35 billion,with quarterly interest payments of $640 million.The core logic is simple: borrow money to buy GPUs, then lease them out to capture the spread.As long as computing power remains in tight supply, this model works. But once capacity eases, the leverage could become crushing.
Now let’s look at Nebius.
Revenue hit $580 million, a staggering 454% year-over-year increase. H1 revenue reached $980 million, up 529%. Adjusted EBITDA turned positive to $236 million—it’s starting to make money.
Under GAAP, it still posted a loss of $190 million. Customer commitments exceed $40 billion—these are signed contracts with payment obligations, not just empty promises. The CEO stated directly:Production capacity for 2027 has already been fully sold out.Growth is more robust than CoreWeave's, scale is smaller than CoreWeave's, and debt burden is lighter than CoreWeave's.

On what basis is it rising?
The market currently subscribes to this logic:Those with computing power capacity, locked-in long-term customers, and stable cash flows are the ones that hold value.CoreWeave's $104 billion in backlog orders and Nebius's $40 billion in customer commitments—are not just slide deck projections, but signed contracts.Demand for computing power is real and substantial, not merely hype.
But don't get carried away; there are risks.
Both are operating at a loss.—CoreWeave posted a $600 million loss, while Nebius recorded a $190 million loss.
They are all debt addicts.— CoreWeave has $35 billion in debt, with quarterly interest payments of $640 million. If demand for computing power slows down even slightly, they won't be able to cover the interest.
Competitors are multiplying.— SpaceX has started renting computing power, and it wouldn't be surprising if Meta or Amazon launched their own rental services soon.
Stocks have already risen significantly.— CRWV is up 26% year-to-date, surging 19% after its earnings report; NBIS jumped 34% in a single day. At these levels, buying in is essentially betting on the frenzy continuing.

One-Sentence Summary
The earnings reports from AI computing leasing companies prove one thing:Demand for AI computing power is real; companies are actually spending money, not just hyping it up.But don't forget—This sector falls just as brutally as it rises wildly.CoreWeave and NEBIUS are bothhigh-growth, high-leverage, and loss-making players.With compute capacity in short supply in the near term, the bull case holds water. In the long run, however, survival will depend on who achieves profitability first. The narrative on compute leasing is only on page two; we are still far from the endgame.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comment (1)
to post a comment
9