Mark your calendars for 2 a.m. this Thursday! Will the Fed raise interest rates?
Event Sniper | US July CPI: Short-term Bullishness and Medium-term Risk Spillover
💡 Key Insight
– US July CPIYoY +3.4%, MoM +0.07%; Core CPI YoY +2.5%, MoM +0.22%Broadly in line with expectations; the tail risk of a secondary surge in inflation did not materialize.
– Coupled with a net decrease of 23,000 in July non-farm payrolls, the CME FedWatch tool shows the probability of a September rate hike has dropped from48.4% to 42.1%, meaning the Federal Reserve was not forced to take immediate action in September.
– Short-end rates declined, while long-end rates failed to fall in tandem due to structural constraints. Tech stocks led the gains, and gold, up 1.5% on the day, emerged as the clearest beneficiary.The medium-term trajectory remains dependent on the path of core PCE and the evolution of default risks in private credit.
1. CPI Component Breakdown: Energy weighed on the headline figure, while underlying inflation stickiness persists.
Chart 1: Comparison of July CPI Data and Forecasts
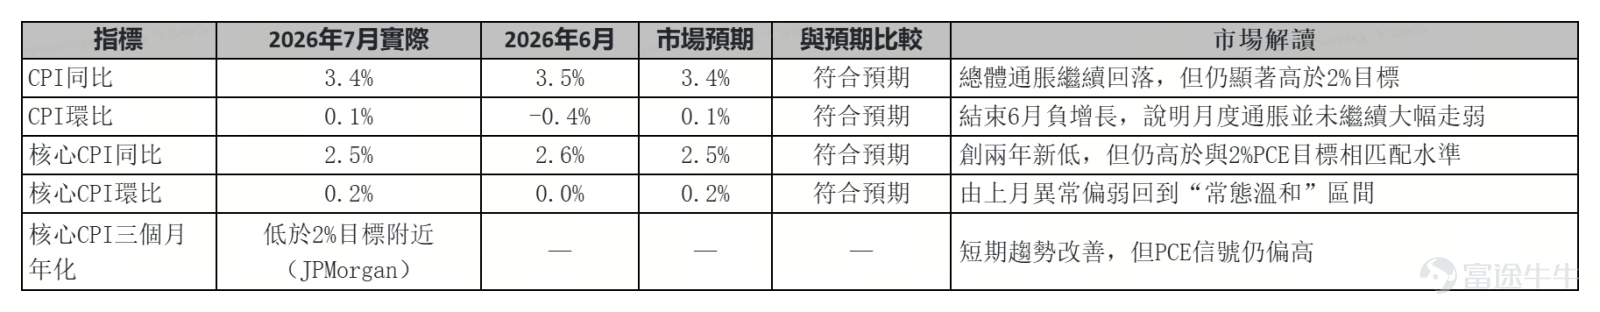
Sources: WIND, JPM, Fitch Ratings, Morgan Stanley
Breakdown by component:
– Energy prices: -1.5% month-over-month (gasoline -2.9%), the primary driver of the overall moderation
– Food prices: +0.1% month-over-month, largely stable
– Housing costs: +0.1% month-over-month, still contributing about two-thirds of the monthly increase, with notable stickiness
– Airline fares: +2.2% month-over-month, signaling a rebound in service prices
– Healthcare service prices: +0.4% month-over-month
Summary: The mild CPI reading was primarily driven by a drag from energy prices; underlying inflation exhibits a structural pattern of "sticky housing costs, recovering services, and stabilizing goods."
2. Policy Implications: The majority holds steady; August data is the key variable.
- Core PCE remains near3.3%levels, with major banks forecasting the month-on-month change at0.22%
- If an energy rebound coincides with a recovery in services, keeping core inflation stuck within the0.2%-0.3%range, the Fed can maintain its relatively tight stance.
- This data release is unlikely to change the stance of the three dissenting FOMC members in July, nor will it prompt the majority to support a rate hike.
– For the majority, economic data released in August will be the decisive factor for policy decisions.
3. Immediate Market Reaction in Asset Prices
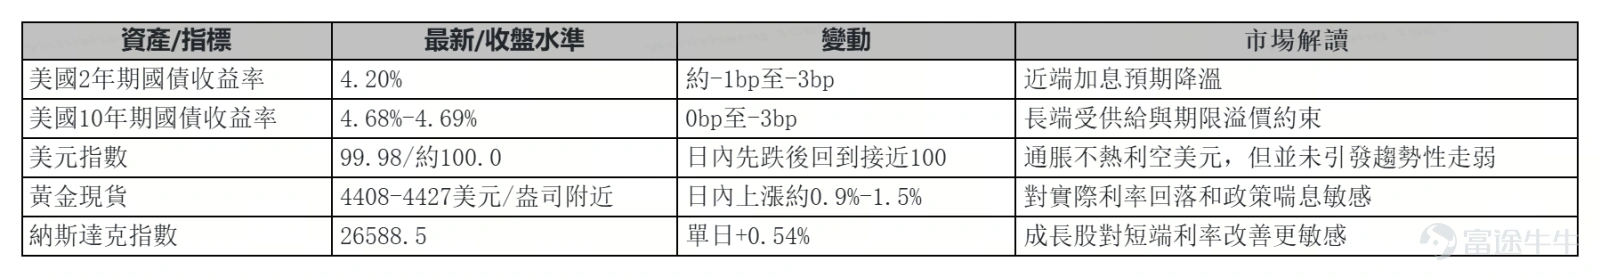
Chart 2: Immediate reaction of key interest rates and market prices following the CPI release
Sources: Wind, JPMorgan, Fitch Ratings, Morgan Stanley
– 2-Year US Treasury: Yield ↓ to 4.199%, cooling expectations for short-end rate hikes
– 10-Year US Treasury: Flat at 4.686%-4.692%
– 30-Year US Treasury: ↑ to around 5.25%, with the long end constrained by structural factors such as fiscal deficits, Treasury supply, term premium, overseas demand, and financing for AI capital expenditure
– US Stocks: Broadly higher, led by technologyGrowth stocks are long-duration assets; a cut in short-term rates first alleviates valuation pressure.
– US Dollar: weakened at one point, closing at 99.98; high long-term rates + carry trade + geopolitical risks support resilience
– Gold: Intraday +1.5%, short-term rates ↓ → reduced real rate pressure → lower cost of holding
4. Medium-term risk spillover
1. Macro level: Stagflation risks emerging
– M2 growth rises to nearly 6% by Q2 2026 GDP drops to 1.5%
– Daily crude oil supply gap of 5.5 million barrels
2. Corporate credit level: Acceleration in private credit defaults
- Fitch data for Q2 2026: The US private credit default rate rose to6%(5.7% in Q1)
- Morgan Stanley expects that, driven by the AI-driven disruption of the software industry, direct lending default rates could climb to8%
- The scale of private credit reached$2.1 trillionUSD, with a significant portion of capital coming from semi-liquid instruments
3. Potential transmission channels
If the default rate breaches a critical threshold, redemption pressure will transmit rapidly, triggering a dual effect:
1. Surge in safe-haven demand: Capital flows from risk assets into gold
2. Forced policy pivot: If systemic defaults threaten financial stability, the Fed may cut rates early or even restart QE. The resulting decline in real interest rates will lift the biggest headwind facing gold prices.
[Investment Advisory Information]
Yu Shilin, Licensed Representative, CE Number: ATQ882
Disclaimer
This report is prepared by Futu Securities International (Hong Kong) Limited (“Futu Securities”). Without prior written consent from Futu Securities, this report and the information contained herein may not be (i) reproduced, copied, or stored in any form, or (ii) directly or indirectly distributed or transmitted to any other person for any purpose. The information in this report is derived from sources believed by Futu Securities to be accurate and reliable at the time of publication. However, this report is not intended to contain all information necessary for an investor’s decision-making and may be subject to delays, obstructions, or interceptions in delivery. Futu Securities does not expressly or impliedly guarantee or represent the adequacy, accuracy, completeness, reliability, or fairness of any such information or opinions. Accordingly, Futu Securities and its affiliates (collectively, the “Futu Group”) shall not be liable for any losses of any kind (including, but not limited to, direct, indirect, or consequential losses) arising from any actions taken by third parties relying on the contents of this report. The views, recommendations, suggestions, and opinions expressed in this report do not necessarily reflect those of Futu Securities or its affiliates and may be changed without notice. Futu Securities has no obligation to update any information or opinions contained herein. This report is provided for general informational purposes only and is intended solely for general reading by clients of Futu Securities, without regard to any specific recipient’s investment objectives, financial situation, or particular needs. Nothing in this report constitutes or should be construed as an offer, recommendation, or solicitation by any member of the Futu Group to buy or sell any securities, investments, or other financial instruments, nor should it be interpreted as an offer or invitation to purchase or sell securities. Any decision to purchase securities mentioned in this report should take into account publicly available information, including prospectuses relating to such securities. Products referenced in this report may not be suitable for all investors; readers should fully consider relevant factors and seek professional advice before making any investment decisions. This report is provided to recipients on the assumption that they are capable of independently evaluating investment risks and exercising independent judgment in investment decisions. In certain jurisdictions or countries, the distribution, issuance, or use of this report may violate local laws, regulations, rules, or registration or licensing requirements. This report is not intended for distribution to, or use by, any person or entity in such jurisdictions or countries. Hong Kong investors with questions regarding Futu Securities research reports should contact Futu Securities directly. The Central Entity Reference Number of the author’s SFC license is disclosed next to the author’s name on the front page of this report. The analyst primarily responsible for preparing this report confirms that: (i) the views expressed in this report accurately reflect his/her personal views about the subject companies covered; and (ii) his/her compensation, past, present, or future, directly or indirectly, is not tied in any way to the specific recommendations or views expressed in this report. The analyst further confirms that neither the analyst nor any related party has traded in the securities of the subject companies covered in this report during the 30 days prior to, or within three business days following, the publication of this report. Neither the analyst nor any related party serves as a senior officer of, or holds any financial interest in, the companies covered in this report. Futu Securities holds no financial interest equal to or greater than 1% of the market capitalization of the companies covered in this report, and has had no investment banking relationship with these companies in the past 12 months. Employees of Futu Securities are not employees of the companies covered in this report.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments
to post a comment
2
2