Mid-2026 Review: How to Identify the Key Themes Amidst Changing Market Dynamics?
Watch these three key directions for Hong Kong stocks today! Alarm bells silenced! CPI targets fully met! Pressure from rate hikes eases sharply—could the Hang Seng Index hit new highs again?
Must-Read at the Open | HK Stock Market Outlook for August 13: CPI Lands Mildly, Rate Hike Fears Subside, Is a Rebound Window Opening?
If you find this content helpful, please hit follow. Once we surpass 100 followers, I'll give out perks to all my followers!
I. Quick Look at Yesterday's CPI Data (August 12, 20:30)
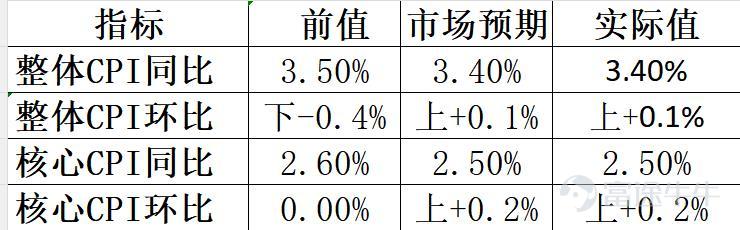
On the evening of August 12 (Beijing Time), the U.S. Department of Labor released the July CPI data:

Key Interpretation: All four figures—year-over-year and month-over-month for both headline and core CPI—met market expectations. Headline CPI recorded its smallest year-over-year increase since March, while core CPI year-over-year was slightly below the previous value of 2.6%. Housing costs remained the primary driver, contributing approximately two-thirds of the monthly rise in headline CPI; energy prices fell 1.5% month-over-month but still rose 14.7% year-over-year.
II. Market Reaction: Rate Hike Expectations Cool, U.S. Stocks Diverge
Rate Hike Expectations: The CME FedWatch Tool shows that the market's probability of a rate hike in September has dropped from about 47% to 44.1%. Morgan Stanley's Chief Equity Strategist stated that inflation data in line with expectations will reinforce the market narrative that "there is no need for a rate hike." Analysts believe that the relatively mild inflation in July and weak employment data will give the Federal Reserve reason to remain on hold.
U.S. Stocks (Wednesday, August 12): The three major indices showed mixed performance—the Dow Jones fell 0.04% to close at 53,770.27, the S&P 500 rose 0.26% to 7,748.50, and the Nasdaq gained 0.54% to 26,588.49. The Philadelphia Semiconductor Index surged nearly 2.5%, led by memory and AI hardware stocks; however, the five major tech giants (Meta, Apple, Google, Microsoft, Amazon) all closed lower.
Commodities: Spot gold briefly plunged $30 after the data release, then quickly rebounded to hit a new intraday high; spot silver surged nearly 3% during the day.
III. HK Stock Performance Yesterday and Today's Open
HK Market Close on August 12: The Hang Seng Index closed at 25,440 points, down 212 points, falling below the 25,500 threshold and hitting a two-week low. Total market turnover reached HKD 216.7 billion. Most tech and internet stocks declined, dragging down the broader market—Tencent fell 2%, Alibaba dropped 3%, Meituan dipped 1.5%, and NetEase slid 5.1%, marking it as the worst-performing blue-chip stock.
Southbound Capital (August 12): Net selling of HK stocks totaled HKD 2.906 billion, marking the second consecutive day of outflows. However, structural divergence was evident—net buying included MINIMAX (HKD 709 million; net buying for five consecutive days, with cumulative inflows exceeding HKD 6.7 billion), Tencent (HKD 683 million), SMIC (HKD 456 million), and Zhipu (HKD 416 million). Alibaba saw the largest net selling at HKD 1.461 billion.
HK Market Opening Estimate for August 13: The Hang Seng Index is expected to open lower by 17 points or 0.07% at 25,423 points; the Hang Seng Tech Index is set to open down by 1 point or 0.04%. In terms of sector performance, oil & gas, innovative pharmaceuticals, and software sectors rose, while real estate and construction advanced. Insurance, media, and financial sectors declined.
IV. Sector Outlook
Semiconductors/AI Hardware: The Philadelphia Semiconductor Index surged nearly 2.5%, with memory stocks rising in tandem (Micron Technology jumped 4.92%). Southbound capital continued to increase its position in SMIC (net buying of HKD 456 million on August 12). Short-term sentiment is bullish; consider buying on dips.
AI/Large Language Models: MINIMAX-W has seen net buying from southbound capital for five consecutive days, with cumulative inflows exceeding HKD 6.7 billion. The trend of southbound capital rotating from high-dividend sectors into AI and semiconductor chains remains unchanged, with sector prosperity trending upward.
Oil/Energy: Negotiations between the US and Iran regarding the Strait of Hormuz remain deadlocked, with Brent crude briefly approaching USD 90 per barrel. Rising oil prices provide short-term support for energy stocks, but geopolitical uncertainty remains extremely high, making trading difficult.
Tech/Internet: Tencent's share price softened ahead of its earnings release, while Alibaba faced significant selling pressure from southbound capital, totaling HKD 1.461 billion. With the peak earnings season for tech and internet companies approaching, adopt a wait-and-see stance in the short term and await earnings guidance.
Insurance: Persistent rumors about taxation on overseas insurance policies continue to weigh on the sector. Avoid insurance stocks such as AIA in the short term.
V. Trading Recommendations
The Hang Seng Index closed at 25,440 points yesterday, breaking below the 25,500 level. CPI data came in mildly, further cooling expectations for a Federal Reserve rate hike in September, leading to warmer external sentiment. However, HK stocks had already priced this in yesterday (with tech stocks weakening ahead of earnings, dragging down the broader market), resulting in a slight gap down at today's open.
Specific strategies:
1. Semiconductors/AI: Consider buying on dips. The surge in the Philadelphia Semiconductor Index provides emotional support, and southbound capital continues to add to positions in SMIC;
2. Maintaining a medium-term bullish view on AI and large language models; continuous buying by southbound capital into MiniMax is a significant signal;
3. Adopting a wait-and-see approach for tech and internet stocks, pending earnings releases from companies like Tencent before making further judgments;
4. Avoiding insurance stocks in the short term due to lingering policy uncertainties;
5. Oil prices have short-term support but face significant geopolitical risks; consider light positions or staying on the sidelines;
6. The Hang Seng Index has short-term support at 25,300 points and resistance at 25,800 points; keep position sizing between 40-50%.
If you find this content helpful, please hit follow. Once we surpass 100 followers, I'll share exclusive perks with all my friends who followed!
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comment (1)
to post a comment
4