Oracle surges post-earnings: Is cloud computing facing new opportunities?
A delayed rebuttal is still a rebuttal; the A100 provides a perfect logical foundation for Neocloud.
Author and source: Shaoshupai Opinion Bureau
Last night's conference call by CoreWeave (a representative US neo-cloud infrastructure company, or "Neocloud") was impressive. The most striking takeaway was neither the CFO's remark that "we are seeing demand, pricing, and margin all expanding," nor the cumulative RPO reaching $129 billion (more than 3.3 times the annual CapEx), but rather this statement:
"We recently signed an A100 contract that extends into 2029 at an attractive price." For example, we recently signed an A100 contract with a term extending to 2029 at a highly attractive price.
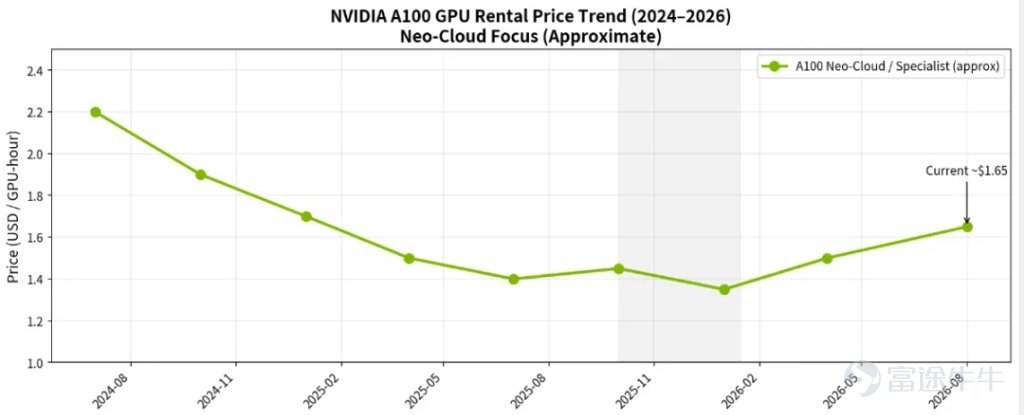
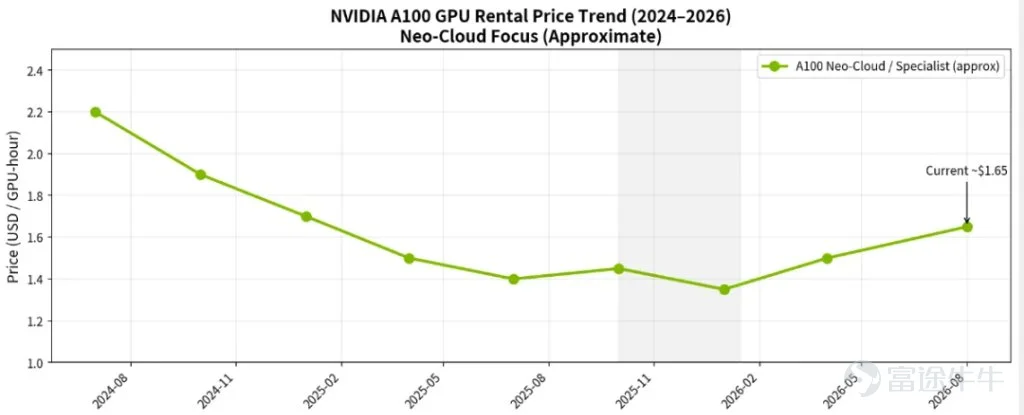
This aligns perfectly with the open letter Jensen Huang just published on X, in which he stated that the A100's economic life approaches ten years. As we know, the A100 was launched in 2020. A GPU released six years ago can still secure new contracts in 2026, extending through 2029, at prices that remain "attractive."
This strikes at the very core of the Neocloud business model.
CoreWeave explicitly disclosed in its 2025 10-K filing that the depreciation period for GPUs and related technical equipment is six years.This agreed-upon depreciation period has been heavily questioned by prominent short-seller Michael Burry, forming the core of his bearish thesis on AI in November 2025.
Burry argues that the true economic life of GPUs is only about 2-3 years, whereas hyperscalers depreciate these assets over 5-6 years. This leads to a significant understatement of depreciation expenses and an overstatement of cloud business profits.
This skepticism is not unfounded (which is why it shook the market significantly at the time). If GPUs truly generate economic value for only 2-3 years, then the high leverage employed by neocloud providers is indeed highly dangerous:
Borrowing money to buy GPUs → Rapid decline in the economic value of GPUs → Asset residual value approaches zero → The assets stop generating profit before the debt is fully repaid.
Recently, CoreWeave provided a direct counterexample, effectively refuting Michael Burry. The A100 GPUs from 2020 have already completed their six-year depreciation cycle by 2026, yet new contracts can extend to 2029, with their economic value continuing to rise.
During the conference call, CoreWeave clearly stated that after old GPU lease contracts expire, the hardware can be repurposed for other workloads such as inference, thereby continuing to maximize asset value.
Then, CoreWeave made a crucial statement:
"So when an initial contract ends, the cluster no longer has any leverage, and we are free to recontract that cloud infrastructure or offer it to the market." In other words, when the initial contract expires, the cluster is free of any associated leverage, allowing CoreWeave to either renegotiate contracts for this cloud infrastructure or offer it to the open market.
A more grounded translation of this statement would be:
When the first/initial contract ends, the financing obligations associated with this GPU cluster have typically been largely covered or repaid by the revenue from that initial contract. Therefore, CoreWeave can re-lease this now highly deleveraged asset, with subsequent income no longer bearing the heavy burden of capital recovery required previously.
This is precisely the most compelling aspect of the Neocloud business model.
A GPU cluster can be viewed as having two distinct lifecycle phases. The first phase is the Initial Contract, where customers sign a relatively long-term agreement. The leasing revenue generated during this stage primarily serves to cover the leveraged portion of capital expenditures (CapEx). The second phase is fundamentally different: after the contract expires, the GPUs are not scrapped but can continue to be leased out. Regarding this segment, CoreWeave specifically noted:
"In a market where new capacity is supply-constrained and costs are rising, AI cloud infrastructure in production is a scarce, valuable asset…increasingly we are seeing longer utilization at higher prices, offering the potential for significant further upside." In a market constrained by limited new capacity supply and rising costs, AI cloud infrastructure in production environments represents a scarce and valuable asset. We are increasingly observing extended utilization periods at higher price points, creating significant potential for further upside.
By the way, this passage can be simply summarized as follows:
Upon expiration of the initial contract, renewal contracts will see significant price increases.
This explains why CoreWeave’s business model—and by extension, the Neocloud model—is far more attractive than the market currently imagines. The key metric for Neocloud is not merely the revenue generated from the first GPU contract, but rather how much additional profit the GPUs can generate, and for how many years, after completing their initial deleveraging.
Looking at the A100, a product launched six years ago (in 2020, when the world was still grappling with the pandemic and large-scale AI training probabilities had not yet emerged), it is evident that the 'second lifecycle' of GPU clusters is exceptionally long. Consequently, the true return on invested capital (ROIC) for Neocloud is staggering.
It is clear that Elon Musk, who plans to quadruple computing power to build an 8GW data center by 2027, understands this dynamic. SpaceX is already evolving into a Neocloud-style company (note: this observation is not intended as mockery).
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more
Comment (1)
to post a comment