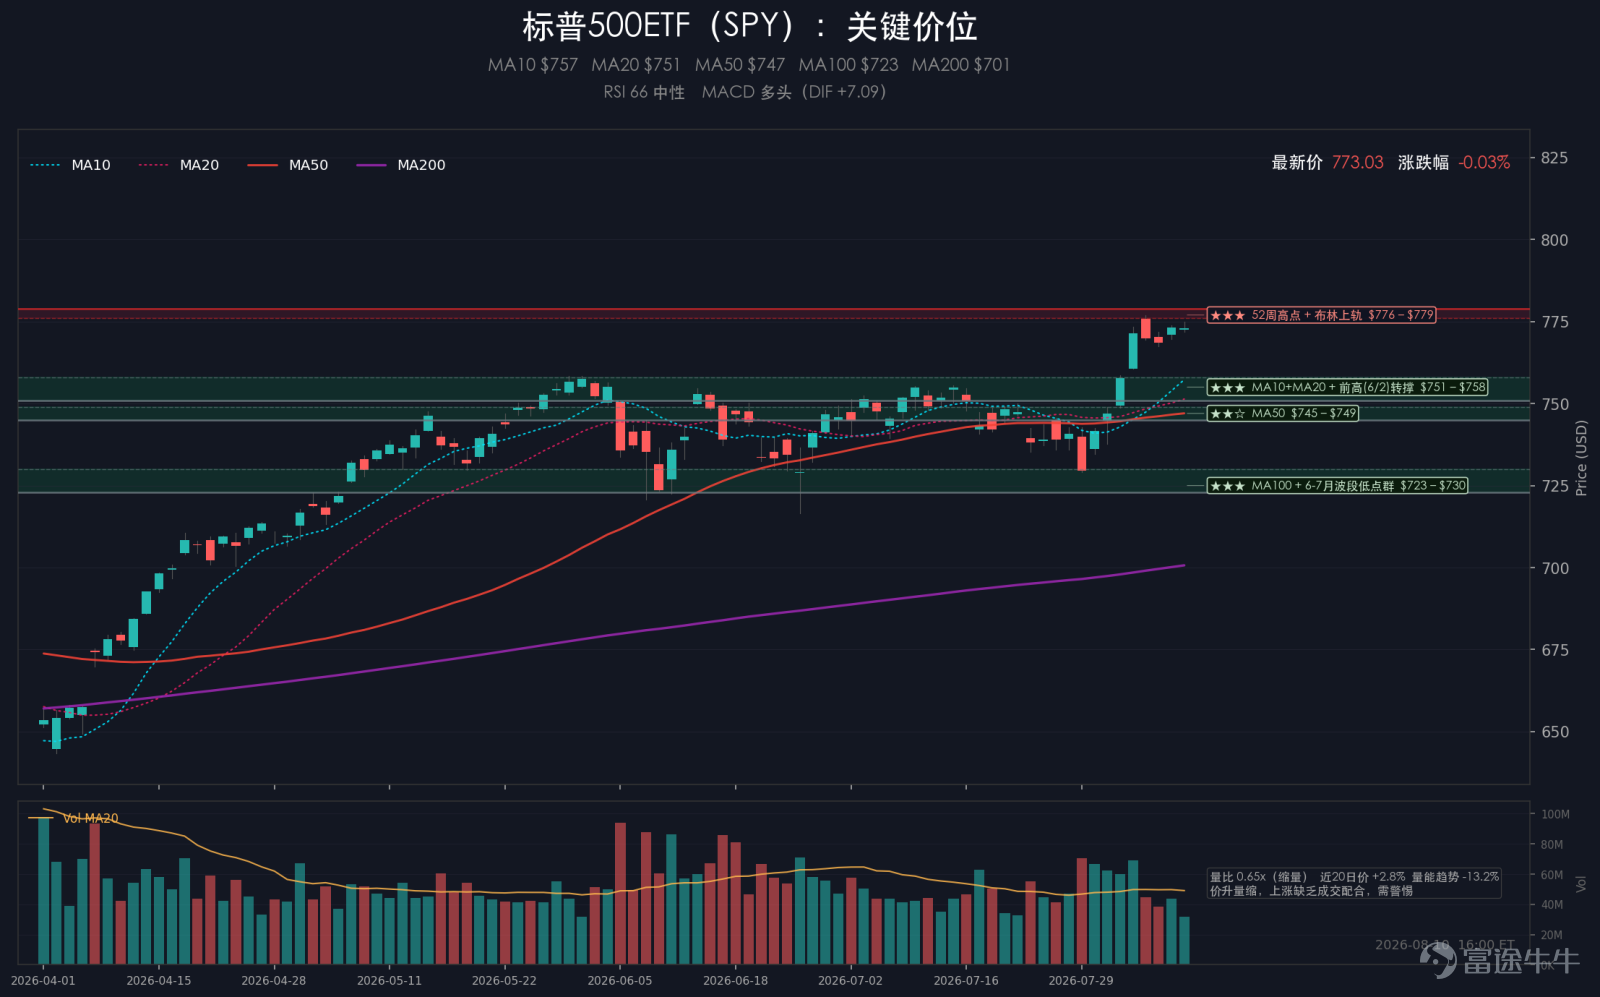
US-Iran tensions flare up again: How will Strait risks impact assets?
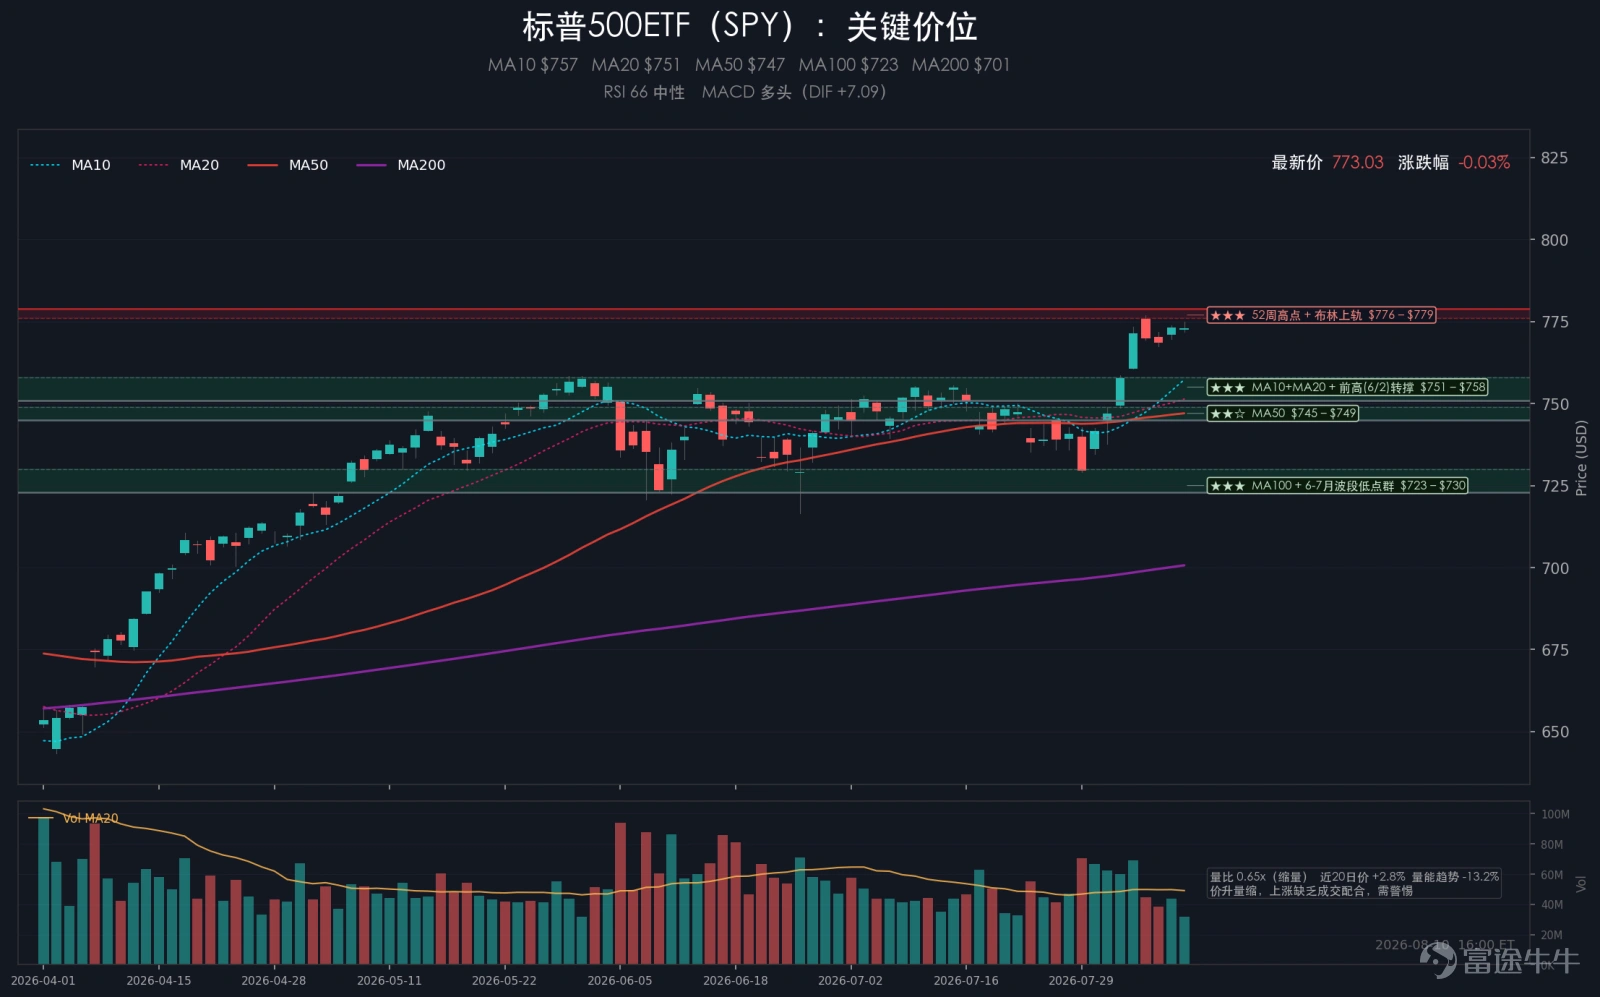
Wall Street Brief (August 11): U.S. equities pulled back slightly from recent highs on Monday, volatility ticked up from low levels, and single-stock trading activity remained robust; surging oil prices intensified rate concerns, while AI financing entered a new phase
Summary: U.S. equities edged lower from recent highs on Monday, with the S&P 500 down 0.06%, the Nasdaq down 0.32%, the Dow Jones down 0.11%, and the Russell 2000 down 0.56%. All four major indices posted modest declines, but small-cap stocks underperformed more noticeably, indicating that capital flows did not continue expanding into higher-beta segments. The VIX rose to 15.46, up 3.76% on the day—volatility has begun rising from low levels but remains outside the stress zone, and single-stock trading activity has not meaningfully cooled. Renewed setbacks in talks over reopening the Strait of Hormuz drove a sharp spike in oil prices, heightening inflation and interest rate concerns, prompting equities to pause at elevated levels. On the sector front, energy and oil services stocks gained notably, healthcare showed relative resilience, while semiconductors, AI hardware, and real estate-related names faced pressure. Across major asset classes, the 10-year U.S. Treasury yield climbed to 4.699%, up 0.84%; gold settled at $4,389.285, up 1.10%; crude oil closed at $82.30, up 6.77%; Bitcoin ended at $64,016, down 1.63%; and the U.S. Dollar Index rose to 99.8103, up 0.21%.
I. Major Events
1. Talks to Reopen the Strait of Hormuz Face Fresh Setbacks
Iran continues to include demands related to sanctions relief, unfreezing assets, war reparations, and military actions in negotiations over reopening the Strait of Hormuz, while Trump publicly pushed back against Iran’s demands for war compensation. Markets had previously anticipated a resumption of shipping through the corridor and easing oil price pressures, but negotiation difficulties have resurfaced. Given the Strait of Hormuz’s critical role in global crude oil transportation, stalled talks heighten supply risks and could once again influence inflation expectations and Treasury yields. With oil prices now elevated, energy stocks are better positioned to attract capital, while high-valuation growth stocks and rate-sensitive assets face greater downside pressure.
2. NVIDIA Partners with Wall Street to Launch AI Financing Platform
NVIDIA announced a partnership with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs, and KKR to mobilize over $500 billion in third-party capital for AI infrastructure. The funds will be allocated to data centers, chips, power infrastructure, and related computing capacity. AI development is no longer just about chip procurement—it has entered a phase requiring heavier capital investment and greater reliance on external funding. While long-term demand remains intact, markets are beginning to question whether these investments can translate into cash flows quickly enough, contributing to downward pressure on NVIDIA shares that day.
II. Major Trends
In the short term, QQQ has risen 5.68% over two weeks, remaining the strongest among major index ETFs; however, the Russell 2000 posted the largest decline on Monday, signaling weakening follow-through strength in high-beta assets. Over a three-month horizon, DIA is up 9.03%, continuing to outperform QQQ’s gain of 1.47%, reflecting the persistent medium-term advantage of traditional large-cap stocks.
Market breadth remains solid over the three-month period, with RSP up 8.32%, outpacing SPY’s 5.07% gain. However, over the past two weeks, SPY rose 4.59%, exceeding RSP’s 2.34%, indicating that recent gains are once again concentrating in large-cap names.
MAGS declined 0.83% over three months but gained 9.57% over the past two weeks, showing a rapid short-term recovery among leading tech names. Yet this rebound hasn’t fully reversed their underperformance on the three-month timeframe, leaving the market in a state of short-term recovery amid medium-term divergence.
III. Market Sentiment
VIX closed at 15.46, up 3.76% on the day, as volatility began rising from low levels. The CNN Fear & Greed Index stood at 64, unchanged from the prior reading, indicating sentiment remains relatively positive. The CBOE total put/call ratio was 0.80, with the index options put/call at 1.01 and the equity options put/call at 0.72. Demand for index options protection has returned to around 1, suggesting investors are adding defensive positions amid elevated market volatility; equity options activity remains upbeat, with no notable cooling in single-stock trading.
IV. Market Scan
1. Index ETFs
S&P 500 ETF SPY fell 0.03%, Nasdaq-100 ETF QQQ dropped 0.30%, Dow Jones ETF DIA declined 0.12%, and Russell 2000 ETF IWM slid 0.52%. All four major index ETFs showed weakness, with small caps lagging most noticeably. The market isn’t experiencing broad-based selling but is instead reducing elasticity and risk exposure from elevated levels. Country-specific ETFs saw no significant gains—Canada’s EWC edged up 0.33%, while South Korea’s EWY and Australia’s EWA underperformed, lacking the prominence of dominant U.S. equity themes.
2. Sector Performance
Energy sector ETF XLE surged 4.66%, and healthcare ETF XLV rose 1.67%, making them the day’s standout performers. Rising oil prices directly benefited energy stocks, while healthcare offered relative defensive appeal during market consolidation at elevated levels. Real estate ETF XLRE fell 1.29%, and utilities ETF XLU declined 1.10%, as higher interest rates weighed on yield-oriented assets.
At the sub-industry level, oil services ETF OIH climbed 5.94%, and oil & gas exploration & production ETF XOP gained 5.73%, both closely tracking the crude oil rally. Within tech, performance wasn’t uniformly weak: cloud computing ETF SKYY rose 2.95%, cybersecurity ETF CIBR advanced 2.81%, and software ETF IGV gained 2.26%. However, semiconductors (SMH) dropped 2.28%, and DRAM-related names fell 1.98%, reflecting heavier pressure on AI hardware and memory segments. Homebuilding ETF XHB declined 2.31%, also illustrating the impact of rising rates on the housing sector.
3. The Magnificent Seven Tech Stocks
Netflix rose 2.90%, NVIDIA fell 2.86%, Microsoft gained 1.21%, Google advanced 0.67%, Meta increased 0.48%, and Tesla rose 0.70%. Mega-cap tech stocks did not all weaken together, but internal divergence was clear: software, streaming, and platform names held up relatively well, while AI chip heavyweights faced headwinds from concerns over funding structures and capital expenditure outlooks.
4. Chinese ADRs
Tencent Music rose 3.88%, Alibaba gained 3.04%, and Futu slipped 0.29%. Chinese ADRs overall outperformed major U.S. indices, driven mainly by rebounds in platform and online entertainment names, though the strength has yet to broaden across the entire group. Futu’s slight decline reflects that brokerages and other high-beta trading-related assets have not kept pace.
5. Cryptocurrencies
Bitcoin fell 1.63%, MicroStrategy (MSTR) dropped 2.68%, Riot Platforms (RIOT) slid 5.46%, and Circle (CRCL) rose 0.57%. Crypto-related assets showed mixed performance, with miners under greater pressure while stablecoin platforms remained relatively steady. The pullback in Bitcoin prices hasn’t formed an independent market theme; instead, it reflects synchronized cooling among high-beta assets amid shifting interest rate expectations and risk appetite.
$S&P 500 Index (.SPX.US)$ $SPDR S&P 500 ETF (SPY.US)$ $NASDAQ 100 Index (.NDX.US)$ $Invesco QQQ Trust (QQQ.US)$ $Dow Jones Industrial Average (.DJI.US)$ $State Street® SPDR® Dow Jones Industrial Average® ETF Trust (DIA.US)$ $Russell 2000 Index (.RUT.US)$ $iShares Russell 2000 ETF (IWM.US)$ $Roundhill Magnificent Seven ETF (MAGS.US)$ $USD (USDindex.FX)$ $U.S. 10-Year Treasury Notes Yield (US10Y.BD)$ $iShares 20+ Year Treasury Bond ETF (TLT.US)$ $XAU/USD (XAUUSD.CFD)$ $SPDR Gold ETF (GLD.US)$ $CBOE Volatility S&P 500 Index (.VIX.US)$ $CME-Bitcoin RR Futures (SEP6) (BTCmain.US)$ $iShares Ethereum Trust ETF (ETHA.US)$ $NVIDIA (NVDA.US)$ $Tesla (TSLA.US)$ $Meta Platforms (META.US)$ $Amazon (AMZN.US)$ $Alphabet-C (GOOG.US)$ $Microsoft (MSFT.US)$ $Apple (AAPL.US)$
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments
to post a comment
5