Simultaneous pressure on the Red Sea and the Strait of Hormuz drives international oil prices higher
Bitget UEX Daily Report | Trump says U.S. military has 100% control of the Strait of Hormuz; oil prices surge, stoking inflation concerns; U.S. equities dip slightly with tech under pressure (August 11, 2026)


I. Key Headlines
Federal Reserve Updates
Markets are focused on this week’s inflation data; rate hike expectations remain influenced by both employment trends and oil prices.
Following the significantly weaker-than-expected July nonfarm payrolls report, markets have substantially reduced the probability of a near-term rate hike.
This week will see the release of the Consumer Price Index (CPI) and Producer Price Index (PPI), which will be critical for pricing the next policy move.
Oil prices surged sharply amid the impasse over the Strait of Hormuz, potentially reigniting inflation expectations.
Market ImpactWeakening employment data and rising oil prices are creating conflicting signals, leaving the Fed’s near-term path uncertain and heightening market sensitivity to incoming data.
Trump claimed that US forces have 100% control over the Strait of Hormuz, leading to a significant rise in oil prices.
Trump stated that the only force currently controlling the Strait of Hormuz is the U.S. Navy, whose blockade is 'impenetrable'—like a 'steel wall.' The entire strait has been cleared of mines and remains open to non-Iranian vessels, though access to Iranian ports is prohibited.
Trump also demanded that Iran compensate for casualties and losses caused by related conflicts, adding a new variable to negotiations over reopening the strait.
Iran, meanwhile, reiterated its conditions for reopening the strait and said it is close to finalizing an agreement with Oman on a new shipping route.
Market ImpactUncertainty over actual navigation through the strait persists, driving a sharp rebound in oil prices and reigniting inflationary pressures and geopolitical risk premiums, intensifying short-term volatility in energy markets.
U.S. stocks pulled back on Monday, with divergence between the tech and energy sectors.
Amid inflation concerns triggered by rising oil prices, the three major U.S. equity indices closed slightly lower.
IntelAnnounced a potential sale of $15 billion in stock to support AI and manufacturing operations, weighing on its share price.
Stocks such as Berkshire Hathaway, which reported better-than-expected earnings, held up relatively well.
Market ImpactGeopolitical tensions and inflation expectations are driving market sentiment, prompting capital rotation between energy and tech sectors, with overall investor caution prevailing.
Spot goldApprox. USD 4,414/oz, +0.6%
SpotSilverApprox. USD 65/oz, +0.2%
WTI Crude OilApprox. USD 82.2/bbl, +0.07%
Brent crudeApprox. USD 83.98/bbl, +0.12%
US Dollar Index (DXY)Approx. 99.75, -0.06%
Driver AnalysisTrump claimed that the U.S. military maintains 100% control over the Strait of Hormuz and continues its blockade. Combined with ongoing disagreements between the parties over compensation, the outlook for reopening the strait remains uncertain, driving a significant rise in crude oil prices. Gold has shown relative restraint as it balances stronger dollar pressure against safe-haven demand. The asset linkage logic is as follows: geopolitical deadlock → rising oil prices → higher inflation expectations → USD support, while risk assets face downward pressure. Short-term commodity volatility will heavily depend on actual developments regarding navigation through the strait and this week’s inflation data.
BTCApprox. USD 64,037, -1.55%
ETHApprox. USD 1,874, +2.12%
Total cryptocurrency market capitalizationApprox. USD 2.27 trillion, -0.4%
Market liquidation situationTotal liquidations in the past 24 hours: USD 205 million, including USD 59.25 million from short positions
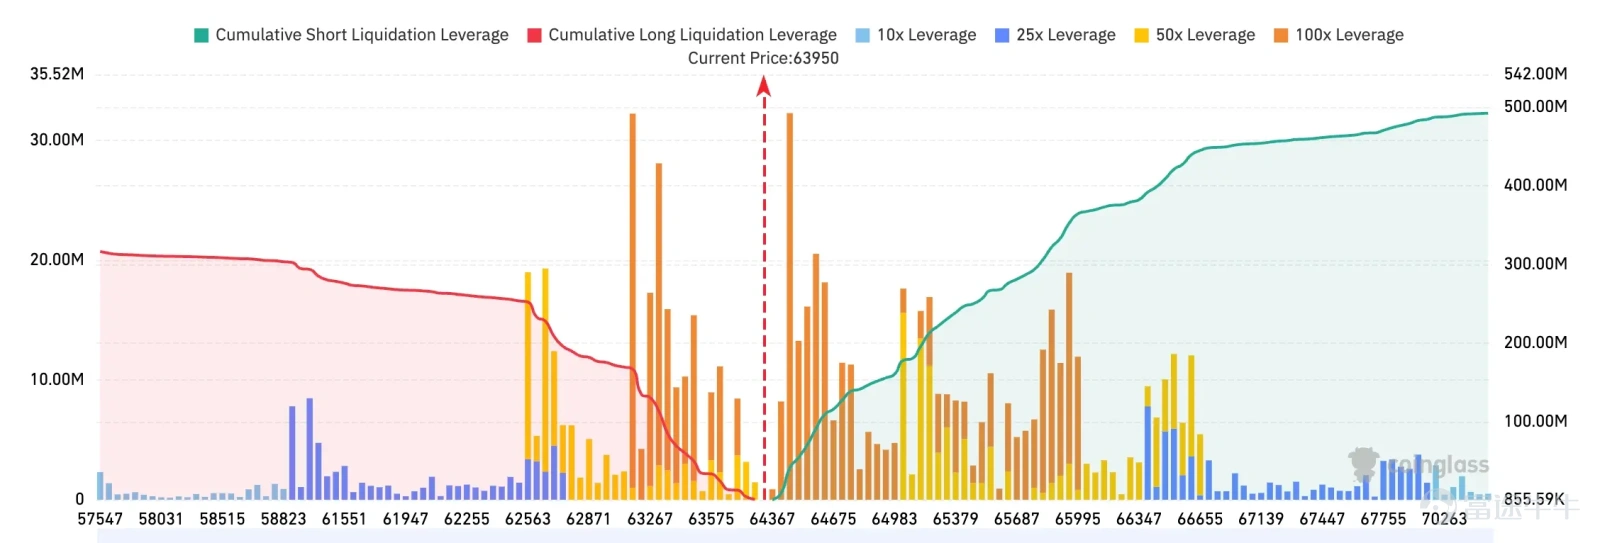
Bitget BTC/USDTLiquidation MapBitcoin is currently trading around $63,950. There is a dense cluster of long liquidations near the $63,300–$63,700 range. A drop below $63,500 could trigger cascading long liquidations. On the upside, short liquidation pressure is evident between $64,300 and $65,000; a breakout above $64,400 may further fuel a short squeeze, leading to elevated short-term volatility risk.
Spot ETF net inflows/outflowsBitcoin spot ETFs recorded a net outflow of $91 million over the past 24 hours.
Driver AnalysisRising oil prices and heightened geopolitical uncertainty have slightly dampened risk appetite, keeping the broader crypto market in a high-level consolidation range. Bitcoin is holding above $64,500, while Ethereum shows limited upside elasticity. Continued net inflows into ETFs provide underlying support, and leveraged liquidation volumes remain manageable. On the macro front, weakening labor market data offsets upward oil price pressures, suggesting crypto may continue trading in a range in the near term. Market participants are closely watching this week’s inflation data for its implications on liquidity expectations.
Dow Jones Industrial AverageClosed at approximately 53,976 points (-0.1%), posting a slight pullback.
S&P 500Closed at approximately 7,753 points (-0.1%), retreating from a record high.
NasdaqClosed at approximately 26,605 points (-0.3%), under pressure in the tech sector.
NVDAApproximately $217.55 (-2.86%)
AAPLApproximately $308.26 (-1.62%)
MSFTApproximately $506.06 (+1.21%)
GOOGL: Approximately USD 357.52 (+0.91%)
AMZN: Approximately USD 278.09 (+1.32%)
META: Approximately USD 594.92 (+0.48%)
TSLA: Approximately USD 330.88 (+0.70%)
Performance Summary and Driver AnalysisU.S. equities experienced a modest pullback on Monday, with the Nasdaq seeing relatively larger declines. NVIDIA and Apple faced notable pressure, while Microsoft, Amazon, Google, Meta, and Tesla posted gains, reflecting continued divergence within the tech sector. A sharp rise in oil prices reignited inflation concerns, partially offsetting earlier rate-cut expectations spurred by weak employment data. Investors are weighing geopolitical risks against macroeconomic data, with capital flowing toward cloud and software names exhibiting higher earnings visibility.
Energy
Representative stocks: Crude oil and energy-related equities broadly strengthened, with some names leading the gains.
Drivers: Trump claimed the U.S. military maintains '100% control' over the Strait of Hormuz and will sustain its blockade. Combined with ongoing disagreements over compensation, the actual resumption of shipping through the strait remains uncertain. Markets have repriced in a geopolitical risk premium, driving a significant rally in oil prices and directly boosting the energy sector. Near-term performance remains highly dependent on negotiation progress and the actual restoration of transit through the strait.
Semiconductor
Representative stocks: NVIDIA (-2.86%), with related semiconductor stocks broadly retreating.
Drivers: Oil prices surged significantly due to the Hormuz impasse, reigniting market concerns over renewed inflationary pressures and their potential impact on future liquidity conditions and the Federal Reserve’s policy trajectory. Although weaker-than-expected nonfarm payroll data had previously supported sentiment recovery, the rapid shift in macro narratives triggered profit-taking and position adjustments in high-valuation AI hardware names, placing downward pressure on the broader sector.
Tech Software/Cloud
Representative stocks: Microsoft (+1.21%) and Amazon (+1.32%) showed relatively resilient performance.
Key drivers: Amid escalating geopolitical tensions and inflation uncertainty, capital has favored companies that have already monetized revenue and demonstrated clear commercialization pathways. The sustained strong growth of Azure and AWS has endowed cloud giants with relatively defensive characteristics, creating a stark divergence from the highly volatile and richly valued hardware sector.
1. NVIDIA (NVDA) – Down nearly 3%, under pressure in the semiconductor space
Event summaryNVIDIA’s share price declined approximately 2.86% to USD 217.55, making it one of the weaker performers among mega-cap tech stocks. Markets are concerned that the standoff in the Strait of Hormuz could push oil prices higher, reigniting inflation expectations and thereby impacting future liquidity conditions and the Federal Reserve’s policy trajectory.
Market AnalysisEarlier-than-expected weak non-farm payroll data had temporarily boosted risk appetite and partially repaired sentiment toward AI hardware. However, the sharp rise in oil prices quickly shifted the macro narrative, prompting investors to reassess interest rate expectations and valuation pressures. As a high-valuation, high-beta leader in computing power, NVIDIA is often among the first to come under pressure when inflation concerns resurface. While the long-term thesis for AI compute demand remains intact, its share price is highly sensitive in the near term to macro liquidity and rate expectations, with profit-taking and position adjustments acting in tandem.
Investment InsightWatch this week’s CPI and PPI data for their impact on inflation expectations, as well as whether major customers’ capital expenditure guidance can continue to support the demand narrative. Volatility may intensify around the data releases.
2. Apple (AAPL) – Down over 1.6%, lagging relatively
Event summaryApple’s share price fell approximately 1.62% to USD 308.26, underperforming most other tech giants and continuing its recent trend of relative underperformance.
Market AnalysisDuring periods of narrowing risk appetite, when capital flows prefer cloud and software names, consumer electronics and hardware firms typically see limited upside elasticity. Although Apple benefits from robust cash flows and a strong services moat, the market is currently more focused on marginal shifts in hardware demand and whether the rollout of AI features will meaningfully accelerate its replacement cycle. Compared with companies already delivering tangible cloud revenue growth, Apple has attracted comparatively less investor interest in the current macro environment.
Investment InsightContinued monitoring is needed on upcoming product cycles, the sustainability of services growth, andAppleThe substantive impact of AI features such as Intelligence on users' willingness to upgrade.
3. Microsoft (MSFT) – Up over 1%, relatively resilient
Event summaryMicrosoft’s share price rose approximately 1.21% to $506.06, demonstrating resilience amid a broader tech sector pullback and emerging as one of the relatively more defensive large-cap tech stocks.
Market AnalysisMicrosoft is viewed by investors as a relatively high-conviction play in the current tech landscape, supported by Azure cloud business growth that continues to exceed expectations and tangible progress in AI commercialization. In an environment marked by rising oil prices, inflation concerns, and declining risk appetite, cloud and software giants with clear revenue realization pathways tend to command a relative premium—a stark contrast to hardware names under pressure due to valuation and macro sensitivity.
Investment InsightEarnings delivery capability remains the core criterion for market pricing at present. Key focus areas going forward include whether cloud revenue growth can continue to offset capital expenditures and how visible AI-related revenue contributions become.
4. Amazon (AMZN) – Up over 1.3%, following the cloud narrative
Event summaryAmazon’s share price increased approximately 1.32% to $278.09, significantly outperforming the hardware segment and extending its relative strength driven by cloud business momentum.
Market AnalysisSustained high growth in AWS and long-term investment in AI infrastructure continue to underpin the stock. Amid escalating geopolitical and inflation uncertainties, capital is favoring assets with realized revenues and clear commercialization roadmaps. Amazon thus exhibits strong defensive-growth characteristics, diverging from highly volatile, richly valued hardware stocks.
Investment InsightKey watchpoints include whether AWS growth can continue to absorb elevated capital expenditures and the resilience of retail and advertising segments amid macro volatility. The alignment between cloud capabilities and AI monetization remains central to medium- to long-term valuation.
5. Tesla (TSLA) – Modestly higher
Event summaryTesla’s share price rose approximately 0.70% to $330.88, showing relatively stable performance without significant volatility.
Market AnalysisTesla embodies multiple narratives—electric vehicles, autonomous driving, and humanoid robotics. Its high-beta nature gives it pronounced upside elasticity when risk appetite rebounds quickly, but its gains are often constrained during periods of declining risk appetite or heightened macro uncertainty. The market is currently cautious amid rising oil prices and inflation concerns. Although Tesla has not seen a significant pullback, it has failed to sustain its previous strength. The long-term narrative remains intact, but short-term pricing is increasingly driven by sentiment and macro liquidity conditions.
Investment InsightThe stock exhibits high volatility and requires continuous monitoring of actual delivery data, progress in autonomous driving, andOptimusthe pace of commercialization to validate the realization timeline of its long-term narrative.
1. The U.S. Securities and Exchange Commission (SEC) will hold an open meeting at 10:00 a.m. Eastern Time on August 14 to consider whether to issue a new rule proposal that would create a tailored registration framework for specific investment contracts involving crypto assets.
2. A whale transferred 1,275 BTC (USD 81.5 million): 500 BTC (USD 32 million) to FalconX, 274 BTC (USD 17.5 million) to Cumberland’s OTC trading desk, and 500 BTC (USD 32 million) to a new address (potentially destined for Galaxy Digital).
3. Futures whale 'First Set 10 Big Goals' (@jasonleo) posted that his medium- to long-term trend outlook remains unchanged, and he still views the current price zone as a cyclical bottom. Barring an extreme structural collapse, he maintains his estimate for this Bitcoin cycle’s bottom around USD 58,000. He noted that reducing two-thirds of his position near his cost basis of approximately USD 64,000 was not a directional shift but a proactive risk management measure to preserve capacity for extreme scenarios. If price action aligns with his expectations, he plans to gradually repurchase the previously reduced positions.
4. Strategy CEO Phong Le stated the company has adjusted its strategy and currently holdsUSD 4.75 billion in cash,sufficient to cover approximately 2.7 years of preferred dividend payments. Le said he initially believed investors would highly value Bitcoin for its liquidity and long-term appreciation potential, but institutional investors place greater emphasis on cash holdings, prompting the strategic shift. Le positions Strategy as a financial platform built around Bitcoin—not merely a leveraged Bitcoin proxy—with the ambition to become the 'JPMorgan of digital finance.' He envisions an ecosystem akin to Apple’s iPhone, where other firms can build financial products atop Strategy’s offerings. Le added that DeFi could expand this ecosystem and ultimately channel more capital into Bitcoin. The company currently holds approximately 840,000 BTC (about 4% of Bitcoin’s eventual supply), and Le remarked, 'We are now the bellwether—the central bank of Bitcoin.'
5. Bitwise Head of Research Ryan Rasmussen stated that as the stablecoin market expands toward a multi-trillion-dollar scale,CircleIts value is undervalued by the market. Rasmussen expects the stablecoin market to grow from approximately $300 billion to between $3 trillion and $5 trillion. Circle holds a first-mover advantage due to its existing market share as U.S. stablecoin regulations take shape. He believes Circle will not only become a stablecoin giant but also a payments powerhouse—the payment infrastructure it is building will play a critical role in a stablecoin-driven financial system, yet investors remain overly focused on its reserve management business.
6. Robert Mitchnick, Head of Digital Assets at BlackRock, stated that Bitcoin market sentiment has shown a clear but subtle improvement over the past month, and Bitcoin’s correlation with U.S. equities is weakening—a healthy sign for the thesis that Bitcoin serves as a portfolio diversifier and a hedge against tail risks. He pointed out that during the sharp July correction in AI-related stocks, Bitcoin significantly outperformed, illustrating this decoupling trend. Despite Bitcoin having declined nearly 30% year-to-date and roughly 50% compared to a year ago, ETF investors have continued buying—U.S. spot Bitcoin ETFs recorded $853.5 million in inflows last week, marking their best weekly performance since mid-April, led by BlackRockIBITwhich contributed $693.7 million (over 80%), followed by Fidelity’s FBTC with $116.4 million. Bloomberg analyst Eric Balchunas noted that several funds registered net daily inflows following the exposure of the Coldcard vulnerability, adding, 'It’s hard not to see a causal relationship.'
7. According to informed sources,OpenAIhas completed an employee stock sale transaction worth approximately $7 billion as the company considers going public on Wall Street. Two informed sources said that in this employee share buyback, the ChatGPT developer did not bring in external investors but instead repurchased shares held by current and former employees itself. They added that the transaction valued OpenAI at $852 billion, consistent with its valuation in the most recent funding round. Large private AI firms periodically allow insiders to sell portions of their stakes to realize gains. In the past, OpenAI has brought in investors such as Thrive Capital and SoftBank Group to purchase shares from employees.
This week
United States
CPI and PPI inflation data
⭐⭐⭐⭐⭐
focus on
global
Progress on Hormuz Strait navigation
⭐⭐⭐⭐⭐
Tuesday, August 11
U.S. weeklyADPchange in employment and July existing home sales;
★★★★ Super Micro Computer (SMCI)、CoreWeave、LumentumAfter-hours earnings release, with key focus on AI server order conversion, data center ramp-up/power/financing costs, and demand for 800G/1.6T optical modules and data center optical communications;
Sea, Tencent Music before the market open;CAVAAfter hours.
Wednesday, August 12
★★★★★ The U.S. releases July CPI data (market expects headline YoY ~3.4%, prior 3.5%; core YoY ~2.5%, prior 2.6%; MoM headline ~0.1%, core ~0.2%), taking over from last week’s NFP as this week’s most critical macro data, directly influencing September Fed rate hike pricing (currently implied probability ~44%).
Tencent reports earnings (focus areas: gaming, advertising, fintech, and AI capex/HunYuan progress);
★★★★Coherent、Cisco、NEBIUSAfter-hours (and some pre-market) earnings to test demand for AI networking equipment and high-speed optical communications; API/EIAcrude oil inventories, with IEA and OPEC monthly reports densely scheduled for release.
Thursday, August 13
The U.S. releases July PPI and weekly initial jobless claims;
★★★★★ Western Digital (SanDisk) Investor Day (evening Beijing time), focusing on NAND supply-demand dynamics, capital expenditure, High Bandwidth Flash (HBF) roadmap, and long-term margin targets—setting the tone for the memory sector;
Google's Made by Google event (Pixel 11 series and wearables, with deep Gemini integration);
Fed officials Hammack and Barkin to speak;
★★★★ Applied Materials (AMAT) after-hours earnings report, with focus on wafer fabrication,DRAM, advanced packaging, and guidance on semiconductor equipment spending; concurrent earnings from JD.com, SMIC, Hua Hong, and other China-concept/semiconductor names.
Friday, August 14
★★★★ US July retail sales MoM, preliminary August University of Michigan consumer sentiment index, and 1-year inflation expectations—testing consumer resilience following signs of labor market cooling;
Deadline for US institutional Q2 13F filings—monitor shifts in large funds’ allocations across tech, energy, and other sectors.
*This week’s key US equity themes center on the July inflation data 'stress test' (CPI following nonfarm payrolls, with PPI and retail sales jointly validating cost pressures and consumption), Fed officials’ signals on the September policy path, and a dense slate of AI infrastructure (CoreWeave, Lumentum, SMCI, Coherent, Cisco, Applied Materials) and memory (Western Digital Investor Day) earnings/events providing validation.
Note: Following last week’s unexpected 23,000 decline in nonfarm payrolls, rate hike expectations have cooled. If CPI and core CPI continue to ease while consumer spending remains resilient, the soft-landing trade and growth stocks could extend their rally; otherwise, tightening expectations may re-accelerate, putting pressure on high-valuation sectors. Market volatility is expected to intensify, with a key focus on how markets price data releases and AI-related guidance that either beat or fall short of expectations.
Analysts broadly agree that Trump’s claim that U.S. forces have 100% control over the Strait of Hormuz and will maintain the blockade has left the outlook for reopening the strait uncertain, driving a sharp rise in oil prices and reigniting inflation concerns. This partially offsets the dovish shift prompted by recent weak employment data. U.S. equities saw a modest pullback, with continued divergence within the tech sector—cloud and software stocks held up relatively well, while hardware names came under pressure. The crypto market remained range-bound at elevated levels, supported by ETF inflows. The prevailing consensus is that geopolitical risks and inflation data will dominate the near-term narrative, likely amplifying market volatility.
Disclaimer: The above content has been compiled by AI-powered search and verified only by human review prior to publication. It does not constitute any form of investment advice. Data presented herein may inevitably contain inaccuracies; please refer to real-time market data for accuracy.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comments
to post a comment
1
1