HK Stock Market Barometer | HK stocks continue to consolidate! How to capture structural market oppo
Value Investors Who 'Run Insurance Companies'—A Case Study on Duan Yongping and Buffett's Options Investing
On April 9, 2026, Duan Yongping wrote on Xueqiu: 'My Pop Mart insurance company is officially open for business.' By 'insurance company,' he referred to selling put options (Sell Put): collecting premiums upfront while committing to buy the stock at an agreed-upon price if assigned. This analogy is vivid because it reframes an options trade as the most basic form of an insurance business—income first, payout obligation later.
Aside from Duan Yongping, Buffett is also a master of using options. Starting from Pop Mart, this article will illustrate—through several of Buffett’s classic trades—that seemingly similar options-based instruments may actually occupy diametrically opposed economic positions.
I. First, Place the Four Types of Instruments Back on Their Proper Coordinates
II. Why Do Some Value Investors Excel at Using Options?
III. Pop Mart: Wheel Strategy or Covered Strangle?
IV. Buffett as an options seller: Premiums reflect position-sizing capacity
V. Buffett as an options buyer: This isn’t about 'running an insurance company'
VI. Where Duan Yongping and Buffett truly differ
VII. What ordinary investors can genuinely learn
Conclusion: Options merely codify your understanding into a contract
This article discusses only investment instruments and publicly available cases and does not constitute investment advice for any securities, options, or other financial products. Please assume all risks yourself.
I. First, place the four types of instruments back into their proper context
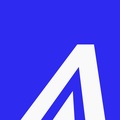
Value investing does not equate to mechanically 'buying and holding forever.' Investors can express the same fundamental view through different contracts: at what price they are willing to buy, at what price they are willing to sell, how long they are willing to wait, and how much loss they can bear in the worst-case scenario. However, before analyzing these tools, one must first clarify whether they are acting as an options seller or an options holder.
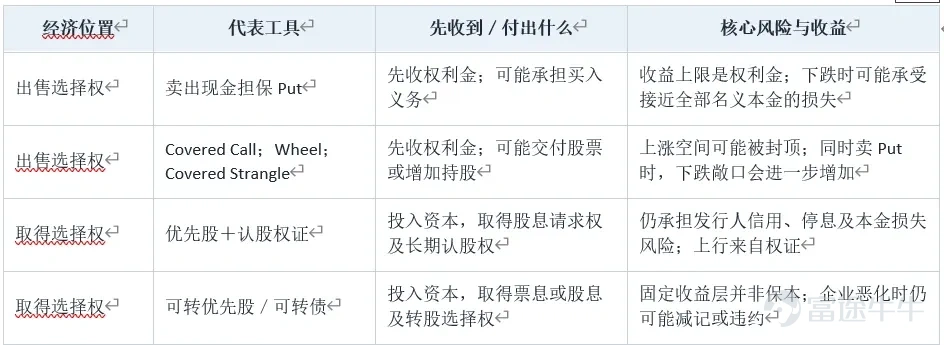
Source: Prepared by the author
Core judgment What truly unifies these four types of instruments is not 'running an insurance company,' but rather embedding price, duration, and risk-bearing capacity directly into the contract.
II. Why Some Value Investors Excel at Options
The general public treats options as leveraged gambling instruments—small bets for big payoffs, expiring worthless, or last-day rallies. But in the hands of Buffett, Duan Yongping, and others, options serve as 'pricing tools to execute value judgments,' with no speculative intent. There are several layers to this reasoning:
The strike price is not the margin of safety itself.
Selling a put with a $35 strike price indeed expresses the willingness to buy at $35. However, the margin of safety comes from the difference between intrinsic value and net purchase cost—not from the strike price alone. If the assessment of the company’s intrinsic value is wrong, the stock may still not be cheap—even if the strike price is significantly below the current market price.
Option premium is not free income for waiting.
Selling puts turns waiting into cash flow, but the seller simultaneously gives up part of their optionality: during the contract term, they must reserve capital or post margin to cover potential assignment obligations. If the stock price suddenly plummets, they cannot simply cancel the position like a limit order. The premium received is both income and compensation for capital commitment and tail risk.
Limit Buy Orders vs. Cash-Secured Puts: Five Key Differences
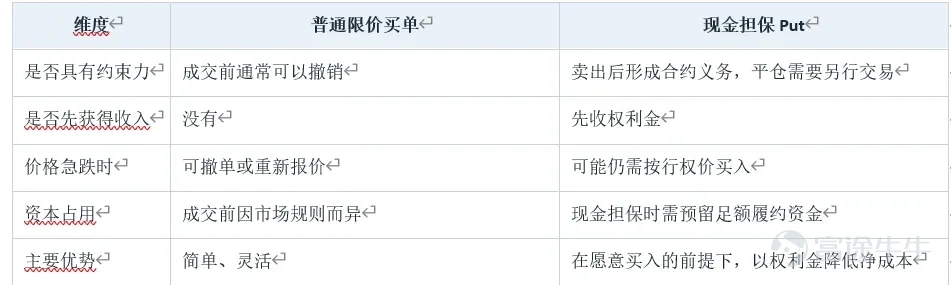
Source: Author's own compilation
High win rate does not equate to low risk.
The maximum profit from selling a put is the premium received. If the underlying asset drops to zero, the theoretical maximum loss per share is 'strike price minus premium.' This strategy often yields frequent small gains but infrequent, much larger losses. Win rate, payoff ratio, and expected return are three distinct concepts.
Risk boundary Selling puts can only serve as a position-establishing tool under the conditions of full cash collateral, predetermined position sizing, and willingness to accept assignment and hold the shares long-term. The contract itself does not prevent investors from adding to their positions nor does it assess whether the company is truly undervalued.
III. Pop Mart: Wheel or Covered Strangle?
How the standard Wheel works
The standard Wheel typically alternates between two positions: first, selling a cash-secured put; if the put is assigned, the investor acquires the underlying shares; then, using those shares as collateral, the investor sells a covered call; if the call is assigned, the shares are delivered at the strike price, returning the position to cash, and the cycle restarts by selling another put. It does not guarantee 'two fixed premiums per cycle,' as either leg may be repeated multiple times before assignment occurs.
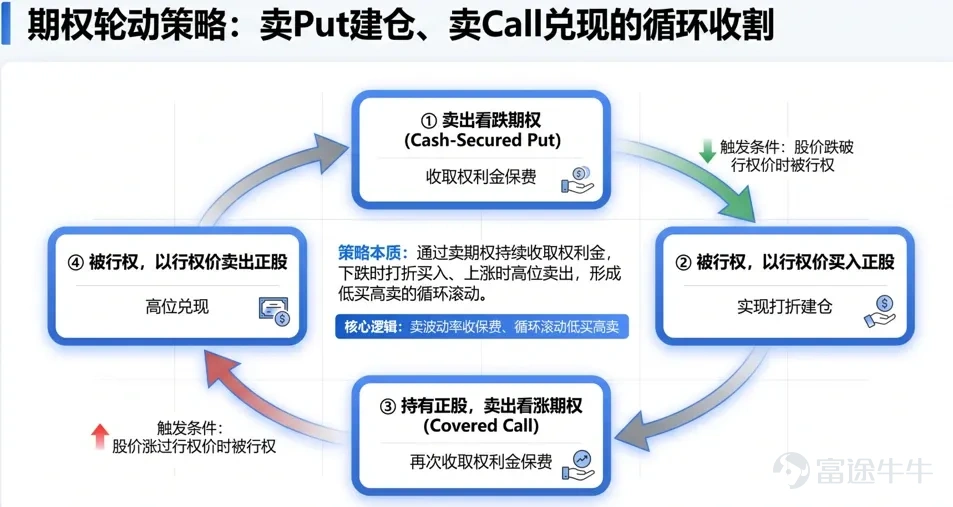
Source: Prepared by the author
Simultaneously selling puts and calls alters the risk profile
If an investor already holds the underlying shares and simultaneously sells a covered call and a cash-secured put, the more accurate term is a Covered Strangle (also known as a Covered Combination). This differs from the standard Wheel beyond terminology: if the put is assigned, the shareholding increases, potentially doubling the downside exposure compared to a standard Wheel; if the call is assigned, the existing shares are delivered at the agreed-upon price, capping upside potential.
What public disclosures can reveal
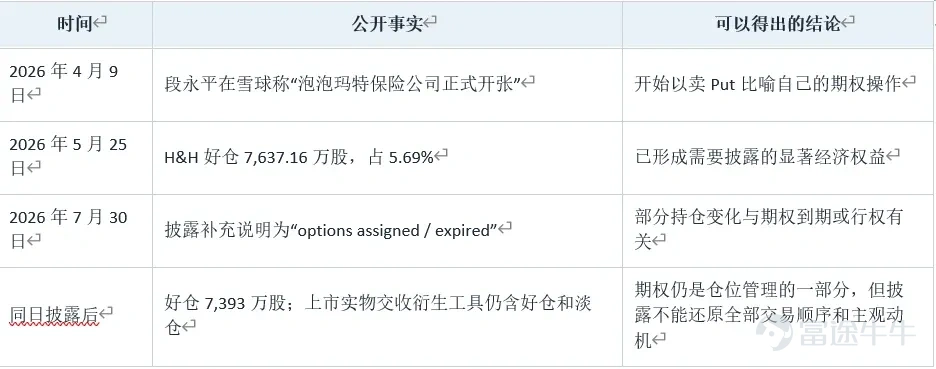
Source: Publicly available information, compiled by the author
Therefore, a more prudent statement is: Duan Yongping employed a combination of put-selling, holding the underlying shares, and call-selling in his Pop Mart position, exhibiting characteristics of both a Wheel framework and a Covered Strangle; however, based solely on public disclosures, it is not possible to reconstruct every position as a strict, continuous Wheel strategy.
Similarly, 'long-term bullish' and 'having the stock called away' are not logically contradictory, but the latter still represents a real economic transaction. At the moment an investor sells a covered call, they have already accepted that if the stock price exceeds the strike price, they may forgo potential gains from higher prices. It is not cost-free 'rent collection'—it is exchanging part of the upside potential for the immediate premium.
IV. Buffett as an Options Seller: Premiums Backed by Holding Capacity
This type most closely resembles 'selling insurance' and is also the easiest to replicate. Its core characteristics are:Only sell puts; if assigned, take delivery and hold long-term—never sell calls.—Options are 'paid limit orders to buy.'
Coca-Cola: Selling a put is a binding commitment to buy.
......
Full in-depth breakdown available exclusively on [Benying Official Website], with limited-time free access to more exciting content!
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comment (1)
to post a comment
6
2