US CPI data released Wednesday! Combined with major Hong Kong stock earnings reports, what should yo
Week Ahead | Inflation Takes Center Stage! US CPI Follows Weak Jobs Report; Tencent and JD.com Lead Wave of Chinese Tech Earnings, AI Supply Chain Giants Deliver Results
Key Events for the New Week
– After a Disappointing NFP, Inflation Data Takes Over—US CPI Could Shape September Policy Path
Following the unexpected drop in US July employment, market expectations for a Fed rate hike in September have cooled significantly. According to LSEG data, the implied probability of a September rate hike now stands at approximately 44%, down from before the jobs report release. Whether inflation data continues to cool will directly impact this probability.
The US July CPI will be released at 20:30 Beijing time on Wednesday. FactSet consensus forecasts show headline CPI year-over-year growth is expected to ease to 3.4% from June’s 3.5%, while core CPI year-over-year growth is projected to decline to 2.5% from 2.6%.
If both headline and core CPI come in below expectations, markets may further reduce bets on a September rate hike, potentially pressuring Treasury yields and the dollar lower, while growth stocks and gold could benefit. Conversely, stronger-than-expected data could force markets to reprice in tighter monetary policy, weighing on elevated US equity valuations.
Against the backdrop of weakening nonfarm payrolls, record highs in US equities, and investor sentiment reaching extreme optimism, this CPI release may carry significantly higher market sensitivity than in recent months.
– CPI, PPI, and the 'Retail Sales' Data Drop in Succession, Testing Cost and Consumer Resilience
Following the CPI release, U.S. July PPI will be published Thursday at 20:30 Beijing time. In June, final demand PPI declined 0.3% month-over-month but remained elevated at 5.5% year-over-year. Markets are closely watching whether businesses can pass through rising costs in raw materials, energy, and transportation to consumers.
On Friday at 20:30 Beijing time, U.S. July retail sales (month-over-month) will be released. As a key gauge of household spending, retail sales are often dubbed the 'terrifying data.' Subsequently, the University of Michigan’s consumer sentiment index and one-year inflation expectations will offer further insight into how high interest rates, energy prices, and slowing job growth are affecting household expenditures.
These three data releases will address three critical questions: Is inflation continuing to cool? Are corporate cost pressures easing? And can U.S. consumer spending remain resilient despite softening labor conditions? A combination of cooling inflation and stable consumption would support the ongoing soft-landing trade in U.S. equities; however, if inflation proves hotter than expected while consumption weakens, stagflation concerns could resurface.
– Tencent and JD.com lead the wave of China-concept earnings reports, with AI investment and profit realization taking center stage
$TENCENT (00700.HK)$ will release its second-quarter results on Wednesday and hold an earnings call at 20:00 Beijing time. The market will closely watch domestic and overseas gaming revenue, commercialization of Channels (WeChat Video Accounts) advertising, fintech business performance, as well as updates on AI-related capital expenditures and progress on HunYuan models, Yuanbao, and WeChat AI features.
$JD-SW (09618.HK)$ will announce its second-quarter and interim results on Thursday, with an earnings call scheduled for 20:00. JD Logistics, JD Health, and JD Industrial will also simultaneously disclose their results. Beyond retail revenue and margins, the market will focus on how investments in new businesses like instant retail impact profitability and the growth of external customers in the logistics segment.
On the semiconductor front, $SMIC (00981.HK)$ 、 $HUA HONG GRACE (01347.HK)$ will report results on Thursday. Key focal points include wafer capacity utilization, average selling prices, capital expenditures, demand for mature-node processes, and progress on domestic substitution. Lenovo Group and China Mobile will also report earnings the same day, offering insights into the momentum of AI servers, AI PCs, and cloud computing businesses, respectively.
– AI infrastructure giants deliver earnings for three consecutive nights, putting the U.S. tech supply chain to a stress test
after U.S. market hours on Tuesday, $CoreWeave (CRWV.US)$ 、 $Lumentum (LITE.US)$ and $Super Micro Computer (SMCI.US)$ will be the first to report earnings. CoreWeave previously disclosed a revenue backlog approaching $100 billion; the market will scrutinize data center ramp-up, power resources, capital expenditures, and financing costs. Lumentum, meanwhile, will serve as a barometer for demand in 800G and 1.6T optical modules and data center optical communications.
Super Micro Computer had previously guided fourth-quarter revenue toward the lower end of its $11–12.5 billion range, but new orders exceeded $60 billion. Market attention will center on order conversion speed, delivery capability, and whether gross margins can meet the updated guidance of 15%–17%.
After Wednesday's market close, $Cisco (CSCO.US)$ and $Coherent (COHR.US)$ will follow with their reports, validating demand for AI networking equipment and high-speed optical communications; after market close on Thursday, Applied Materials will set the tone for spending trends in wafer manufacturing, DRAM, advanced packaging, and semiconductor equipment.
So far this year $PHLX Semiconductor Index (.SOX.US)$ has risen more than 80% cumulatively, yet remains down over 15% from its late-June peak. In a crowded trading environment, even earnings beats may not suffice—the quality of orders, profit margins, and capital expenditure guidance could ultimately dictate the stock’s market reaction.
– Unitree Robotics launches IPO subscription; commercial aerospace, smartphones, and memory sectors all receive catalysts
$Yushu Technology (688836.SH)$ will open online and offline subscription on the STAR Market this Monday. The company plans to issue 40.4464 million shares, representing 10% of its post-IPO total share capital. Online subscription will be open from 9:30–11:30 and 13:00–15:00, with payment due for successful applicants on August 12. As a highly anticipated humanoid robotics company, its subscription demand could serve as a barometer for risk appetite across the broader robotics supply chain.
In commercial aerospace, a Notice to Airmen indicates that the temporary launch and recovery window for Zhuque-3 Y2, a reusable rocket, is set for approximately 7:40 AM Tuesday. This mission is expected to again test vertical recovery of the first stage, though the exact timing remains subject to official confirmation.
At 06:00 Beijing time on Thursday, $Alphabet-C (GOOG.US)$ Google will hold its Made by Google event, where it is expected to unveil the Pixel 11 series and next-generation wearables. The key highlight will be the extent of Gemini integration into mobile devices.
On the same day at 21:00, $SanDisk (SNDK.US)$ an investor day will be held, with market focus on NAND supply-demand dynamics, capital expenditure plans, the roadmap for high-bandwidth flash memory, and long-term margin targets.
– The Reserve Bank of Australia is expected to hold rates steady, while three major monthly oil market reports are set for密集 release
The Reserve Bank of Australia will announce its interest rate decision and monetary policy statement at 12:30 on Tuesday, followed by a press conference at 13:30. The market widely expects the cash rate to remain unchanged at 4.35%, with close attention on whether cooling inflation, weakening employment, and housing market risks prompt the central bank to signal potential rate cuts ahead.
The Bank of Japan will release the summary of opinions from its July monetary policy meeting at 07:50 on Monday. Market participants will scrutinize the document for insights into policymakers’ views on inflation, the yen, and the pace of future policy normalization.
In energy markets, the EIA’s Short-Term Energy Outlook will be released on Tuesday, followed by the IEA and OPEC monthly oil market reports on Wednesday. After last week’s sharp decline in oil prices, these three reports—assessing global supply-demand dynamics, production, and inventories—could continue to influence inflation expectations.
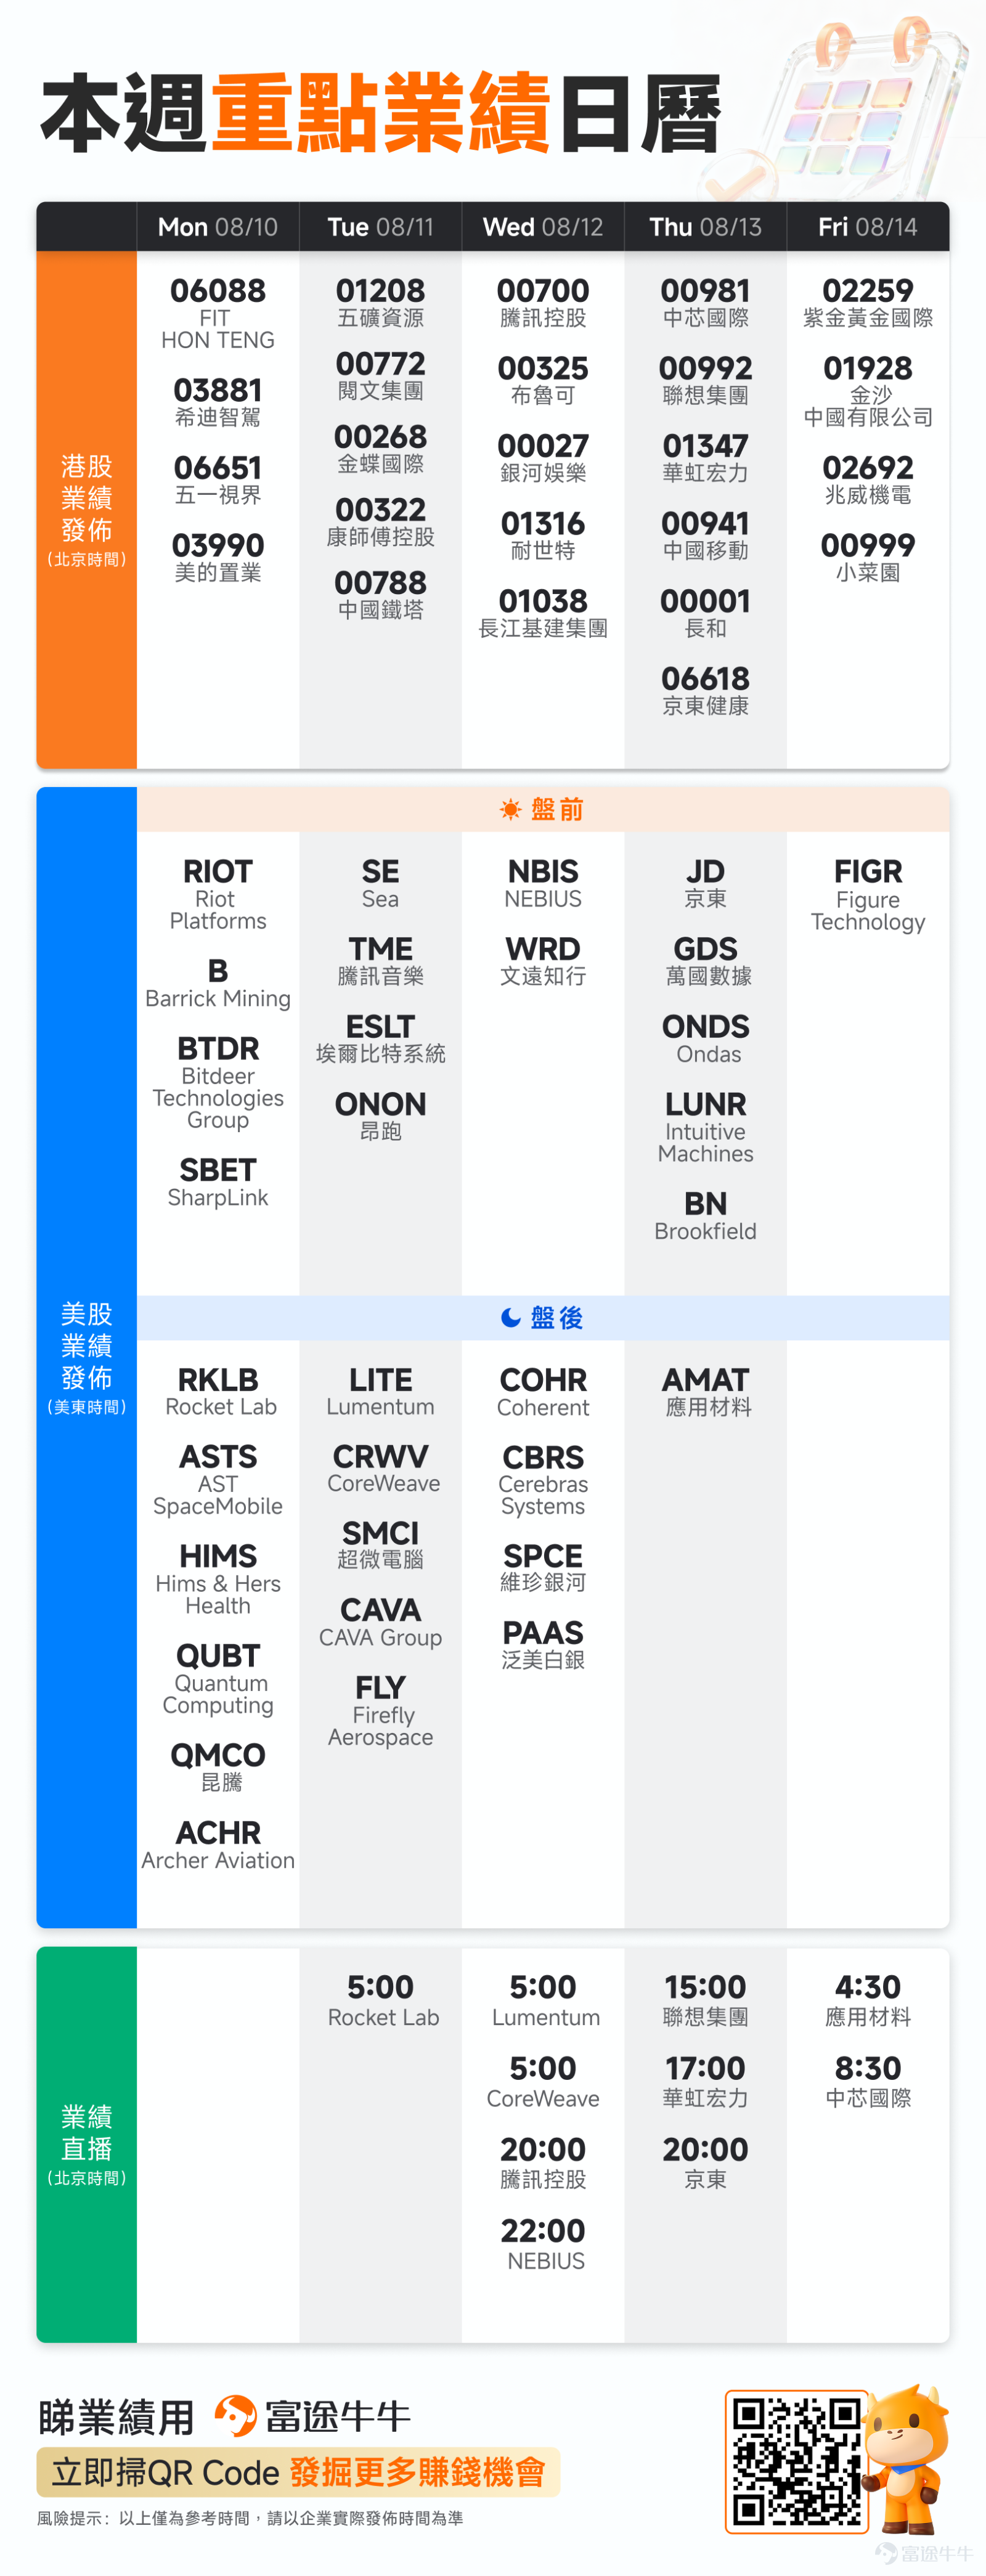
Key Earnings Calendar for the New Week
Earnings reports for the new week will be dominated by leaders in AI infrastructure, semiconductors, internet, and consumer sectors.

Monday (August 10)
Keywords: Bank of Japan meeting summary; Eurozone investor confidence; Rocket Lab earnings
On the economic data front,At 07:50, Japan releases June trade balance; at 16:30, the Eurozone Sentix investor confidence index for August is published.
On the economic calendar,at 7:50, the Bank of Japan will release the summary of opinions from its July monetary policy meeting; market participants will focus on committee members’ views on inflation risks, the yen, and the timing of potential rate hikes. Unitree Technology will launch online and offline subscription for its STAR Market listing; $CXMT Corporation (688825.SH)$ It has been included in the MSCI China All Shares Index, effective as of today.
In corporate earnings, U.S. stocks$Bitdeer Technologies Group (BTDR.US)$will release earnings before the market opens;$Rocket Lab (RKLB.US)$、$AST SpaceMobile (ASTS.US)$、$Hims & Hers Health (HIMS.US)$will report after the market close. Hong Kong-listed stocks$FIT HON TENG (06088.HK)$、$MIDEA REAL EST (03990.HK)$will release earnings reports.
Tuesday (August 11)
Keywords: Lumentum, Super Micro Computer earnings; Japanese stock market closed
On the economic data front,At 18:00, the U.S. NFIB Small Business Optimism Index for July will be released; at 20:15, the weekly change in ADP employment for the week ending July 25 will be published; at 22:00, the annualized existing home sales figure for July will be announced, with market expectations at 4.07 million units, compared to the prior reading of 4.09 million.
On the economic events front,At 12:30, the Reserve Bank of Australia will announce its interest rate decision and monetary policy statement, with markets expecting the cash rate to remain unchanged at 4.35%; at 13:30, RBA Governor Bullock will hold a monetary policy press conference.
On the earnings front,US stocks$Sea (SE.US)$、$Tencent Music (TME.US)$will release earnings before the market opens;$Super Micro Computer (SMCI.US)$、$CoreWeave (CRWV.US)$、$Lumentum (LITE.US)$and$CAVA Group (CAVA.US)$will report after the market close. Hong Kong-listed stocks$CHINA TOWER (00788.HK)$、$MMG (01208.HK)$、$TINGYI (00322.HK)$、$CHINA LIT (00772.HK)$will release earnings reports.
Regarding market holidays, the Tokyo Stock Exchange in Japan will be closed for one day due to Mountain Day.
Wednesday, August 12
Key highlights: U.S. CPI for July, Tencent, Coherent earnings
On the economic data front,4:30 AM: API crude oil inventory data for the week ending August 7 released; 2:00 PM: Germany's final July CPI monthly rate released;8:30 PM: Key US July CPI and core CPI data released. Headline CPI is expected to rise 0.1% month-over-month and 3.4% year-over-year; core CPI is forecast to increase 0.20% month-over-month and 2.50% year-over-year; 10:30 PM: EIA crude oil inventory data for the week ending August 7 released.
On the economic calendar,12:00 AM: EIA releases its Short-Term Energy Outlook report; 4:00 PM: IEA releases its monthly oil market report; OPEC’s monthly report release time is yet to be confirmed, typically published between 6:00 PM and 9:00 PM.
On the earnings front, Hong Kong-listed stocks$TENCENT (00700.HK)$announce results. US-listed stocks$NEBIUS (NBIS.US)$、$WeRide (WRD.US)$release earnings before the market opens,$Coherent (COHR.US)$、$Cerebras Systems (CBRS.US)$、 $Cisco (CSCO.US)$ and$Virgin Galactic (SPCE.US)$ announce results after the market closes.
Thursday (August 13)
Key highlights: US PPI; Fed officials' speeches; SanDisk Investor Day; SMIC earnings
On the economic data front, at 01:00, the results of the US 10-year Treasury note auction will be released; at 14:00, the UK’s preliminary year-over-year GDP for Q2, June industrial production, and manufacturing output data will be published; at 17:00, eurozone June industrial production month-over-month will be announced; at 20:30, the US weekly initial jobless claims for the week ending August 8 and US July PPI will be released, with the PPI month-over-month forecast at 0.20%; at 22:30, the US EIA natural gas inventory report will be issued.
On the financial events front, at 06:00, $Alphabet-C (GOOG.US)$ hosts the Made by Google product launch event; at 20:15, Cleveland Fed President and 2026 FOMC voting member Beth Hammack delivers remarks; at 20:40, Richmond Fed President and 2027 FOMC voting member Tom Barkin speaks on the economic outlook; at 21:00, $SanDisk (SNDK.US)$ hosts its Investor Day.
In corporate earnings, U.S. stocks$JD.com (JD.US)$、$GDS Holdings (GDS.US)$report before the market opens, $Applied Materials (AMAT.US)$and release earnings after the market closes. Hong Kong-listed stocks $CHINA MOBILE (00941.HK)$、$SMIC (00981.HK)$、$LENOVO GROUP (00992.HK)$、$HUA HONG GRACE (01347.HK)$announce their earnings.
Friday (August 14)
Key highlights: U.S. retail sales; University of Michigan consumer sentiment; Eurozone GDP; RBA testimony
On the economic data front,At 14:45, France’s final July month-over-month CPI is released; at 17:00, the Eurozone’s revised Q2 year-over-year GDP, final Q2 employment quarter-over-quarter, and June trade balance are published; at 20:30, U.S. July month-over-month retail sales are announced, with market expectations at 0.30%, up from the prior reading of 0.20%; at 22:00, the U.S. preliminary August one-year inflation expectation, preliminary University of Michigan consumer sentiment index, and June business inventories month-over-month are released, with the consumer sentiment index expected at 54, down from the previous 55.2.
On the economic calendar,At 7:30, RBA Governor Bullock appears at a hearing. China’s domestic refined oil prices enter a new adjustment window, with the exact timing to be confirmed.
Other notable events:The deadline for U.S. institutional filings of Q2 13F holdings reports arrives. The market can use these disclosures to observe changes in allocations by large hedge funds and asset managers as of end-June across sectors such as technology, energy, and financials. However, note that 13F filings only disclose certain long positions and carry a reporting lag of approximately 45 days.
 Wishing all fellow investors a successful week ahead!Get ahead of major financial events and spot investment opportunities early! Open Futubull > Market > US Stocks >Financial Calendar/Featured macroeconomic data, seize investment opportunities ahead of the curve!

Editor/Rocky
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comment (1)
to post a comment
37
11