US Equity Indices Edition | S&P and Nasdaq Near Highs—Chasing Direction Doesn't Necessarily Mean Higher Leverage Is Better: Bull/Bear Certificates Are Worth Comparing First Based on Knock-in Distance
The US market has shown an interesting condition over the past few days:Indices are still holding high, but it’s no longer a comfortable spot where you can blindly chase gains.
The S&P 500 Index closed at 7,709.96 points on August 6, having previously reached an intraday high of 7,793.68 points; SPY also closed at $768.56, with its short-term RSI already rising to around 73. The Nasdaq-100 Index closed at 29,373.33 points, rebounding sharply from late-July lows and returning above the 29,000 mark, though it remains some distance away from its June high of 30,762 points.
Therefore, what’s truly worth discussing at this stage isn’t just whether the S&P or Nasdaq will rise or fall, but rather:
If you already have a directional view, which terms of Hong Kong-listed US stock index warrants/Callable Bull/Bear Certificates (CBBCs) are more suitable for the current market conditions?
S&P 500 $S&P 500 Index (.SPX.US)$ : Both bull and bear CBBCs offer high leverage, but bear certificates are most likely to tempt investors into 'chasing short-term gains.'
Let’s start with the S&P.
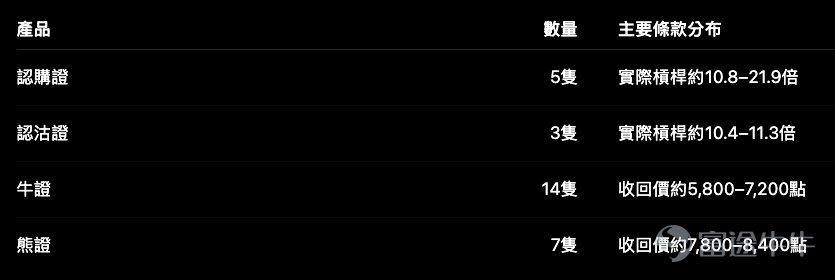
Currently available S&P 500-related products include:

The most noteworthy is actuallybear certificates。
When the S&P reference price is around 7,724 points, the knock-out level of the closest-to-the-money bear certificate in the market has already reached around 7,800 points,meaning the knock-out distance is less than 1%, with leverage potentially as high as 80x。
An 80x leverage may look attractive, but the problem with this type of product is very straightforward:
You not only have to correctly predict a decline, but also accurately time that it won't rise by dozens more points before falling.
The S&P is still trading in a high range and has just recently reached 7,793 points. If you select bear warrants with a call price near 7,800 points, even a normal intraday rebound—without any real change in underlying direction—could trigger early redemption of the product.
Conversely, bear warrants with a call price near 8,000 pointsare about 3.6% away, still offering roughly 30x leverage. Moving one step further out—for example, call prices between 8,200 and 8,400 points—leverage decreases, but you gain more practical room for market movement.
Therefore, if you're bearish on the S&P right now, I wouldn’t prioritize 'maximum leverage' as my top criterion.
At this level, the real value in shorting lies in preserving enough buffer to accommodate a potential initial upward move before the anticipated decline.
If you’re bullish on the S&P, bull warrants are actually easier to select.
S&P bull warrant terms are relatively favorable.
The callables in the data range from 5,800 to 7,200 points, representing knock-in distances of approximately 6.8% to 24.9%, with leverage between about 3.8x and 11.2x.
If you're only targeting a breakout above recent highs, callable warrants near the 7,200-point level offer roughly 11x leverage, but their knock-in distance of around 6.8% is already significantly more comfortable than that of at-the-money bear warrants.
If you don’t want to take on excessive knock-in risk, set the knock-in level at around 6,900 to 7,000 points, which corresponds to a knock-in distance of roughly 9% to 11%, while still offering leverage of about 8x.
This type is actually better suited for the current S&P:
You can still benefit from leveraged upside on a breakout above recent highs, without being forced out of your position due to normal one- or two-day pullbacks.
There’s a set of terms for S&P call warrants that is actually far more practical than high-leverage, out-of-the-money calls.
S&P call warrants exhibit a very clear polarization.
Some products have strike prices as high as 9,000 points, i.e., approximately 16.5% out-of-the-money, with effective gearing exceeding 20x.
The problem is:
– Delta is only around 9% to 10%
– Premium is approximately 17%
– Daily time decay is about 2.3%
– If the underlying index doesn’t rise significantly, the product may not move quickly in practice
This is a classic case of 'an attractive-looking gearing number, but insufficient actual sensitivity.'
On the other hand, there are in-the-money call warrants with strike prices around 7,200 to 7,236 pointswith deltas reaching over 80%, effective gearing of about 11x, a premium of only around 1%, and daily time decay of approximately 0.5% to 0.6%.
When comparing these two types of products side by side, their trading values are entirely different.
If you're bullish on the S&P continuing to break above 7,800:
I’d prefer slightly less nominal leverage in exchange for higher delta and lower premium.
What you really want is for the product to respond when the S&P rises by 10 or 20 points—not to see 20x leverage on paper but only start gaining sensitivity after a large index move.
Nasdaq $NASDAQ 100 Index (.NDX.US)$ : Direction is even more volatile than the S&P; the 'distance' of bull/bear warrants should be relaxed by one more level.
The Nasdaq-100 currently warrants extra caution.
The index quickly rebounded from around 27,200 points in late July, briefly challenging 30,000 again, but fell back to 29,373 points on August 6.
In other words, the Nasdaq still has upward momentum, but its short-term volatility is significantly higher than that of the S&P.
Based on current data:

This distribution actually already reveals one thing:
Bear warrants on the Nasdaq in the market are notably more 'aggressive' than those on the S&P.
The closest-to-the-money bear warrants can have a call price near the 30,000 level, which at the time was only about 1.7% away based on product details, offering leverage as high as approximately 46x.
But looking at the Nasdaq’s recent movements over the past few days, swings of several hundred points in a single day are nothing unusual.
Thus, bear warrants with call prices near 30,000 face the same issue as those linked to the S&P—and arguably an even more severe one:
You might correctly anticipate 'resistance around 30,000,' but if the index briefly dips below that level intraday, the product is already knocked out.
If you truly want to position for a pullback, bear warrants with call prices around 31,000 to 32,000 offer much more practical trading room—even though their leverage drops to just over 10x.
Nasdaq calls and puts aren’t particularly cheap on either side.
Nasdaq call warrants are available with strike prices ranging from 28,800 to 35,800, offering effective leverage of roughly 6x to 14x.
However, for deep out-of-the-money calls in the 35,000 to 35,800 range:
– They are approximately 19% to 21% out-of-the-money
– Their delta is only about 13% to 18%
– Premium of over 20%
– Daily time decay of approximately 1.7% to 2%
I’d be more cautious about this kind of term.
If the Nasdaq truly surges sharply to 31,000 or 32,000 points, it could rise very quickly; but if it just trades sideways near highs, the product will lose time value every day.
Conversely, call warrants closer to the current price with delta around 40% to 60%, even if they have slightly lower effective gearing, are actually better suited for genuine directional trading.
The same applies to put warrants. Puts near 29,000 are only about 1.7% out-of-the-money, with a delta of roughly 39%, making them far more practical than deep out-of-the-money puts at 24,000 or 25,000.
This is how I interpret index-linked products at this stage:
If it isBullish on the S&P, bull certificates with knock-out levels around 6,900 to 7,200 could be considered; if selecting warrants, priority should instead go to in-the-money calls with low premium and high delta, rather than simply chasing leverage above 20x.
If it isBearish on the S&PI'm not too fond of those tight bear warrants near the 7,800 level. Choosing strike levels at 8,000 or even slightly further away—sacrificing some leverage for a more reasonable buffer—makes much more sense.
As forNasdaqBecause it inherently has higher volatility, both bull and bear warrants should have wider knock-in buffers compared to those on the S&P.
The issue now isn't a lack of directional opportunities—it's that choosing the wrong warrant terms is far riskier than simply getting the market direction wrong.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more

Comments
to post a comment
1