$Tesla (TSLA.US)$with
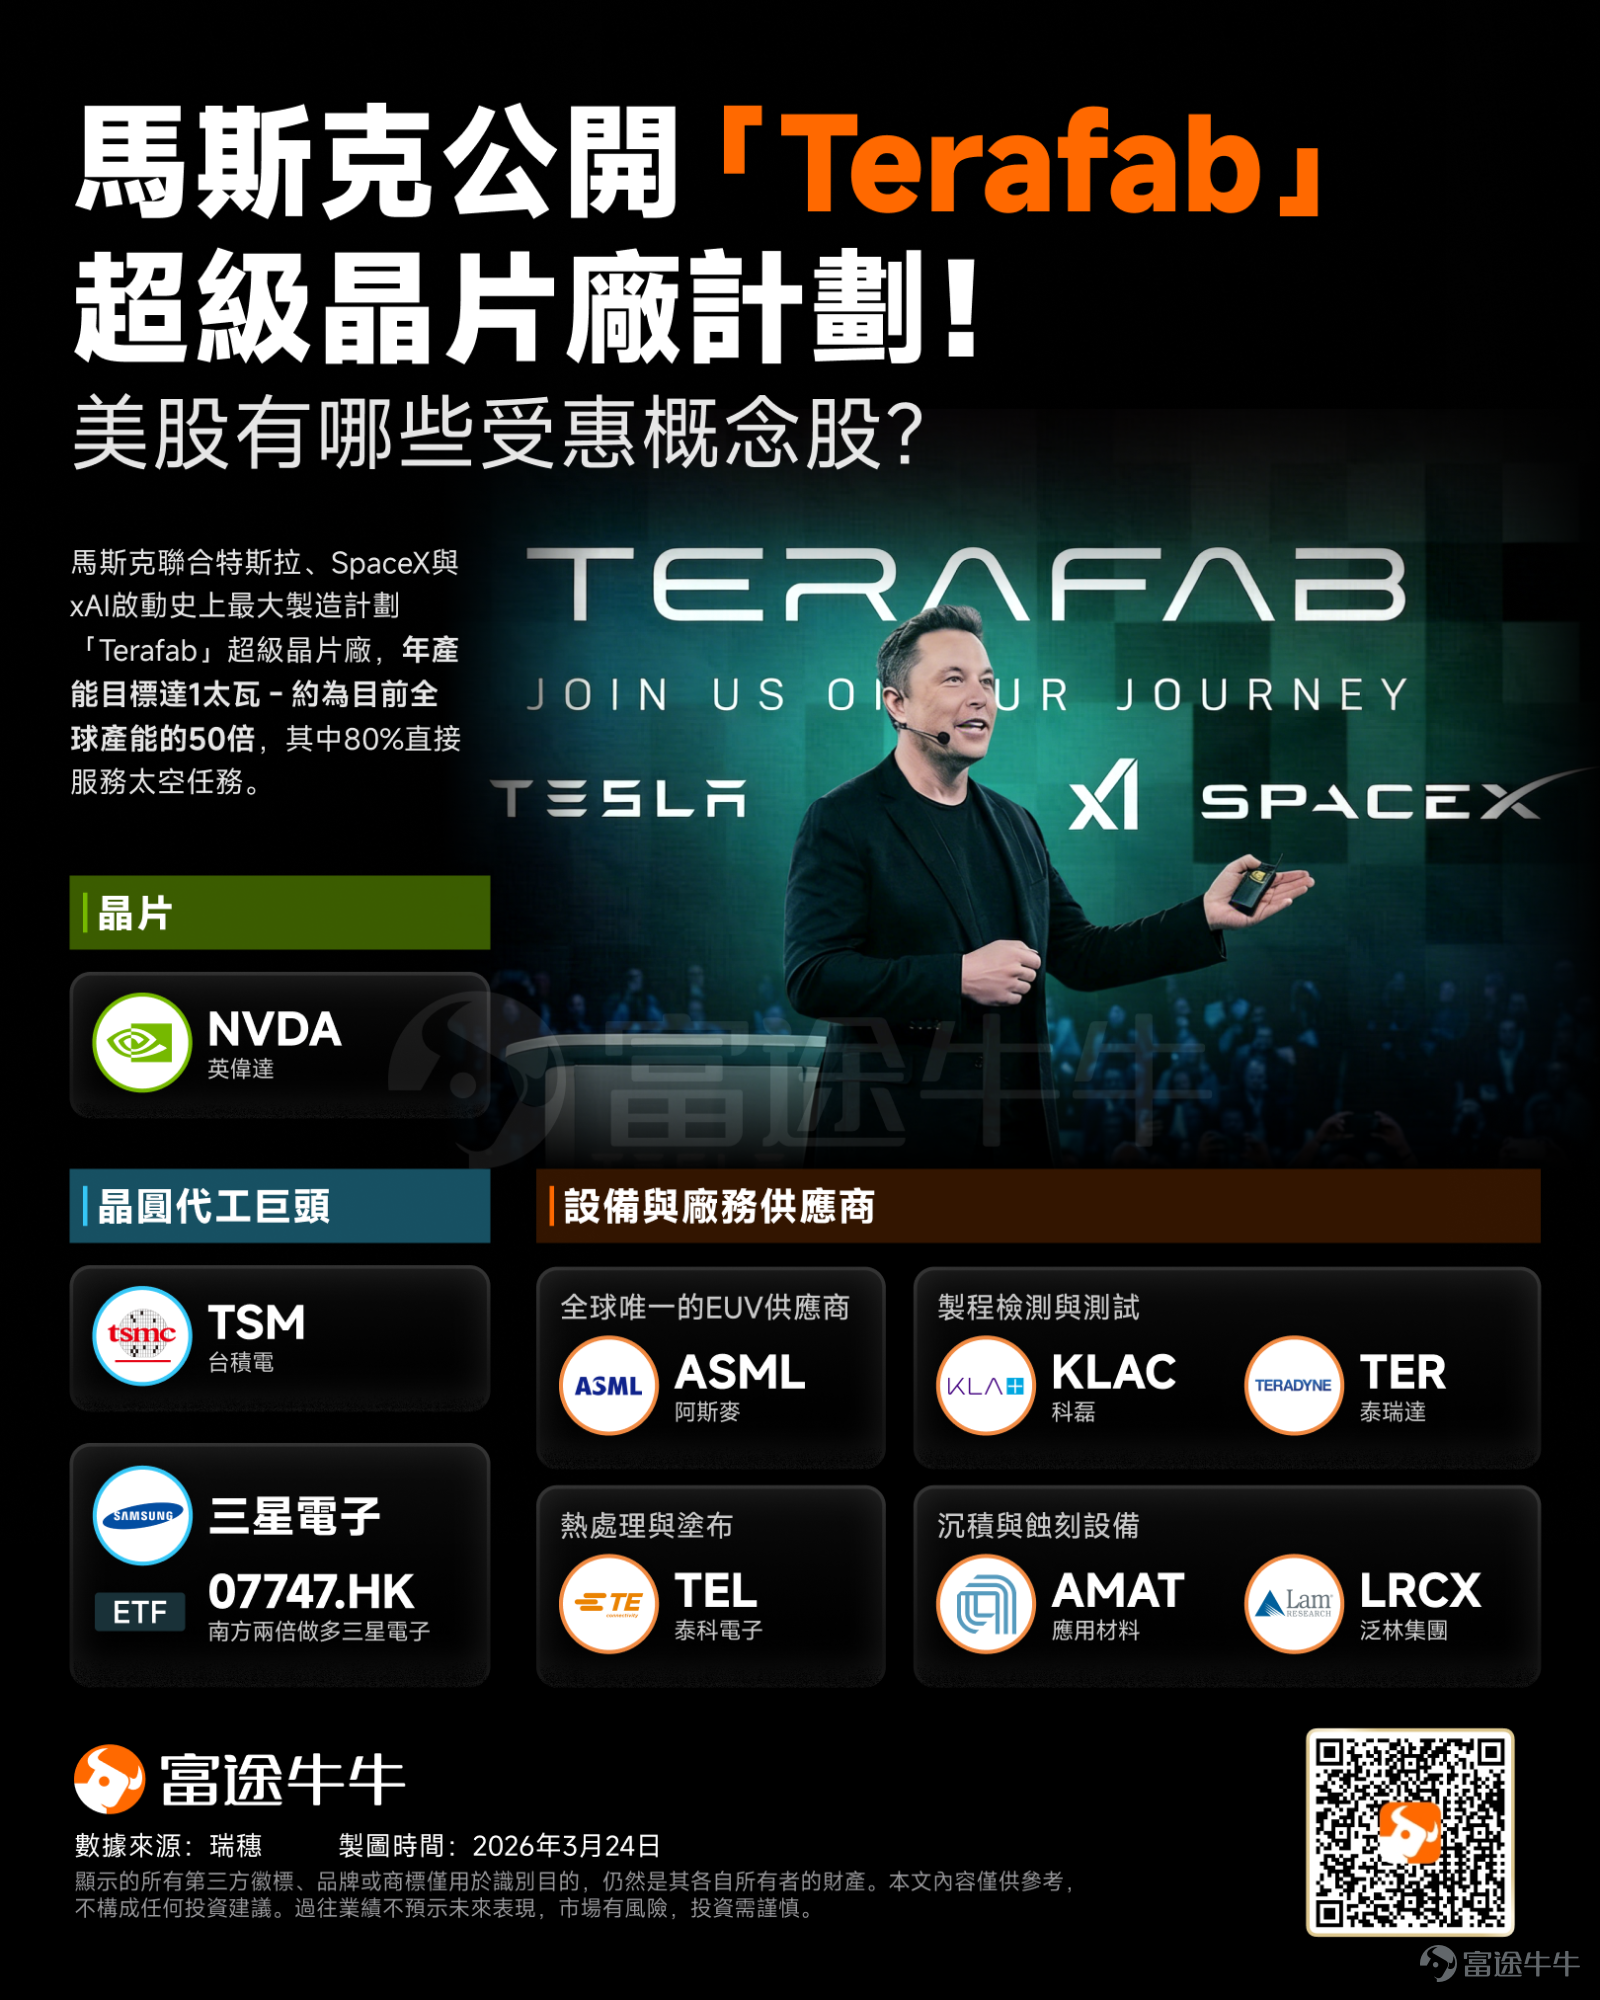
$SpaceX (SPCX.US)$Jointly announced a $16.8 billion investment in Texas to build Terafab, a hyperscale AI chip integrated manufacturing campus spanning approximately 100 million square feet. Unlike traditional wafer fabs, Terafab will integrate logic and memory chip manufacturing, advanced packaging, and testing within a single campus, creating a vertically integrated production system directly serving the computing demands of Optimus humanoid robots, Cybercab autonomous ride-hailing vehicles, and SpaceX’s space-based data centers.
$Intel (INTC.US)$ has been confirmed as a manufacturing partner. In terms of supply chain expansion, equipment suppliers
$ASML Holding (ASML.US)$ 、
$Applied Materials (AMAT.US)$ 、
$Lam Research (LRCX.US)$ , back-end assembly and test
$Amkor Technology (AMKR.US)$ , as well as power delivery and thermal management
$Vertiv Holdings (VRT.US)$ 、
$Eaton (ETN.US)$ are all drawing market attention. With AI giants building their own chip capacity, can this rally truly extend from compute chips to equipment, packaging/testing, and power infrastructure? Is Tesla’s move a strategic advantage or an overextension of capital?