OpenAI delays IPO; is Anthropic still aiming for a $2 trillion valuation?

Anthropic Races Toward IPO: A Comprehensive Comparison with OpenAI—How to View the Competitive Landscape of AI Giants?
Anthropic is preparing for an IPO, with current market valuations pointing toward $2 trillion.
If this valuation materializes, Anthropic will become one of the most watched listed companies in the AI industry. Meanwhile, although OpenAI has no plans for an IPO in 2026, market expectations for its valuation in the new funding round have reached approximately $1.2 trillion.
Both AI giants are experiencing rapid revenue growth, but their business models, customer structures, profitability, and computing power investments are not entirely identical.
Is Anthropic worth $2 trillion? Compared to OpenAI, which metrics should the market truly focus on? This article provides a detailed analysis.
1. Rapid Revenue Growth: Anthropic Currently Leads, but ARR Should Not Be Directly Compared
Anthropic's revenue growth has accelerated significantly in recent years. Public data shows that Anthropic's ARR grew rapidly from approximately $9 billion at the end of 2025 to over $65 billion by the end of July this year; meanwhile, OpenAI's latest ARR as of August has also exceeded $40 billion. Both companies remain in a phase of rapid expansion.
Numerically, Anthropic is currently experiencing faster revenue growth.However, the ARR figures disclosed by the two companies do not follow completely uniform accounting standards, so a simple one-to-one comparison is not advisable.
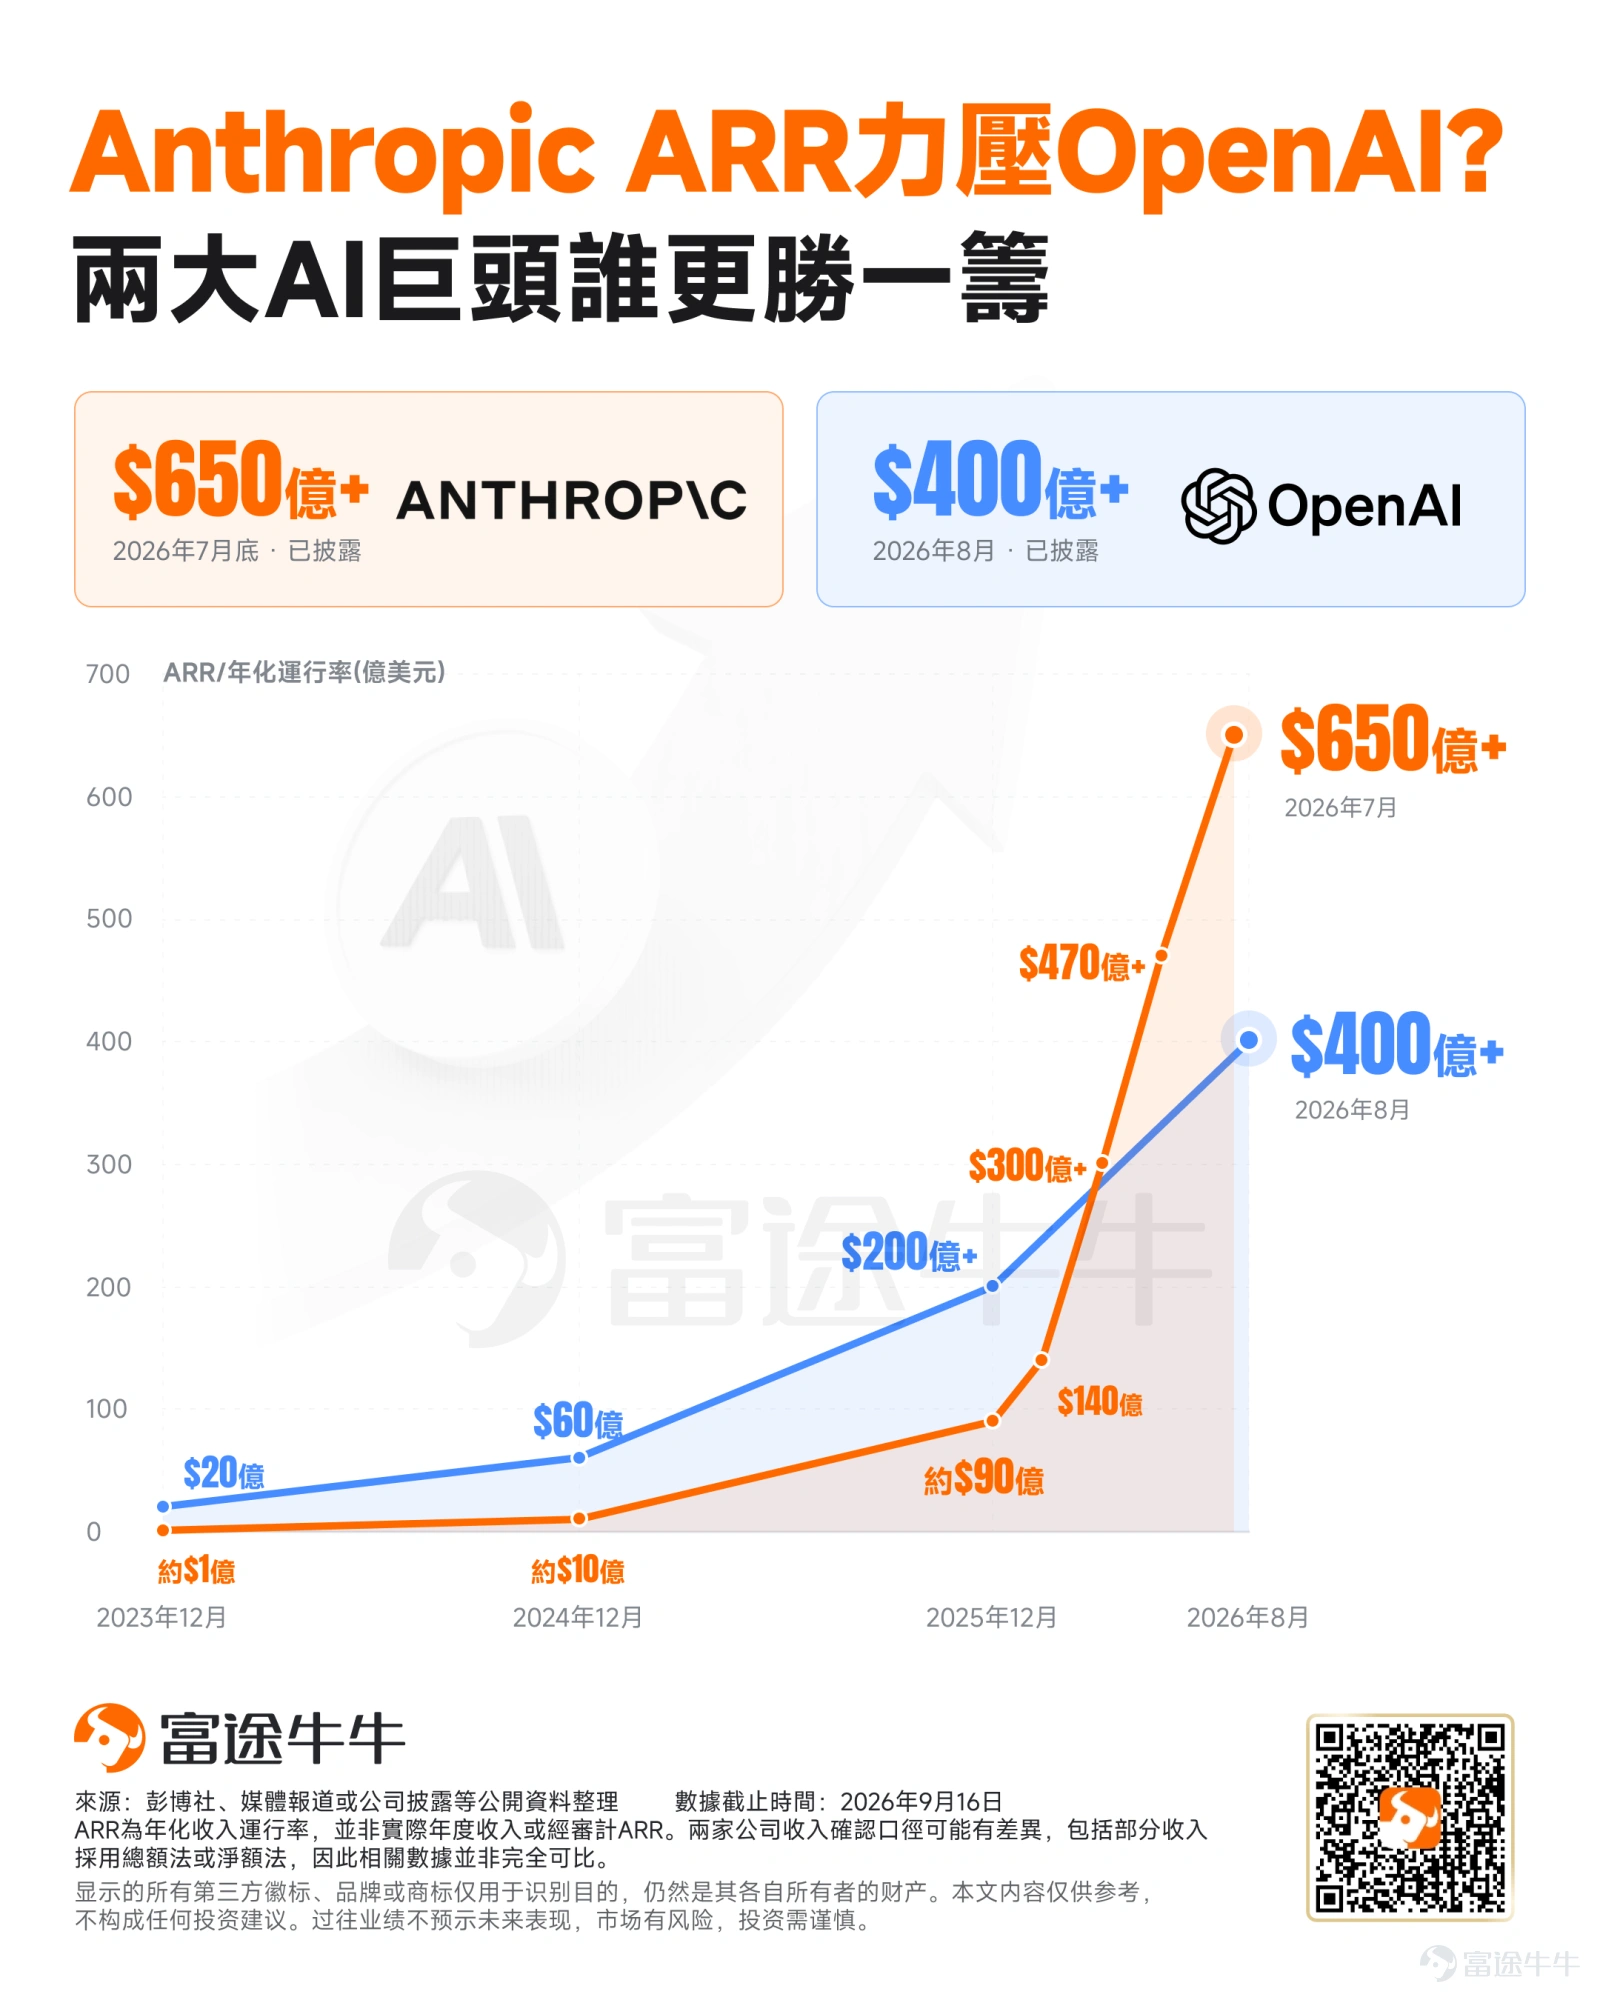
ARR itself is not a statutory metric under US Generally Accepted Accounting Principles (GAAP). The two companies differ in their accounting methodologies regarding calculation periods, timing of revenue recognition, and revenue sharing with cloud computing partners, such as the debate between Gross (gross method) and Net (net method).
Therefore, the current figures of $65 billion and $40 billion are better suited for observing revenue growth trends rather than being treated as fully comparable financial data. Truly comparable metrics will only be available after Anthropic files its S-1, allowing for an assessment based on revenue, customer structure, and revenue recognition policies under unified accounting standards.
2. Business Model: Anthropic focuses more on enterprises and developers, while OpenAI has a larger consumer entry point.
One of the biggest differences between the two companies lies in their commercialization paths.
Anthropic primarily builds its business around Claude, with revenue sources including enterprise subscriptions, API usage, and Claude Code.
In particular, Claude Code has become a new growth engine. Enterprises can integrate Claude into workflows such as software development, data analysis, customer service, and AI agents via the API, with revenue directly tied to actual usage. This model positions Anthropic more towards Enterprise AI + API + AI Programming.
OpenAI, on the other hand, has a larger consumer business.
ChatGPT provides a massive user entry point. Beyond individual subscriptions, the company also covers enterprise services, API, Codex, and Agent businesses.
From a business model perspective, Anthropic's revenue growth in enterprise and developer scenarios is worth watching; OpenAI boasts a broader user base and product coverage.
This also means that the drivers of revenue growth for the two companies will differ in the future:Anthropic needs to continuously expand its enterprise client base and deepen usage, while OpenAI needs to further convert ChatGPT's user scale into subscription, enterprise, and API revenue.
3. Profitability: Anthropic shows positive signals, but AI costs remain a key variable
Compared to revenue, profitability may be the more noteworthy aspect of Anthropic's IPO.
Anthropic has disclosed to select shareholders and investors that it achieved adjusted operating profit in Q2 and expects to maintain positive results in Q3;The company reported a gross margin exceeding 80%.
However, this figure requires careful interpretation. Its gross margin of over 80% is calculated before accounting for revenue sharing with certain partners and model training costs, so it cannot be directly equated to the final operating margin. The cost structure of AI companies also includes substantial expenditures on model training, inference, cloud computing, R&D, and data centers.
Meanwhile, OpenAI remains in a high-investment phase. Its operating loss in Q2 was approximately $12.3 billion, higher than the roughly $9.3 billion in Q1. At the same time, OpenAI's revenue scale continues to grow rapidly.
There are also discrepancies in the reporting metrics for the two companies' profit data: Anthropic discloses adjusted operating profit, while OpenAI's operating loss includes significant R&D and compute capacity investments. Therefore, it is currently inappropriate to directly judge the relative profitability of the two companies based on single-quarter profit figures.
In the future S-1 filing, the most critical items to watch will be GAAP gross margin, R&D expenses, training and inference costs, stock-based compensation, and free cash flow.Only these metrics can further determine how much of AI model companies' revenue growth ultimately translates into profit.
4. How to view the $2 trillion valuation? The key lies in growth quality and compute efficiency
Looking at the long-term value post-IPO for Anthropic, the market will focus on three core questions:
First, can revenue growth be sustained:Anthropic is currently growing very rapidly, but whether this pace can be maintained as it scales remains to be seen.
Second, can high gross margins translate into real profitability:A gross margin of over 80% is based on specific accounting metrics; ultimately, operating profit and free cash flow after accounting for training, inference, and cloud service costs are what matter.
Third, can computing power investments create operating leverage:Both companies need to continuously procure GPUs, TPUs, and data center resources. If future revenue growth significantly outpaces the growth in computing and R&D costs, profitability will further improve; conversely, high revenue may still be accompanied by sustained large-scale capital expenditures.
Summary
Overall, Anthropic currently exhibitscharacteristics such as rapid revenue growth, a high proportion of enterprise business, and improving adjusted profitability;while OpenAI possessesA larger consumer gateway, a broader product ecosystem, and a more substantial user baseBoth companies face challenges such as model competition, computing costs, and sustained R&D investment.
Therefore, what makes Anthropic's upcoming IPO noteworthy ishow the public markets will price the revenue quality, profitability, and capital efficiency of frontier AI companiesFor investors, the complete financial data disclosed in the S-1 filing will be more valuable for reference than the ARR and valuation figures currently available in the market.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments (2)
to post a comment
11
16