US Stock Market Talk | The Fed Resumes Rate Hikes After a Three-Year Pause! Is a New Shift Ahead for
Wall Street Brief (August 28): US stocks rebounded on Thursday, with tech heavyweights driving the Nasdaq to lead gains; NVIDIA reignited faith in AI; software, cybersecurity, and cloud computing strengthened, while Bitcoin continued to soar.
Summary: US stocks rose on Thursday. The S&P 500 gained 0.72%, the Nasdaq rose 1.57%, the Dow Jones increased 0.20%, and the Russell 2000 index climbed 0.28%. All four major indices strengthened, with the Nasdaq clearly leading, while the Dow and small-cap stocks saw smaller gains. The VIX dropped to 14.51, down 4.60% for the day, indicating a significant decline in safe-haven demand. The market is willing to increase risk exposure again, with sentiment returning to the "greed" zone. NVIDIA's earnings report reinforced the demand for AI computing power, with tech heavyweights driving the index rebound. Software, cybersecurity, cloud computing, and semiconductors emerged as the strongest sectors. Initial jobless claims came in below expectations, showing that economic resilience has not broken, and risk appetite continues to recover. In terms of major asset classes: the 10-year US Treasury yield rose 0.17% to 4.672%; gold rose 0.14% to $4,600.69; crude oil rose 1.99% to $83.54; Bitcoin rose 2.04% to $80,303.21; and the US Dollar Index fell 0.01% to 99.1337.

I. Major Events
1. Surge following NVIDIA's earnings report validates the AI trade once again
NVIDIA's revenue for the second fiscal quarter reached $96.2 billion, a year-on-year increase of 106%; data center revenue hit $89.0 billion, up 117% year-on-year. The earnings information was fully priced in by the market on Thursday, viewed as confirmation that demand for AI computing power remains strong. Investors' confidence in AI capital expenditure has recovered, providing higher valuation support for tech heavyweights. However, capital did not flow evenly into all AI sub-sectors; the market prefers to buy into the core segments with the highest certainty.
2. US initial jobless claims drop to 203,000, indicating economic resilience remains intact
The US Department of Labor reported that initial jobless claims for the week ending August 22 fell to 203,000, below market expectations; continuing jobless claims also declined to 1.778 million. The labor market remains in a state of "limited layoffs and modest hiring," without sudden deterioration. The data supports the growth resilience of risk assets and keeps long-term interest rates elevated. For the stock market, this alleviates recession concerns; for US Treasuries and gold, it weakens the rationale for betting on rapid monetary easing.
II. Major Trends
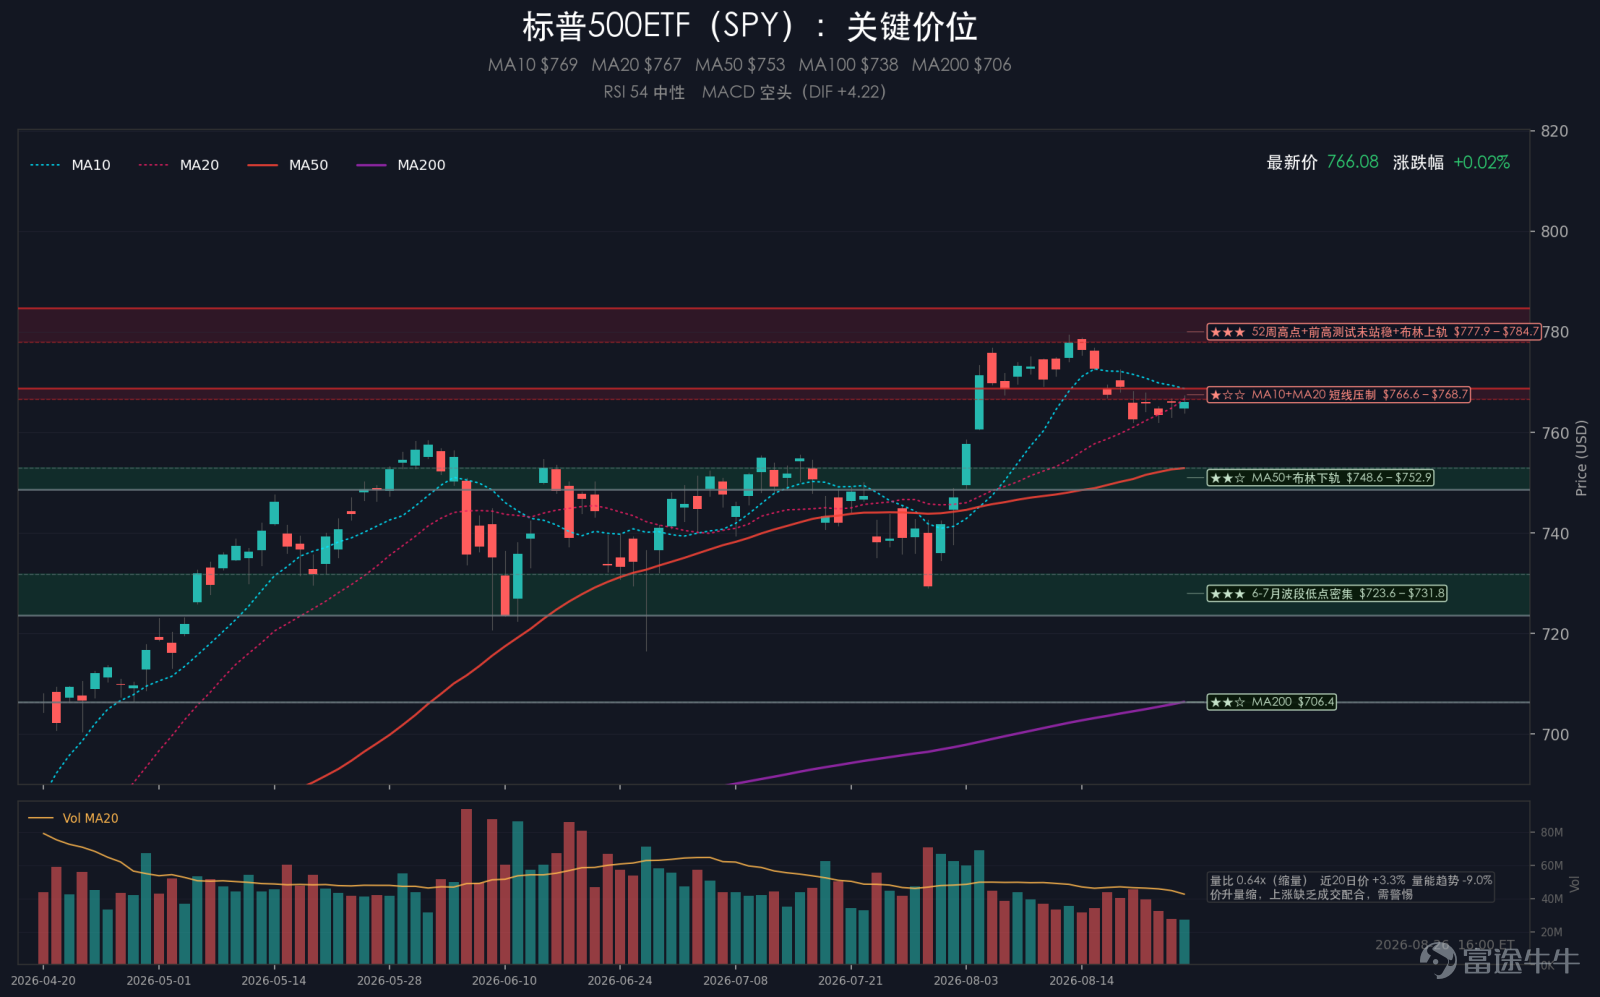
All four major indices rose on Thursday, with the Nasdaq clearly leading the way, while the Dow Jones and Russell 2000 posted smaller gains. The market was driven by large-cap tech stocks, showing a solid rebound, though it has not yet evolved into a broad-based sector rotation.
Over a two-week horizon, the four major indices have not fully recovered: QQQ is down 1.50%, IWM down 1.22%, SPY down 0.87%, and DIA down 0.42%. Short-term pressure remains more pronounced for tech and small-cap stocks. Over a three-month horizon, DIA is up 6.00%, IWM up 3.50%, SPY up 3.02%, while QQQ is down 1.03%, indicating that the mid-term structure still favors the Dow and small caps over the Nasdaq.
Over the past two weeks, mega-cap tech stocks have begun to provide support again, with MAGS up 0.16%, although this gain is modest. The S&P 500 Equal Weight ETF (RSP) fell 0.57% over two weeks, outperforming SPY's 0.87% decline, suggesting no significant deterioration in market breadth. In terms of style, SPYV (value) fell 0.36% over two weeks, while SPYG (growth) fell 1.26%, indicating that value stocks remain more resilient than growth stocks.
III. Market Sentiment
The VIX dropped to 14.51, down 4.60% on the day, signaling a notable decline in safe-haven demand. The simultaneous rise in indices and fall in volatility suggests investors are willing to increase risk exposure again. The CNN Fear & Greed Index rose from 54 to 58, returning to the 'greed' zone. While this level is not yet extremely optimistic, it indicates increased tolerance for short-term risk among capital flows.
Regarding CBOE Put/Call ratios, the total Put/Call ratio stands at 0.65, the index Put/Call ratio at 0.86, and the equity Put/Call ratio at 0.55. Demand for protection on the index side has decreased, while appetite for chasing rallies in individual stocks is stronger, with the options market supporting the rebound in tech stocks.
4. Market Scan
1. Index ETFs
DIA (Dow Jones) rose 0.19%, SPY (S&P 500) rose 0.66%, QQQ (Nasdaq 100) rose 1.37%, and IWM (Russell 2000) rose 0.29%. QQQ significantly outperformed other index ETFs, as large-cap tech stocks once again became the primary driver of the index rally.
Among overseas ETFs, $iShares MSCI South Korea ETF (EWY.US)$ rose 1.65%, standing out relatively; $iShares MSCI France ETF (EWQ.US)$ fell 1.54%, with significant divergence among major country-specific ETFs. On Thursday, the internal structure of the US market was clearer, with the core theme remaining the rebound in the Nasdaq and large-cap tech stocks.
2. Sector Performance
Among the 11 GICS sectors, Technology (XLK) rose 3.16%, leading all other sectors by a wide margin; Consumer Staples (XLP) fell 1.38%, Healthcare (XLV) fell 1.13%, Consumer Discretionary (XLY) fell 1.09%, and Communication Services (XLC) fell 1.07%, indicating that capital has not broadly dispersed across sectors.
From the perspective of industry and thematic ETFs, $iShares Expanded Tech-Software Sector ETF (IGV.US)$ Up 7.74%, $First Trust Exch Traded Fund 2 Nasdaq Cybersecurity Etf (CIBR.US)$ Up 7.61%, $First Trust Cloud Computing ETF (SKYY.US)$ Up 4.21%, $VanEck Semiconductor ETF (SMH.US)$ Up 3.10%, collectively forming the strongest signal within the tech sector. $VanEck Oil Services ETF (OIH.US)$ Up 2.49%, $Invesco Solar ETF (TAN.US)$ Up 1.97%; $SPDR S&P Retail ETF (XRT.US)$ Down 1.86%, with the consumer chain showing明显 weakness.
The AI supply chain did not strengthen in unison. The AI storage basket fell by an average of 0.56%, and the optical communication/optical module basket dropped by an average of 0.09%, failing to follow the rebound in NVIDIA and software stocks. Capital is still focusing on the most certain segments.
3. The Magnificent Seven Tech Stocks
The seven major tech ETFs (MAGS) rose 1.52%. NVIDIA (NVDA) surged 8.74%, acting as the strongest heavyweight; Tesla (TSLA) gained 2.60%, Microsoft (MSFT) rose 1.75%, and Apple (AAPL) edged up 0.36%.
Netflix (NFLX) declined 1.99%, Meta dropped 0.87%, and Google (GOOG) fell 0.41%. Not all large-cap tech stocks rose; Thursday's gains were primarily driven by NVIDIA and select tech heavyweights lifting the indices.
4. Chinese ADRs
$KraneShares CSI China Internet ETF (KWEB.US)$ Down 0.68%, overall weak. $Baidu (BIDU.US)$ Up 3.95%, $Bilibili (BILI.US)$ Up 3.81%, but failed to drive a systematic rally in Chinese concept stocks. $Alibaba (BABA.US)$ fell by 2.94%, $PDD Holdings (PDD.US)$ Down 2.36%, $Futu Holdings Ltd (FUTU.US)$ Down 2.18%, becoming the main drag. Within Chinese concept stocks, performance remains divergent on an individual stock basis, rather than reflecting an overall improvement in risk appetite.
5. Cryptocurrencies
Bitcoin rose 2.04%, reclaiming the $80,000 level. Crypto-related stocks showed greater elasticity, $Strategy (MSTR.US)$ Up 11.54%, $MARA Holdings (MARA.US)$ Up 5.79%, $Coinbase (COIN.US)$ Up 4.92%, $Circle (CRCL.US)$ Up 4.82%, $Riot Platforms (RIOT.US)$Up 1.31%. As Bitcoin itself regains strength, capital is flowing more rapidly into higher-beta crypto-exposed companies, miners, trading platforms, and stablecoin-related assets. Compared to spot prices, these stocks react more quickly to shifts in risk appetite.
$S&P 500 Index (.SPX.US)$ $SPDR S&P 500 ETF (SPY.US)$ $Invesco Exchange Traded Fd Tr S&P 500 Equal Weight Etf (RSP.US)$ $NASDAQ 100 Index (.NDX.US)$ $Invesco QQQ Trust (QQQ.US)$ $Dow Jones Industrial Average (.DJI.US)$ $State Street® SPDR® Dow Jones Industrial Average® ETF Trust (DIA.US)$ $Russell 2000 Index (.RUT.US)$ $iShares Russell 2000 ETF (IWM.US)$ $Roundhill Magnificent Seven ETF (MAGS.US)$ $USD (USDindex.FX)$ $U.S. 10-Year Treasury Notes Yield (US10Y.BD)$ $iShares 20+ Year Treasury Bond ETF (TLT.US)$ $XAU/USD (XAUUSD.CFD)$ $SPDR Gold ETF (GLD.US)$ $CBOE Volatility S&P 500 Index (.VIX.US)$ $CME-Bitcoin RR Futures (SEP6) (BTCmain.US)$ $iShares Ethereum Trust ETF (ETHA.US)$ $NVIDIA (NVDA.US)$ $Tesla (TSLA.US)$ $Meta Platforms (META.US)$ $Amazon (AMZN.US)$ $Alphabet-C (GOOG.US)$ $Microsoft (MSFT.US)$ $Apple (AAPL.US)$
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comments
to post a comment
6
1