AMD's market cap breaks $1 trillion! Is the US stock AI rally staging a full-scale comeback?
Earnings Options Strategy | Marvell Technologies Report Imminent: Beating Estimates Is Just the Baseline—Who Holds the Winning Hand Amid >10% Expected Volatility?
$Marvell Technology (MRVL.US)$ will be released after market close on Eastern Time Thursday, August 27, 2026for FY2027 Q2 (corresponding to the calendar period of approximately May to July 2026).
The most distinctive aspect of this earnings report isbeating estimates for the quarter has essentially become a "must-have" rather than a "bonus point": Wall Street's consensus expectations were precisely anchored to the midpoint of the guidance provided by management in May.
What truly determines the stock price is not how many extra percentage points were earned this quarter, but three things—whether Q3 and full-year guidance will be raised, the long-term outlook and actual orders from the Google partnership, and whether the gross margin of nearly 59% can be maintained。
Meanwhile, MRVL's stock price has rebounded more than 50% from its July lows, with its P/E ratio returning to historical highs. The options market is pricing in approximately 14% single-day volatility for the earnings release. In other words, even if you get the direction right, buyers may still incur losses if the move is insufficient or the guidance lacks surprises, as the elevated implied volatility (IV, reflecting the premium for expected future volatility) could drop sharply after the earnings report.
Consensus precisely anchored to the midpoint of guidance; beating estimates is a "must-have"
This is the key sentence to understanding this earnings report.
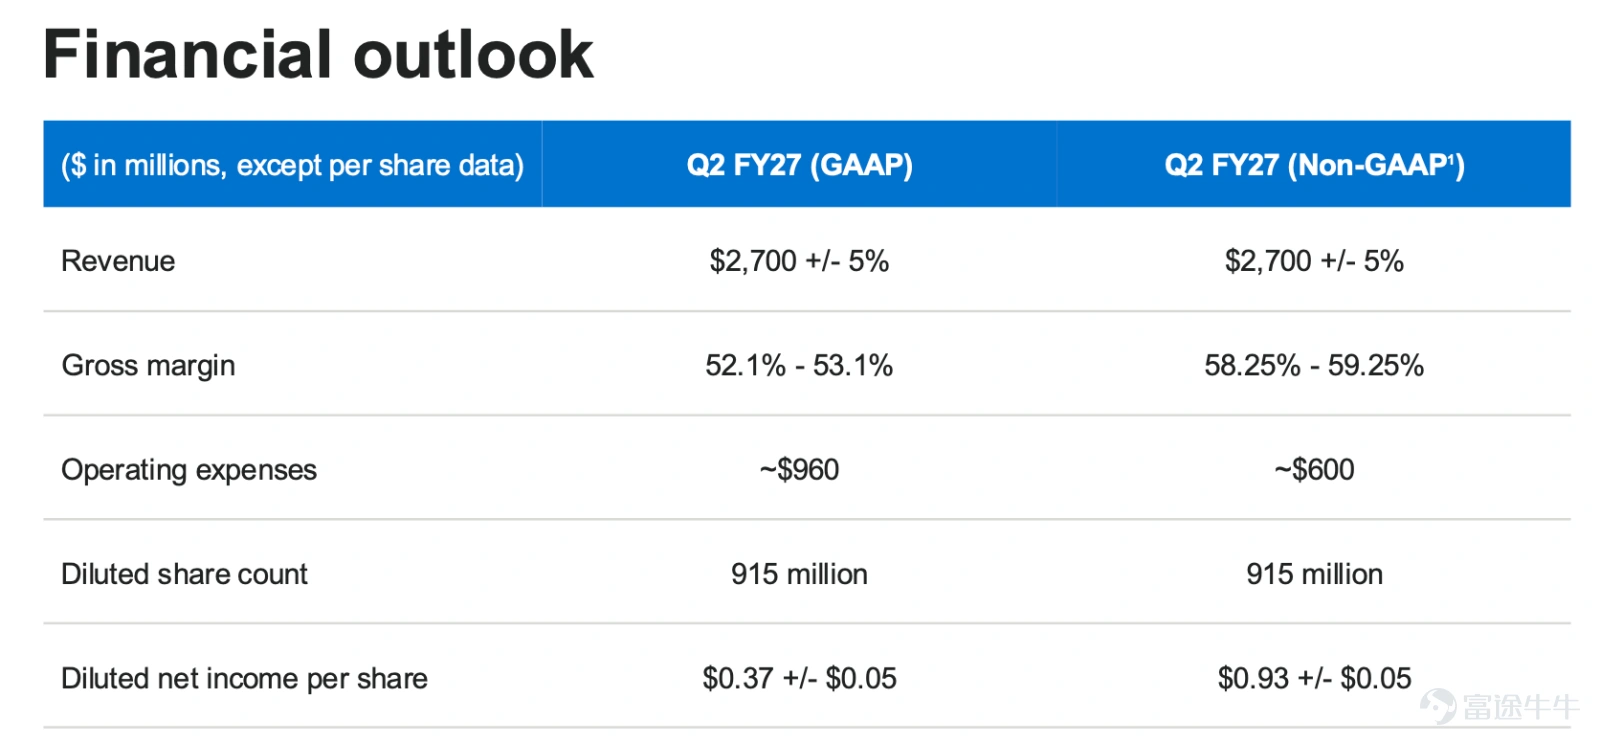
Management's Q2 guidance given in May: Revenue $2.70 billion ±5%- Non-GAAP diluted earnings per share (EPS)$0.93 ± $0.05- Non-GAAP gross margin of 58.25%–59.25%.
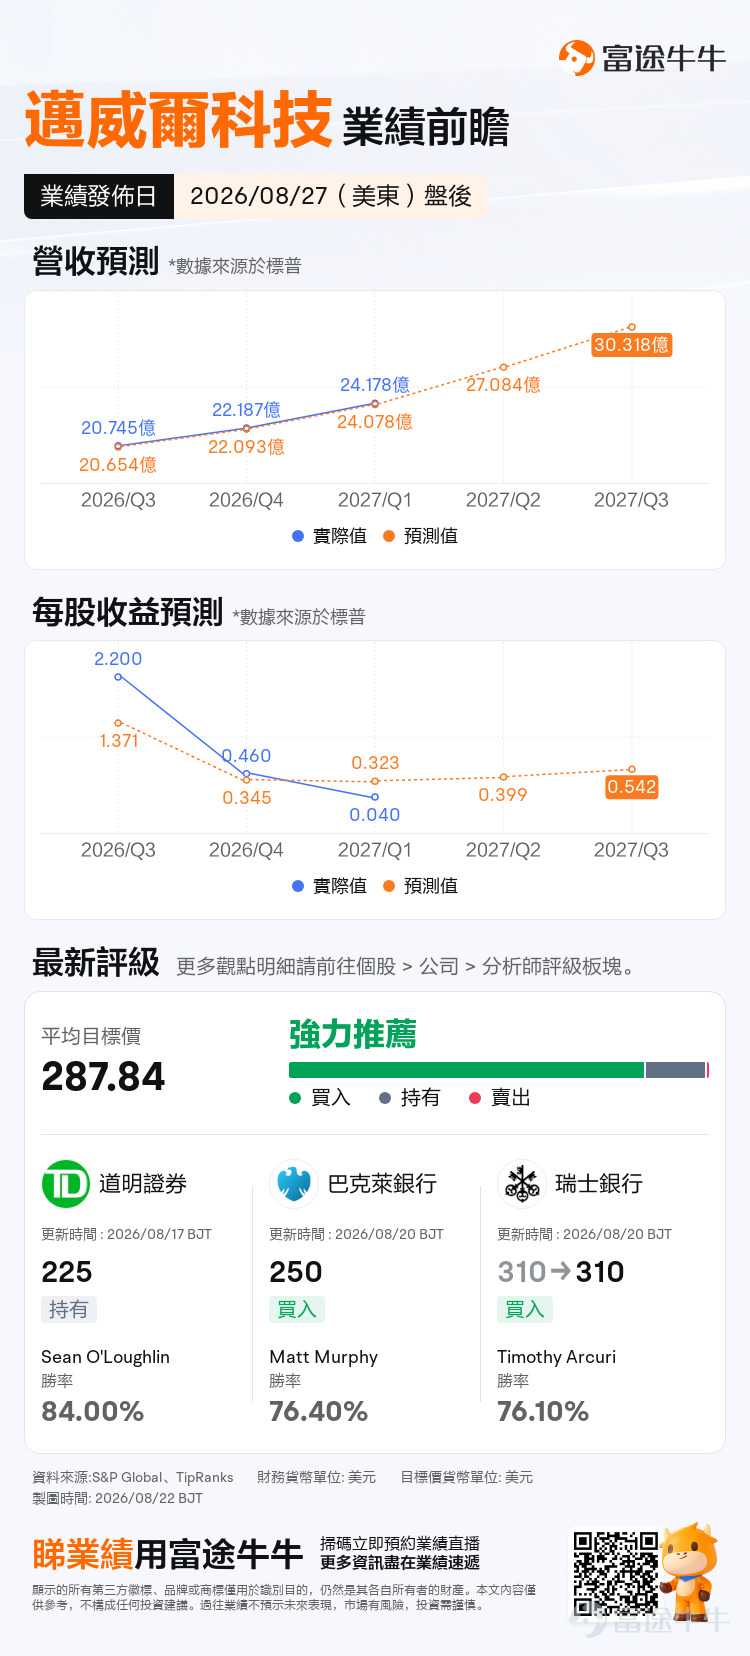
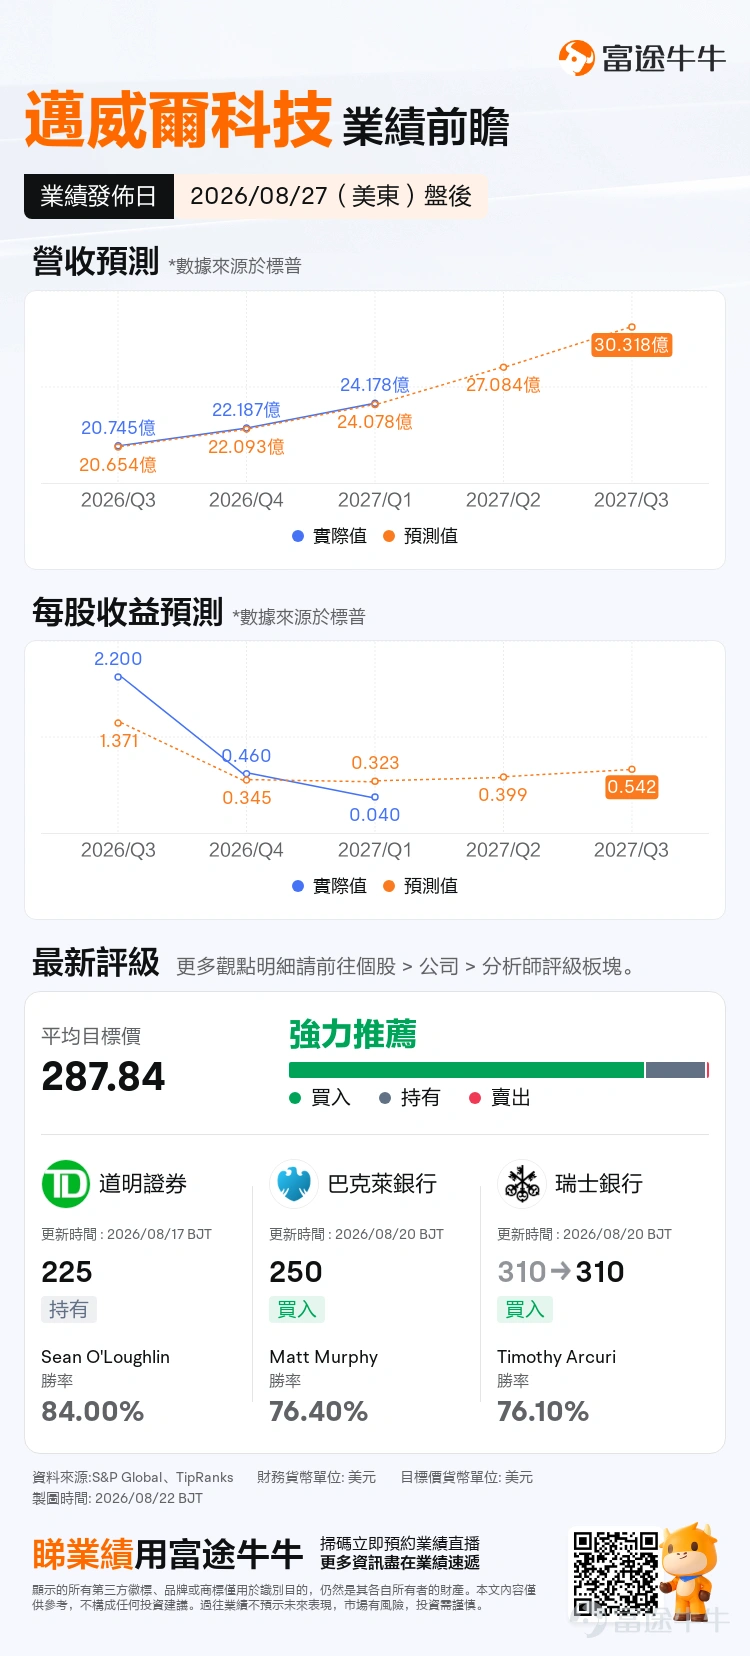
As of August 24, the market consensus for revenue was approximately $2.7084 billion,only 0.3% above the midpoint of the guidance.
What does this mean? It means the market has already priced in "meeting expectations this quarter" as the baseline assumption.
Over the past six quarters, Marvell has beaten its guidance midpoint every time. In other words, merely "meeting guidance" is now viewed by the market as nearly bearish, as it is considered a given. The real beat that can drive the stock price must involve quarterly performance significantly exceeding management's May expectations, accompanied by stronger forward-looking guidance.
The real key factor: Can Q3 and full-year guidance be raised?
If the current quarter's results are the "must-answer question," then the guidance is the "finale."
The market's consensus expectations for the next quarter (FY2027 Q3) have risen to revenue of approximately $3.03 billion,with GAAP EPS of around $0.54, representing a quarter-over-quarter increase of over 13%. Management struck a notably aggressive tone during last quarter's conference call, stating: "We expect year-over-year revenue growth to accelerate sequentially in each quarter of FY2027," citing "unusual bookings related to AI" and "significantly raising the revenue outlook for FY2027 and FY2028." The previous full-year FY2027 guidance was approximately $11.5 billion (representing roughly +40% year-over-year growth).
Therefore, what the market truly seeks confirmation on this time is:
– Will the Q3 guidance be significantly higher than the $3.03 billion consensus? If the guidance is merely mediocre, even strong quarterly results may be interpreted as a sign of slowing growth;
– Will the full-year target of $11.5 billion be revised upward? Some optimistic sell-side analysts believe there is substantial room for an upward revision;
– Can the +55% growth outlook for Data Center in FY2028 be further confirmed?
This is an earnings report where guidance matters more than the current quarter's results. This is also the fundamental reason why the options strategy discussed later favors "controlling IV crush and avoiding single-leg bets"—it is a play on the narrative, and narrative-driven expectation gaps are most likely to emerge in guidance and conference call wording.
Data Center and Gross Margin: Two Thermometers for Growth Quality
Marvell’s story is essentially the "AI Data Center" story. Last quarter, data center revenue was $1.833 billion, accounting for total revenue 76%, up approximately 27% year-over-year, serving as a structural growth engine (management guides for full-year growth of ~+50% and ~+55% by FY2028).
The other business segment, "Communications and Other" (covering carriers, enterprise networks, automotive, etc.; the company currently categorizes its end markets into these two major segments), generated approximately $585 million last quarter, accounting for about 24%. It saw a year-over-year increase of roughly 29%—but this was primarily driven by cyclical restocking following inventory corrections. Management holds a more conservative medium-term outlook for this segment (~+10% in FY2027 and low single-digit growth in FY2028).
In other words, it is still the data center business that truly supports the valuation narrative, while the communications business is stabilizing rather than accelerating.
This time, keep an eye on two key indicators:
1. Whether the data center's revenue share and growth rate can be sustained(i.e., whether it still accounts for ~76% and whether the year-over-year growth rate remains on track with management's full-year guidance of ~+50%). This determines "whether AI growth is still accelerating";
2. Whether Non-GAAP gross margin can reach the upper end of the guidance range of 58.25%–59.25%(last quarter was 58.9%, with the market expecting ~59% this time). The product mix, including custom XPUs (ASICs), will impact gross margins. Only if "revenue accelerates" while "gross margins expand" can it truly prove economies of scale, rather than simply trading price for volume.
Google Partnership: The Market Wants Progress, Not Just Frameworks
This is the biggest catalyst for the stock price recently and the key strategic highlight of this earnings report.
On August 19, Marvell disclosed a strategic partnership with Google: Google was granted warrants for up to approximately 58.97 million shares(representing about 6.7% of existing share capital), with an exercise price of $206.58. The notional value would be approximately $12.18 billion if fully exercised.
But the key lies in the terms—approximately 97.7% are subject to performance-based vesting: A tranche (out of 240 total tranches) unlocks for every $500 million of custom products Google purchases from Marvell, with the term extending to FY2033; only about 2.3% vests quarterly based on time.
In other words, this $12.18 billion is the "notional cap upon full realization," neither representing capital invested by Google today nor committed revenue; it ties Google'sprocurementand itspotential shareholdingare tied together, representing a long-term alignment of interests, while also implying potential dilution.
The scope of cooperation covers AI inference accelerators, storage controllers, network and memory interface controllers, near-memory computing, etc.; management states there is "a cumulative TAM opportunity of approximately $120 billion by FY2033"—note that 240 batches × $500 million equals exactly $120 billion, which corresponds to the cumulative procurement amount required for full warrant vesting. The stock price rose +9.85% on the day of the announcement and another +5.79% the following day.
But the market's current concern has shifted to progress:
– Google orders'revenue recognition progress(warrants unlock per $500 million in revenue, effectively tying "orders" directly to "revenue," serving as a strong verification anchor);
– Microsoft ASIC mass production timeline (the market believes procurement volume could exceed 1 million units, generating an additional $1–2 billion in revenue);
– Whether there areNew hyperscale cloud customer。
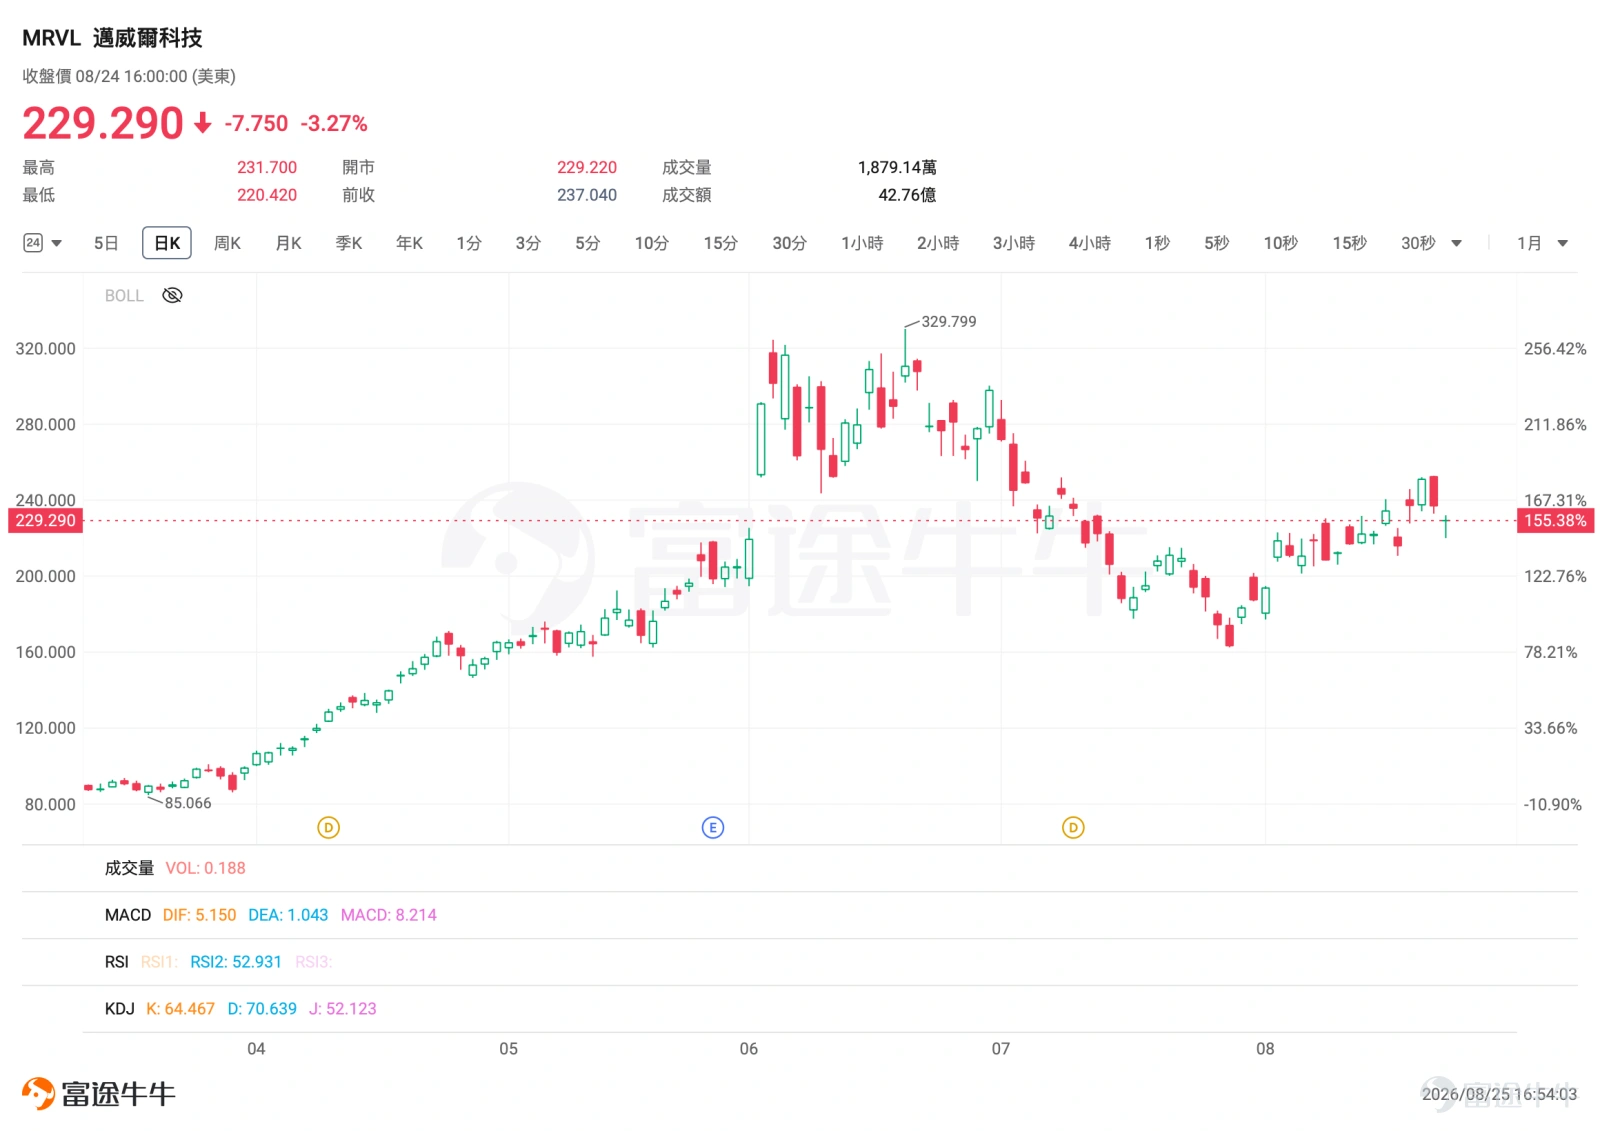
Options market signal: Betting on high volatility, but beware of IV Crush
Based on closing data as of August 24, let's first look at how much volatility the market has priced in for the earnings report:
– The implied one-day move is approximately ±13%. The market has priced in a significant single-day swing for this earnings release, which can be roughly viewed as starting from ±10%.;
– Current IV is around 80%, with an IV Percentile of 65%(upper-middle range over the past year), which is not extreme; however, note that the IV for options contracts expiring during the 8/28 earnings cycle has reached as high as 132%–140%—this implies that once the earnings are released, the IV Crush (sharp drop in implied volatility) will be very severe;
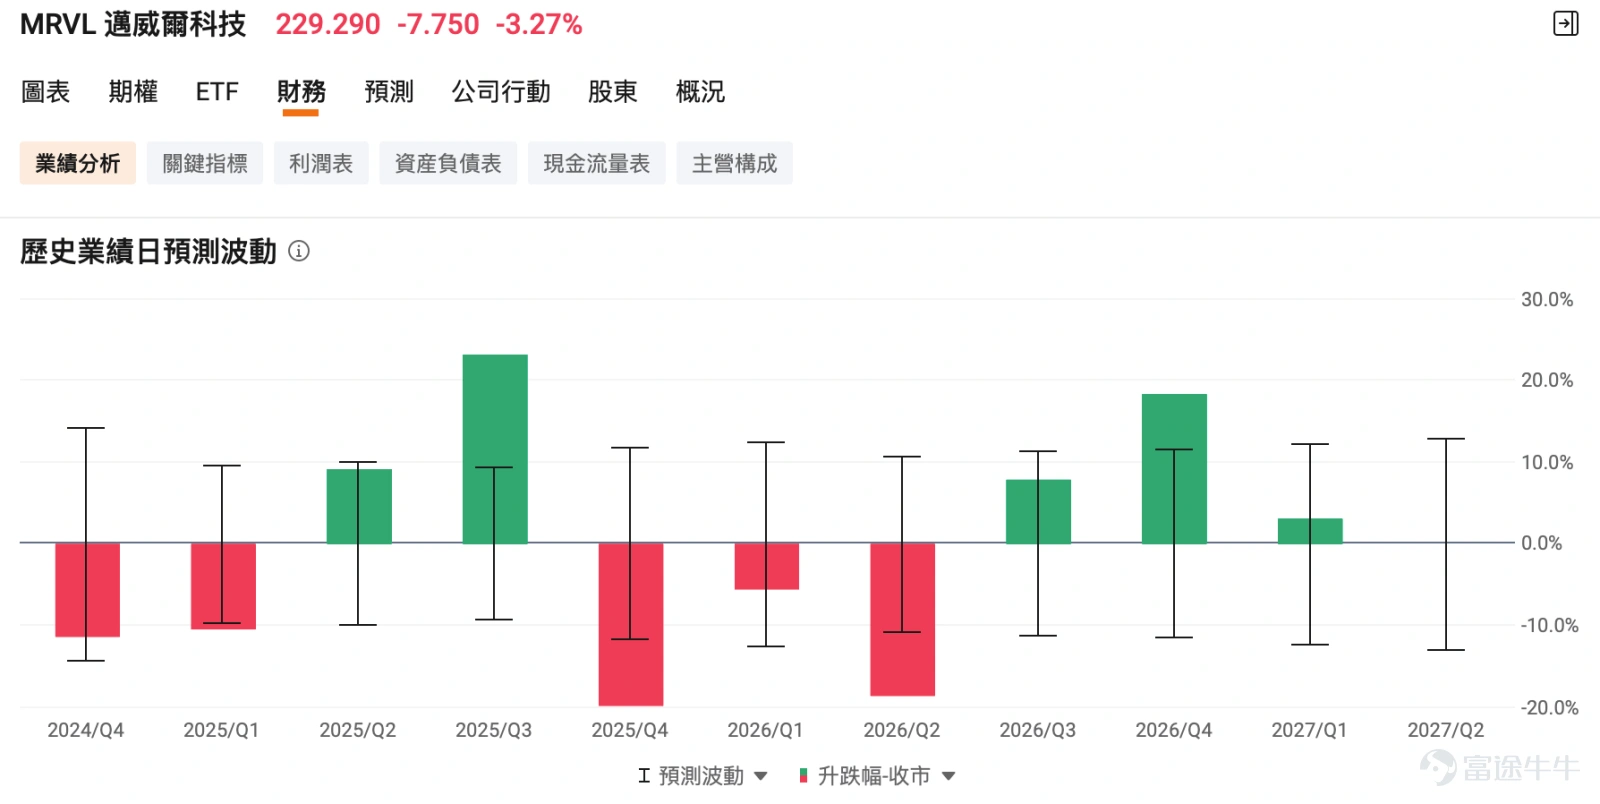
– Moreover, MRVL has historically shown large single-day swings around earnings—averaging ±13.06% over the past 8 reports, with a maximum move of +23.19% / -19.81%. Even though the current implied ±13% is similar to the historical average,the tail risk of a violent gap remains;
– In terms of trading structure, recent options activity has been dominated by calls (Put/Call Ratio mostly between 0.4–0.6), but open interest shows slightly more puts (~956k contracts) than calls (~866k contracts). Large orders show mixed bullish and bearish sentiment—there are both sellers of near-term Calls to collect high IV, and long-term bullish strategies involving buying far-term Calls and selling far-term Puts.These should only be treated as sentiment indicators and cannot be used to definitively determine the direction of "smart money."
A one-sentence summary of the options landscape:Options are not cheap this time; Implied Volatility (IV) is extremely high during earnings week, posing a significant risk of an IV crush. Even if you get the direction right, buyers may still incur losses due to falling IV and time decay if the actual price move is smaller than the implied volatility range (approximately ±10%~14%).
Options Strategy:
The following strategies are based on the assessment of "high IV + significant IV crush risk during earnings week + strong fundamentals but crowded valuations + guidance being the key determinant."All involve structures with limited risk and do not include naked option selling.
Strategy 1: Bull Call Spread — Bullish bias with IV control
– Target Investors: For investors who are optimistic about guidance upgrades or the fulfillment of Google's orders but are concerned that profits from a long call position could be eroded by an IV crush after earnings.
– Strategy: Buy one at-the-money call and simultaneously sell one call with a higher strike price near the upper bound of implied volatility. Choose an expiration date one to two weeks after earnings to avoid the most extreme IV levels during earnings week.
– Rationale: The premium collected from the short leg offsets the high IV cost of the long leg and significantly reduces sensitivity to declines in IV.
– Maximum Risk: The maximum loss is limited to the net premium paid (long leg minus short leg). If the stock price drops after the earnings report, the full amount is lost; meanwhile,profits are capped by the short leg,missing out on extreme upside potential.
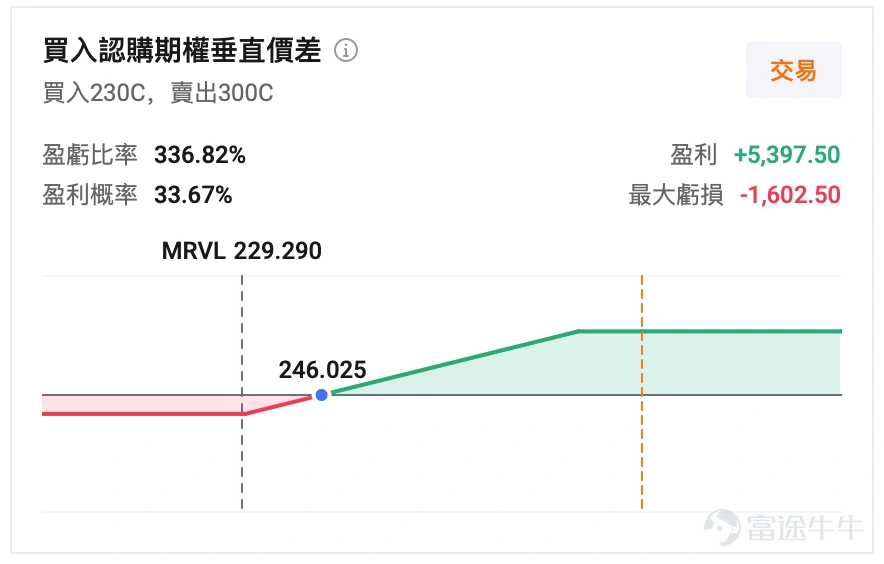
(The illustrative graphics shown on screen are for demonstration purposes only and do not constitute investment advice or guarantees; market conditions change frequently, and the displayed option prices do not reflect real-time data.)
Strategy 2: Iron Condor — Shorting inflated IV (Advanced only)
– Target Investors: For experienced investors who believe implied volatility is overly inflated and that the stock price will remain within a range after the earnings report, aiming to profit from an IV crush.
– Strategy: Simultaneously establish call and put spreads — sell OTM Calls outside the implied volatility range and buy higher-strike Calls for protection; simultaneously sell OTM Puts and buy lower-strike Puts for protection. The core profit sources are the post-earnings IV collapse and time decay.
– Rationale: With pre-earnings IV reaching 130%+, the premiums from the short legs are substantial. As long as the stock price stays between the two short strike prices after the earnings report, you can keep the entire net premium. Maximum loss is strictly capped by the protective legs, avoiding the unlimited risk of naked short positions.
– Maximum Risk (Key Point): MarvellHistorical earnings reports have always exhibited significant single-day volatility.(The maximum single-day move has been +23% / -20%, exceeding the implied ±10%~14%). Once a violent gap post-earnings penetrates the sell side, losses can quickly approach the maximum. Shorting volatility on this stock is by no means a "safe income" strategy; the win rate is dragged down by elevated realized volatility, so position sizing must be strictly controlled.
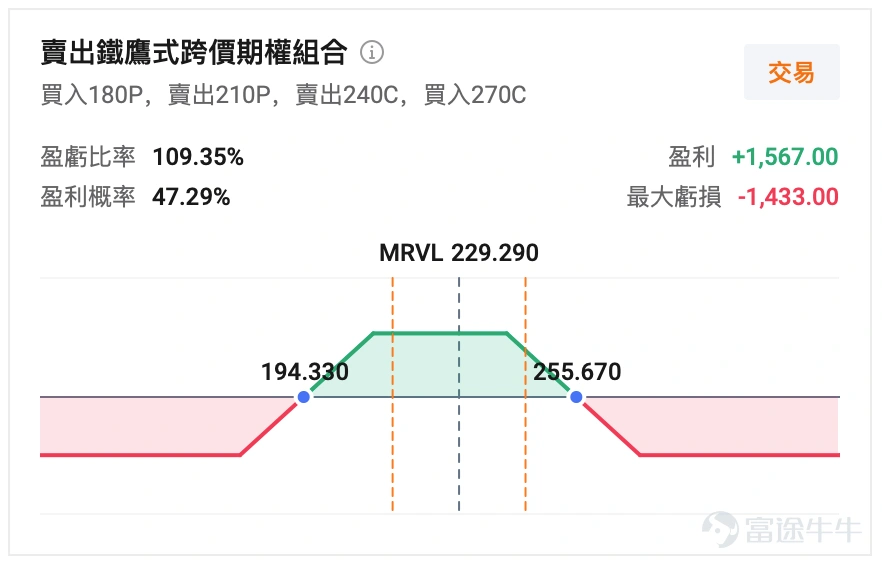
(The illustrative graphics shown on screen are for demonstration purposes only and do not constitute investment advice or guarantees; market conditions change frequently, and the displayed option prices do not reflect real-time data.)
Overall, if MRVL's Q3 guidance significantly beats consensus, full-year estimates are raised, Google/Microsoft orders provide substantive direction, and gross margins hit the upper bound—even if the quarter merely meets expectations—valuation could find support or even be re-rated higher. In such a scenario, realized volatility may exceed implied volatility, making directional and long-volatility strategies more advantageous.
Disclaimer
This content does not constitute an offer, solicitation, recommendation, opinion, or guarantee regarding any securities, financial products, or instruments. The risk of loss in trading options can be substantial. In certain circumstances, your losses may exceed the initial margin deposited. Even if you set backup instructions such as "stop-loss" or "limit" orders, losses may not be avoided. Market conditions may prevent the execution of such orders. You may be required to deposit additional margin within a short period. If the required amount is not provided within the specified time, your open positions may be liquidated. However, you remain responsible for any deficit in your account resulting from this. Therefore, before trading, you should research and understand options, and carefully consider whether such trading is suitable for you based on your financial situation and investment objectives. If you trade options, you should be familiar with the procedures for exercising options and at expiration, as well as your rights and obligations when exercising options and at expiration. Options trading involves high risk and is not suitable for all investors. Before engaging in any options trading strategy, investors should carefully read "Characteristics and Risks of Standardized Options" 。
Finally, Option Sir brings a small benefit for fellow investors. Welcome to claim it. Options Starter Pack
*This event is limited to invited HK users. Click to learn more. Detailed terms and conditions of the promotion >>
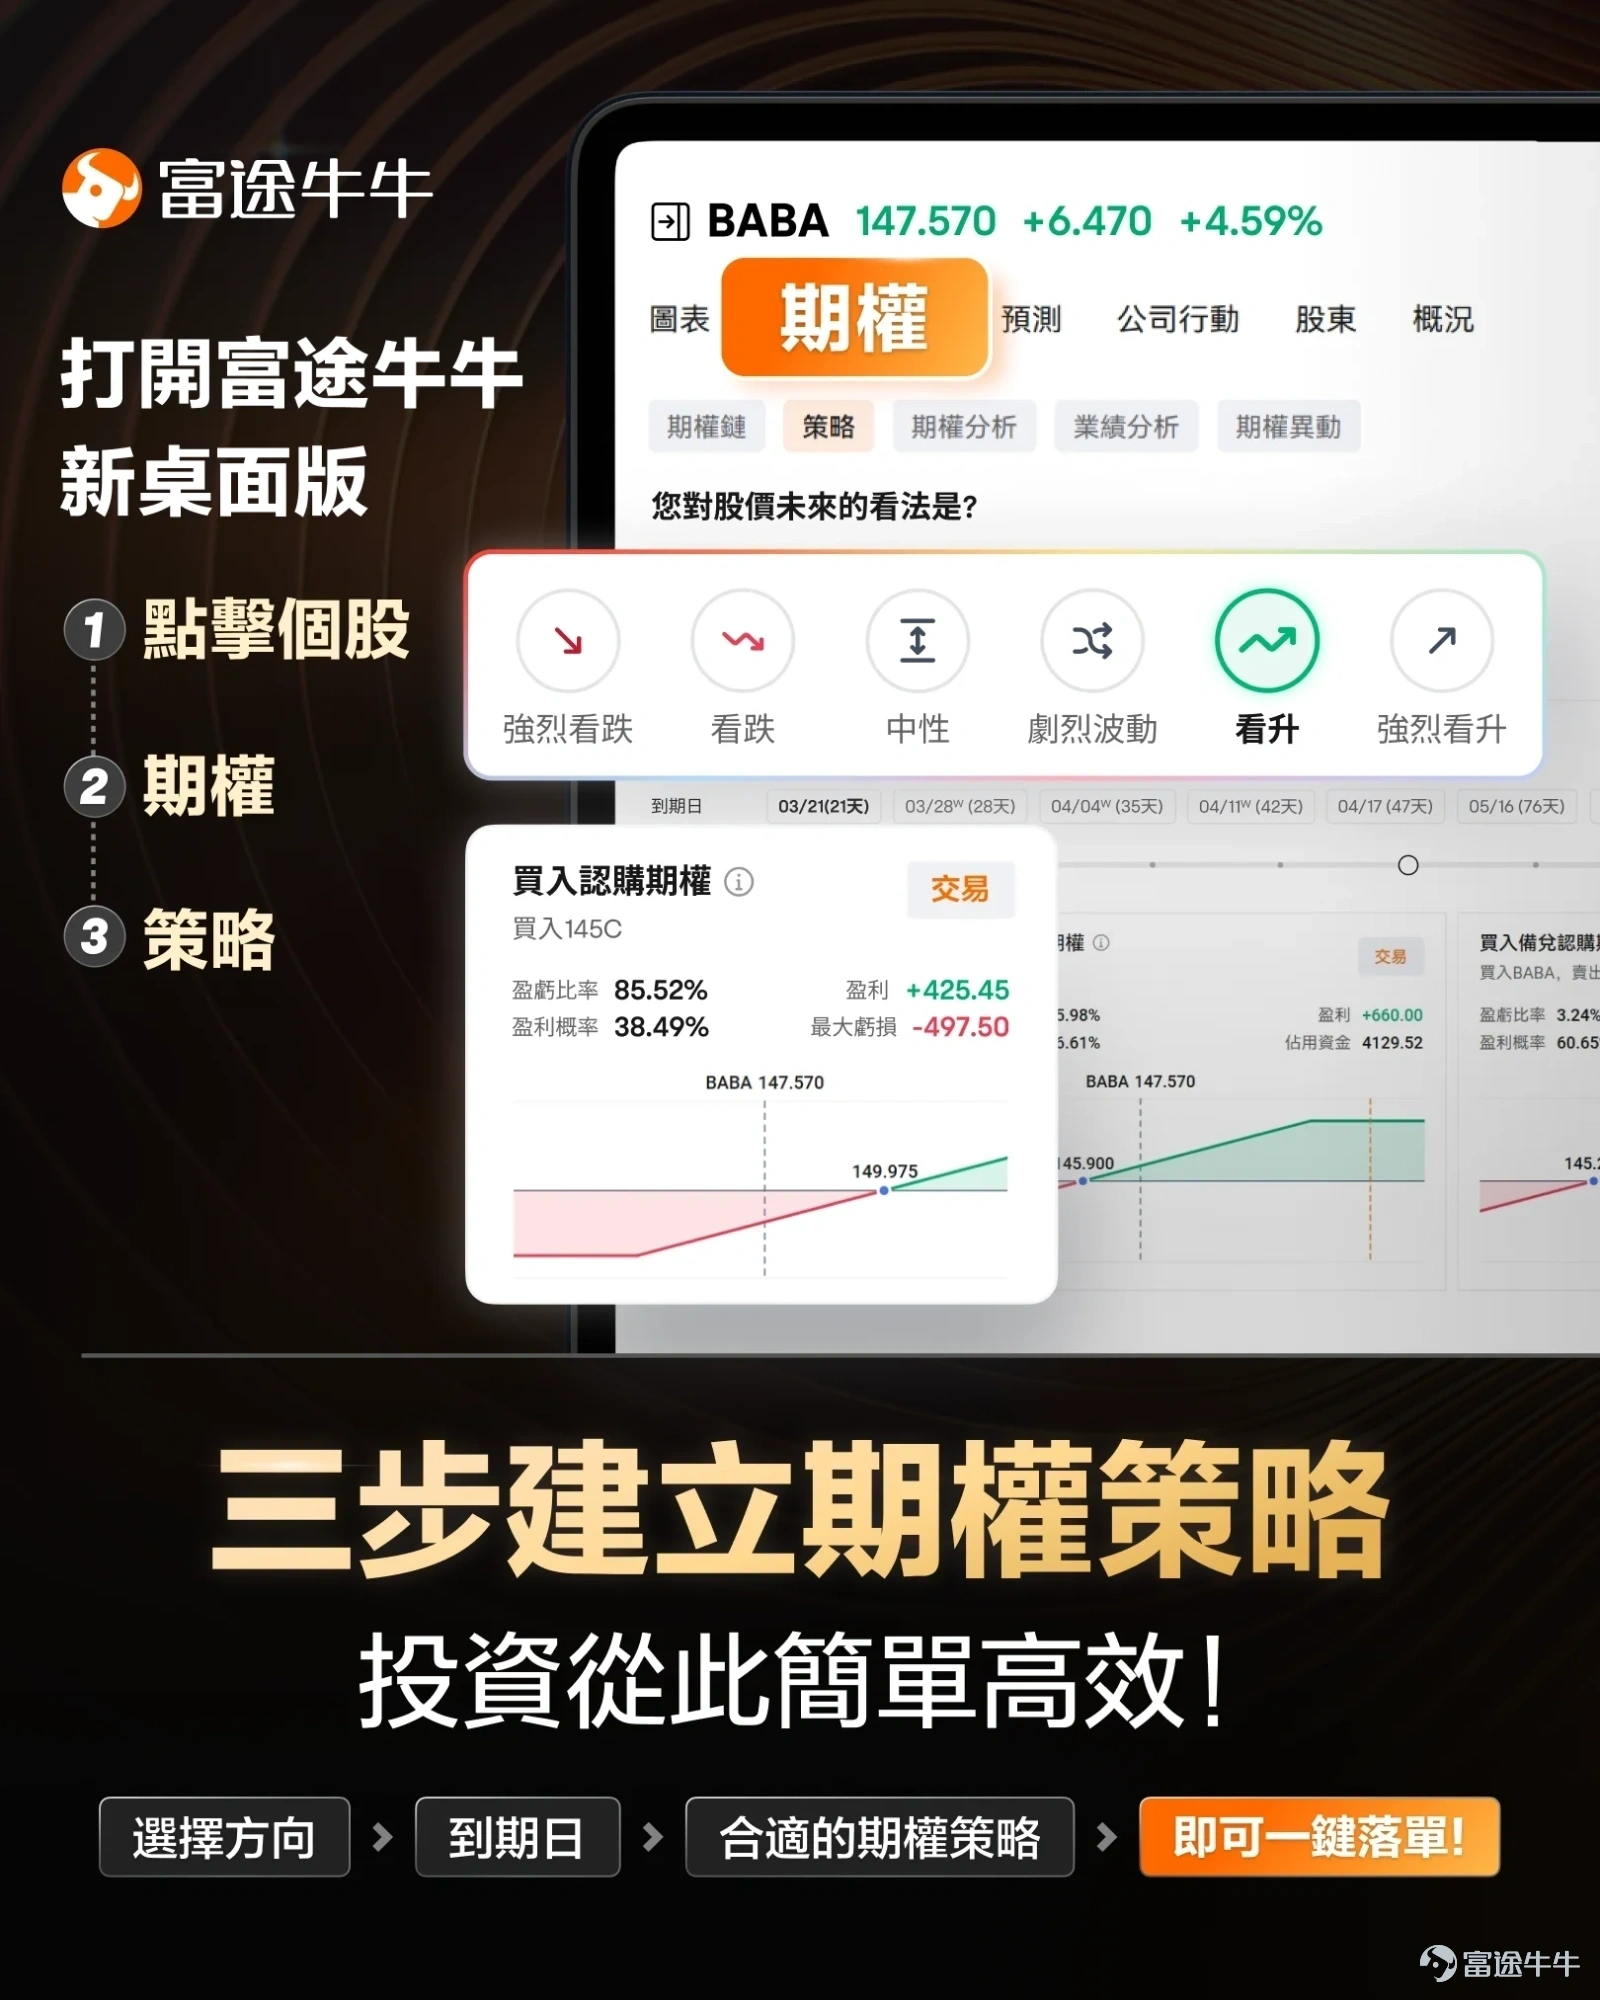
Market conditions are complex and volatile, Options strategies with numerous choices, unsure how to select? Futubull helps you build in three steps Options strategies , making investing simple and efficient from now on.
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more


Comment (1)
to post a comment
36
57