Is the food delivery war coming to an end? Meituan's Q2 profits exceed expectations
Hot Stock Commentary | Summary of Alibaba's 1QFY27 Earnings and Guidance
💡 Key Takeaways
- FY27 Q1 revenueRMB 268.953 billion, year-on-yearGrew by 9%, slightly above the Bloomberg consensus estimate.
- Profitability was dragged down by AI investments; adjusted EBITA year-over-yeardeclined by 30%, and Non-GAAP net profit year-over-yeardeclined by 38%, significantly below expectations.
- Cloud and AI were the only high-certainty growth drivers this quarter: revenue from AI cloud and computing power services increased by 45% year-over-year. Management guided that growth in the September quarter is expected to exceed 50%, and expressed confidence in achieving $100 billion in external cloud revenue and a margin above 20% by 2030.
- Capex this quarterThe RMB 67.7 billion figure far exceeded expectations, acting as a short-term drag; however, the company remains optimistic about its ROIC guidance for AI capital expenditures and roughly projects free cash flow to turn positive by FY29. E-commerce continues to be constrained in the short term by weak domestic demand and a high base effect, but high-frequency data indicates quarter-on-quarter improvement in shelf-based e-commerce for both JD.com and Alibaba in Q3.
The current stock price has largely priced in the e-commerce weakness. Future catalysts will depend more on accelerated growth in AI + Cloud and margin improvement.
▎ Financial Performance
In FY27 Q1 (the quarter ended June 30, 2026), Alibaba achieved revenue ofRMB 268.953 billion, a year-over-yeara 9% increase,surpassing the Bloomberg consensus estimate of 8.4%. Revenue slightly beat expectations, with growth primarily driven byCloud business and instant retail.。
On the profit side, results were impacted by increased technology investment: Adjusted EBITA wasRMB 27.329 billion, down 30% year-over-year; Non-GAAP net profit wasRMB 20.715 billion, down 38% year-over-year.Revenue slightly exceeded expectations, while profit fell short; the core issue lies in the front-loading of AI capital expenditures and model investments.
▎Business Segment Breakdown
Alibaba E-commerce Business Groupachieved revenue of RMB 205.862 billion, with instant retail revenue rising 45% year-over-year to RMB 53.3 billion; the E-commerce Business Group's adjusted EBITA year-over-yeardeclined 1% to RMB 39.7 billion, beating expectations.
AI cloud and computing power servicesGenerated revenueof RMB 48.4 billion, with income from external customers also showing a year-on-yearincrease of 45%. The segment's EBITA margin reached11.6%. Revenue from AI-related products reachedRMB 12.376 billion, with the corresponding ARR (Annual Recurring Revenue) for this quarter atRMB 49.5 billion(USD 7.3 billion), marking the twelfth consecutive quarter of triple-digit year-on-year growth,ARR for the September quarter is expected to approach $10 billion。
Management stated that, excluding the impact of consolidating T-Head, cloud business margins would actually be higher, reaching the forward-looking target20% profit marginthe pace will be faster.
AI Labs and Applicationsachieved revenueRMB 3.338 billion, +16% year-over-year. Adjusted EBITA was-RMB 13.861 billion** (vs. -RMB 3.224 billion in the same period last year), mainly due to increased investments in AI models and higher inference costs for the Qianwen App.
Capital expenditure (Capex) reached RMB 67.7 billion this quarter(RMB 26.9 billion in FY26 Q4 and RMB 38.7 billion in FY26 Q1), primarily driven by chipprocurement and rising prices.Similar to Tencent, Alibaba's Capex this quarter alsosignificantly exceeded the expected RMB 36 billion. Management stated that the three-yearRMB 380 billionAI investment plan had accumulatedRMB 190 billionby Q2 2026, in line with expectations.
Management's performance guidance
Regarding AI + Cloud,the annualized revenue target for MaaS in 2026 remains to be reached by year-end,RMB 30 billion,with hopes of achieving it ahead of schedule.Currently at approximatelyRMB 16 billion.;
Gross margins for self-developed and third-party open-source models are similar. Management guided thatAlibaba Cloud's growth rate will exceed 50% in the September quarter,and growth rates for the subsequent December and March quarters are expected to be revised upward further. Performance growthShort-termis driven by the surge in inference demand and increased pricing for computing power.Long-termLeveraging economies of scale in data centers, cost reductions from self-developed chips, and pricing capabilities of self-developed models.
The company remains confident that external cloud revenue will reach $100 billion with profit margins exceeding 20% by 2030.
E-commerce faces short-term challenges, while focusing on supply-side upgrades and AI empowerment in the long term. Performance of core merchants during the 618 shopping festivalmet expectations, and an e-commerce-specific AI agent will be launched in collaboration with Tongyi Qianwen Office.
Taobao Flash Salessaw user and order growth last quarteruser and order growth'swhile unit economics (UE)Continued optimization has significantly narrowed losses. Going forward, the company will accelerate the integration of Hema, Tmall Supermarket, and its front warehouse network. Non-food GMV is expected to surpass food GMV in the next fiscal year.Achieve overall profitability in FY29, with instant retail expected to contribute to the platform's total GMV over the long term30%。
Free cash flowRegarding [specific aspect], the company roughly expects that byFY29, it will turn positive. Sell-side consensus expects Alibaba Cloud's Capex ROIC to be around13%, but management believes sell-side estimates may be conservative. The current ROIC on new investments already exceeds sell-side expectations, while existing assets acquired at lower costs in the early stages deliver even higher ROIC.
Front-loaded investments can drive sustainable returns:As customer demand and revenue continue to grow rapidly, revenue growth is expected to far outpace the growth rate of new capacity, thereby driving compounding growth in revenue, free cash flow, and ROIC.
▎ Strategic Integration
Alibaba Group this quarteradvanced the integration of its business strategy,leveraging synergies across e-commerce platforms and strengthening full-stack AI capabilities. The adjusted new business segments are divided intofour major categories:Alibaba E-commerce Business Group (China Commerce + Alibaba International Digital Commerce + Freshippo), AI Cloud & Computing Services (Cloud Intelligence Group + T-Head), AI Labs & Application Businesses (AI Model Lab + Tongyi Consumer Business Group + Tongyi Enterprise Services), and Other Businesses.
▎Alibaba's Long-Term Outlook on the AI Industry
The AI industry is still in its early stages, with value dynamically flowing among chips, cloud infrastructure, models, and applications.Therefore, the company remains committed to full-stack investment. In the current phase of computing power shortage, commercial value is more concentrated at the chip and cloud infrastructure layers.
APIs are merely a transitional business model for models; the long-term value of models lies in the direct delivery of products and business outcomes. Meanwhile, T-Head's self-developed chips have achieved scaled commercial deployment.Continuously capture industrial value through the synergy of "chips + cloud + models" in the future.
💡 Summary
The market is paying closer attention to Alibaba Cloud's growth rate and ROI. This quarter's higher-than-expected capital expenditure became a drag. The company's earnings guidance, particularly regarding ROIC on AI Capex, remains optimistic.There is high certainty that cloud business growth will remain above the 40% level.。
In the e-commerce sector, weak domestic demand combined with a high base from last year has put pressure on all HK-listed e-commerce stocks. However, high-frequency data shows that both JD.com and Alibaba's Q3 e-commerce businesses improved quarter-over-quarter, indicating a divergence in performance: shelf-based e-commerce is stabilizing, while video-based e-commerce is weakening.Alibaba's e-commerce business is expected to stabilize in the second half of the year.。
The current stock price has rebounded significantly from its lows, largely pricing in the weakness in e-commerce.Future stock price catalysts will likely stem from accelerated growth in Alibaba's AI + Cloud business and margin improvement.。

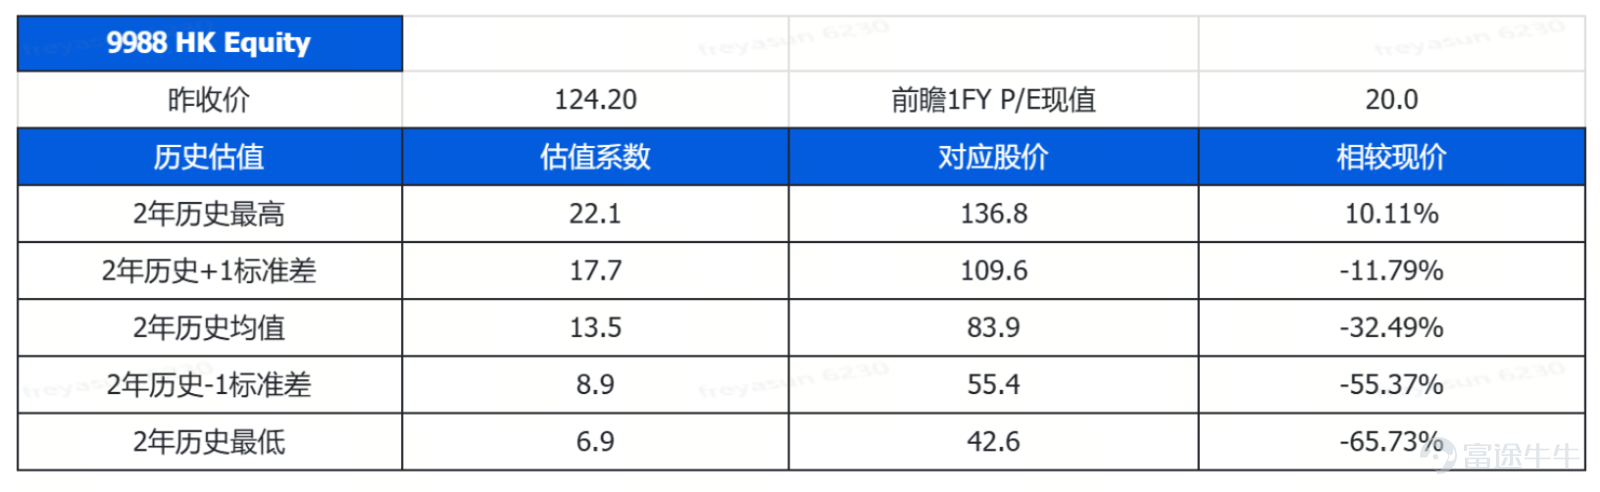
As shown in the table above, Alibaba (9988.HK) closed yesterday atHKD 124.20, with a forward one-year P/E ratio of approximately20.0x, falling between the two-year historical high of 22.1x and +1 standard deviation at 17.7x, significantly higher than the two-year historical average of 13.5x.
This report is prepared by Futu Securities International (Hong Kong) Limited (“Futu Securities”). Without the prior written consent of Futu Securities, this report and the information contained herein may not be (i) reproduced, copied, or stored in any form, or (ii) directly or indirectly distributed or forwarded to any other person for any purpose. The information in this report is derived from sources that Futu Securities believes to be correct and reliable at the time of publication; however, this report is not intended to contain all information required by investors and may be affected by factors such as delivery delays, obstacles, or interception. Futu Securities makes no express or implied warranty or representation regarding the adequacy, accuracy, completeness, reliability, or fairness of such information or opinions. Therefore, neither Futu Securities nor its affiliates (collectively, the “Futu Group”) shall bear any liability for any type of loss (including but not limited to direct, indirect, or consequential losses) arising from any actions taken by third parties in reliance on the contents of this report. The views, recommendations, suggestions, and opinions expressed in this report do not necessarily reflect the positions of Futu Securities or its affiliates and are subject to change without notice; Futu Securities has no obligation to provide updates to such information or opinions. This report is provided for general informational purposes only and is intended for general review by clients of Futu Securities, rather than considering the specific investment objectives, financial status, or particular needs of any specific recipient. No information or opinion in this report constitutes or should be deemed as a proposal, recommendation, or solicitation by any member of the Futu Group to purchase or sell any securities, investments, or other financial instruments. Nor shall it be construed as an offer or invitation to buy or sell securities. Any decision to purchase the securities mentioned in this research report should take into account existing public information, including any prospectus related to such securities. The products mentioned in this report may not be suitable for all investors; readers should fully consider relevant factors and seek professional advice before making any investment decisions. This report is provided to a recipient on the basis that the recipient is deemed capable of independently assessing investment risks and exercising independent judgment in investment decisions. For certain jurisdictions or countries, the distribution, issuance, or use of this report may violate local laws, regulations, rules, or other registration or licensing requirements. This report is not intended for distribution to or use by any person or entity in such jurisdictions or countries. Investors in Hong Kong with any questions regarding Futu Securities’ research reports should contact Futu Securities directly. The Central Entity Number of the Hong Kong SFC license held by the author of this report is disclosed next to the author’s name on the first page of the report. The analyst primarily responsible for writing this report confirms that (i) the opinions expressed in this report accurately reflect his/her personal views on the listed corporations commented on in this research report; and (ii) no part of the compensation he/she has received, whether in the past, present, or future, directly or indirectly, is related to the specific recommendations or views expressed in this report. The analyst confirms that neither the analyst nor his/her associates have traded in the listed corporations and related securities mentioned in the report within 30 days prior to the release of the research report and within 3 business days after its release. Neither the analyst nor his/her associates serve as senior management of the listed corporations commented on in this research report, nor do they hold any financial interests therein. In this report, Futu Securities does not hold any financial interest amounting to 1% or more of the market capitalization of the listed company, and has had no investment banking relationship with the company in the past 12 months. Employees of the Company are not employees of the listed company.
Content Disclosure: Personal opinion
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more
Comments
to post a comment
1