English
Back
Open Account
钛媒体APP
wrote a column · Aug 10 21:00

In Luckin Coffee's second-quarter report, we saw signs that growth has peaked.

(This article is authored by Financial Report Notes, published by TMTPost with authorization)
By Financial Report Notes
On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce.
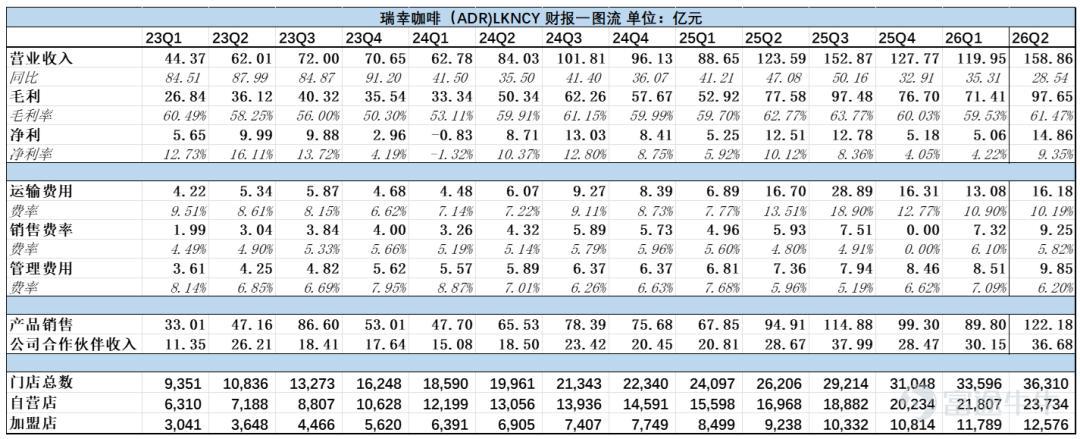
In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million.
Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level.
In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion.
Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations.
(See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
Our core viewpoints are as follows:
Store-level economics are showing diminishing marginal returns, yet scale expansion continues to deliver solid growth. Second-quarter revenue exceeded expectations at RMB 15.886 billion, primarily driven by accelerated store densification across its nationwide network of 36,000 stores. However, same-store sales growth (SSSG) declined by 5.3%, average daily revenue per store fell by 9.5%, and monthly unique customers per store dropped by 11.6%—all reflecting double-digit declines.
Narrowing discounts and a high takeout pickup ratio have driven cost optimization and efficiency gains on the profitability front. Thanks to a slight rebound in average selling price (ASP) to the RMB 11.9–12.9 range, along with the substitution of high-cost delivery orders by convenient 'walk-down pickup' enabled by dense store coverage, delivery expenses as a percentage of revenue dropped sharply by 3.3 percentage points year-over-year to 10.2%. Non-GAAP net income reached RMB 1.753 billion (+22.8%), indicating that Luckin Coffee is gradually moving past the impact of the RMB 9.9 pricing war.
Overall, Luckin Coffee’s second-quarter financial results were solid, but they only addressed market concerns regarding scalability limits and the pricing war. The contraction in store-level productivity has also exposed underlying issues to the market.
Luckin Coffee’s total revenue this quarter exceeded market expectations. In the second quarter of 2026, the company reported net revenue of RMB 15.886 billion, up 28.5% year-over-year; gross merchandise value (GMV) for the same period reached RMB 18.4 billion, an increase of 29.8% year-over-year.
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
Overall, this quarter’s revenue reflects a growth strategy prioritizing scale over quality—aggregate performance was strong, but signs of peaking growth rates and per-store dilution indicate mounting pressure on growth quality. We conduct an in-depth analysis from two dimensions: revenue composition by business segment and store-level operating quality.
Breaking down revenue, both product sales revenue (from company-operated stores and official online channels) and partner revenue (primarily franchise fees) saw significant increases this quarter.
In Q2 2026, product sales revenue reached RMB 12.218 billion, up 28.73% year-over-year, though growth slowed by 15.8 percentage points compared to the same period in 2025. Revenue from freshly prepared beverages totaled RMB 11.155 billion, accounting for 70.2% of total product sales. Core self-operated store revenue reached RMB 11.564 billion, up 26.6% year-over-year, while same-store sales growth (SSSG) for self-operated stores stood at approximately -5.3%, marking the third consecutive quarter of decline.
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
Source: Luckin Coffee Second Quarter 2026 Earnings Presentation
During the same period, partner revenue reached RMB 3.668 billion, up 27.94% year-over-year, though growth decelerated sharply by 27.03 percentage points compared to the same period in 2025. Franchise store revenue amounted to RMB 3.668 billion, up 27.9% year-over-year, with growth slowing by 27.1 percentage points compared to Q2 2025.
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
Source: Luckin Coffee Second Quarter 2026 Earnings Presentation
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
Revenue growth was primarily driven by store network expansion and an increase in the average monthly number of transacting customers:
As of Q2 2026, Luckin Coffee operated a total of 36,310 stores globally, adding a net 2,714 stores this quarter. This includes 23,734 self-operated stores and 12,576 franchise stores.
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
The monthly average number of transacting customers this quarter reached 112.7 million, an increase of 22.9% year-over-year, with over 25 million new transacting customers added in the quarter alone. As of the end of Q2 2026, Luckin Coffee’s cumulative number of transacting customers has approached 500 million, and the average monthly number of drinks per customer hit a record high.
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
Source: Luckin Coffee Second Quarter 2026 Earnings Presentation
On the flip side of continued scale expansion is the simultaneous emergence of slowing revenue growth and declining per-store productivity. The core reasons stem from two factors:
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
(1) External factor: Absorption of the high base effect from Q2 2025. In the same period of 2025, intense subsidies from food delivery platforms significantly boosted online transaction volumes and GMV, creating a high base that is now challenging to surpass.
(2) Internal factor: 'Internal cannibalization' caused by higher store density. Combining store and customer data, we estimated Luckin Coffee’s per-store output and average monthly customers served per store for this quarter. The results indicate that denser store deployment has clearly diluted per-store productivity:
In terms of per-store output, company-operated stores generated average quarterly revenue of approximately RMB 487,000 per store in Q2 2026, or roughly RMB 5,414 in daily revenue per store. By comparison, in Q2 2025, company-operated stores reported total revenue of RMB 9.136 billion with 16,968 stores at period-end, translating to average quarterly revenue of about RMB 538,000 per store and daily revenue of roughly RMB 5,982 per store. This represents a year-over-year decline of approximately 9.5% in daily revenue per store. While the number of company-operated stores increased by about 40% year-over-year in Q2 2026, total revenue from these stores grew by only 26.6%—indicating that store count growth outpaced revenue growth, making the decline in per-store output almost inevitable.
In terms of users served per store, based on an estimated quarterly average of 34,953 stores, each store served approximately 3,224 transacting customers per month this quarter, down about 11.6% from 3,646 customers per store per month in the same period of 2025. While total store count expanded by approximately 39% year-over-year, total transacting customers grew by only about 23%—indicating that store growth significantly outpaced customer growth, inevitably leading to a decline in per-store user coverage.
This quarter, Luckin Coffee sustained overall revenue growth through its high-density store network and a large influx of new users. However, comparable-store sales growth from existing stores came under pressure, with both per-store output and per-store service volume declining—signaling that the company is facing diminishing marginal returns, characterized by 'adding stores without adding efficiency.'
This quarter, Luckin Coffee reported a gross profit of approximately RMB 9.77 billion, with an overall gross margin of 61.5%, placing it among the industry leaders. Compared to the same period in 2025, the gross margin increased by approximately 1.7 percentage points year-over-year.
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
The improvement in gross margin this quarter was primarily driven by a rebound in actual average selling price (ASP) and tighter discount controls.Compared to its previous aggressive subsidy strategy of uniform nationwide discounts at RMB 9.9 per cup, Luckin implemented more refined product-tiered pricing this quarter. By reducing the issuance of large-value coupons and raising the effective payment threshold for certain regular and best-selling products (e.g., to the RMB 11.9–12.9 range), the company achieved a modest ASP recovery.
Raw material costs remained relatively stable in the second quarter, with material cost as a percentage of revenue rising 1.7 percentage points year-over-year to 38.6%. Rapid top-line expansion helped absorb the pressure from higher material costs, allowing gross margin to remain elevated.
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
Source: Luckin Coffee Second Quarter 2026 Earnings Presentation
On the net profit front, GAAP net income this quarter amounted to RMB 1.486 billion, up 16.1% year-over-year; Non-GAAP net income reached RMB 1.753 billion, increasing 22.8% year-over-year. GAAP net margin stood at 9.4%, down approximately 1 percentage point from 10.4% in the same period of 2025.
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
The significant increase in net profit this quarter was largely attributable to effective cost control, particularly reflected in optimized delivery expenses.
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
In Q2 2026, delivery expenses amounted to RMB 1.619 billion, representing a delivery fee rate of 10.2%, down 3.3 percentage points year-over-year. The decline in the delivery fee rate stems from two factors:
First,as subsidies for food delivery wane,the share of delivery orders has significantly declined, while the proportion of in-store pickup orders—which incur no delivery fees—has risen sharply. Since pickup orders carry zero third-party delivery fulfillment costs, this shift in order mix directly lowered the overall delivery fee rate.
Second,The substitution effect driven by store density—'pickup right outside your door'. Luckin Coffee has achieved coverage within 100 meters in most of its store areas, enabling convenient 'pick up downstairs' options that directly replace scenarios previously reliant on delivery. Enhanced consumer willingness to pick up orders themselves has fundamentally reduced dependence on delivery services.
(This article is authored by Financial Report Notes, published by TMTPost with authorization) By Financial Report Notes On the evening of August 3, 2026, Beijing time, Luckin Coffee released its second-quarter 2026 financial results. Ahead of the earnings release, its share price had been rising steadily amid expectations of record-high revenue; however, after the report was finally released, capital market volatility intensified, and the tug-of-war between bulls and bears became extremely fierce. In the second quarter of 2026, Luckin Coffee reported total net revenue of RMB 15.886 billion, up 28.5% year-over-year, surpassing market expectations—the Bloomberg consensus estimate was RMB 15.43 billion, meaning actual revenue exceeded expectations by approximately RMB 460 million. Gross margin for Q2 2026 stood at approximately 61.5%, up 1.7 percentage points year-over-year, remaining at a relatively high level. In terms of profitability, GAAP net income for Q2 2026 reached RMB 1.486 billion, an increase of 16.1% year-over-year; Non-GAAP net income (excluding non-cash items such as stock-based compensation) was RMB 1.753 billion, up 22.8% year-over-year. Net profit margin was 9.4%, down roughly 1 percentage point from 10.4% in the same period of 2025. Profit growth lagged behind revenue growth, primarily due to rising coffee bean costs and fixed expenses associated with rapid store expansion. Overall, Luckin Coffee maintained strong revenue growth in Q2 2026, with all key metrics exceeding market expectations. (See the one-page summary of the earnings report below; all data sourced from Wind, in RMB billions unless otherwise noted.)  Our core viewpoints are as follows: Position...
In summary, we believe Luckin Coffee’s Q2 earnings report effectively answered two key questions:
First, the benefits of large-scale expansion are far from exhausted.
The ceiling for China’s coffee market remains very high. In Q2 2026, Luckin Coffee operated a total of 36,310 stores globally, adding a net 2,714 new stores in the quarter—averaging roughly 30 net new stores per day. Meanwhile, revenue growth remained close to 30% despite a high base, clearly demonstrating that the scaling-up phase in the made-to-order coffee segment is still in full swing.
Secondly, it can achieve effective growth without relying on subsidies such as the RMB 9.9 price point.
In the second quarter, Luckin Coffee’s overall average selling price (ASP) increased, driving gross margin up to 61.5%. Against a backdrop of significantly reduced delivery subsidies, monthly transacting users reached a record high of 113 million. Meanwhile, by densely deploying stores within a hundred-meter radius, Luckin enabled customers to pick up orders in person—replacing costly delivery services—and reduced its delivery fee rate by 3.3 percentage points year-over-year to 10.2%, effectively improving its fee margin.
However, Luckin’s Q2 report left certain issues unaddressed. For instance, declines in same-store sales productivity and per-store customer traffic are signaling potential diminishing returns from further scaling.
The post-earnings stock price volatility reflects a sharp clash in capital markets over Luckin’s valuation logic: bulls are betting on the defensive moat created by its 36,000-store scale and supply chain cost advantages, while bears question the declining quality of growth amid persistent same-store sales declines. At its core, this divergence represents a battle between two narratives—'absolute scale advantage' versus 'per-store output ceiling.'
From a valuation perspective, based on an estimated full-year 2026 Non-GAAP net profit of approximately RMB 5.5–6.0 billion, Luckin’s current forward P/E ratio in the U.S. OTC market has already compressed to a range of 15–18x. This valuation closely aligns with that of mature restaurant chains like Yum China.
Looking ahead, whether Luckin can break through its current valuation ceiling hinges on the realization of two key factors:
Domestically,First, whether it can halt the decline in same-store sales growth (SSSG) through product portfolio upgrades—such as bottled coffee and single-origin espresso (SOE) offerings—and achieve a bottoming-out and rebound in per-store output. Market reception of new products will directly determine when the SSSG inflection point occurs.
Internationally,Second, whether it can successfully replicate its proven domestic model of 'digital-enabled self-pickup plus ultra-efficient supply chain' to generate a second growth curve in markets such as Southeast Asia and the Middle East. Currently, Luckin operates 223 overseas stores with negligible revenue contribution—so small that it isn’t separately disclosed in financial statements—and its international expansion remains largely in pilot phases, unlikely to meaningfully boost results in the near term.
Until this transformation is fully realized, Luckin’s share price is likely to remain highly volatile within its current valuation range, heavily dependent on earnings delivery—a phase of 'value reassessment.' This Q2 earnings report answered the question of whether the company can make money, but whether it can consistently earn more will require several more quarters to reveal. (Author: Xing He)
Risk Disclaimer: The above content only represents the author's view. It does not represent any position or investment advice of Futu. Futu makes no representation or warranty.Read more
13K Views
Report
Comment (1)
Write a Comment...
1
1